GetCoattail Research — The Filing Tape #203. Petróleo Brasileiro S.A. (PBR) through six filing lenses, as of the latest filings. Past patterns are not a promise of future results. For education only — not investment advice.
The Hype
Petrobras is in front of readers on October 26, 2026, for a political reason, not an earnings reason. The Wall Street Journal's "Stocks to Watch" for October 26 reports that Brazil-linked shares slid after Luiz Inácio Lula da Silva unexpectedly beat Flávio Bolsonaro in Sunday's election: XP tumbled more than 40% premarket, Petrobras U.S. shares slid more than 20%, and MercadoLibre fell 10%. Those premarket moves are cited as the attention story, not verified here — the price file ends October 2.
The price file does show a violent year underneath that headline. PBR closed 2025 at $11.85, stood at $20.75 by March 31, 2026, then fell 22.1% in Q2 to $16.16 by June 30, and closed the price file on October 2 at $21.65 — 34.0% above its June 30 close and 82.7% above its 2025 year-end close. The daily refresh (cross-source) puts the October 23 close at $26.16 — 61.9% above its June 30 close and 20.8% above its October 2 close. What did the tracked holders, the broad market, insiders, members of Congress, and the control register actually do in the quarter when the price fell?
The Tape
| Lens | As of | What the filings show | Direction vs prior period |
|---|---|---|---|
| Superinvestors (13F) | Jun 30, 2026 | 7 of 147 tracked managers hold; 206,095,387 ADR shares across both classes ($3,325.76M reported). GQG Partners is 93.7%. | Verified continuing cohort shares +8.6%; no new holders; 1 exit in the Q1 register; register = cohort, residual 0 |
| All institutions (13F) | Jun 30, 2026 | 623 filers hold 1,030,704,053 shares ($17.19B reported). | Shares +6.28%; filers +20; reported value −16.63% |
| Insiders (Form 4) | Oct 2, 2026 | 0 buys, 0 sells in 90 days (P/S codes); 1 buy and 1 sell in the parsed corpus. | 90-day window is silent; the corpus itself spans only Apr 6 – Aug 24, 2026 filing dates |
| Congress | Oct 3, 2026 | No transactions in any congress file. | None — no House row, no Senate row, no member-file row |
| 13D/G | Jul 20, 2026 | 6 filings across both classes; BNDES Schedule 13D/A filings reach 17.59%. | Control register holds activist-form filings; the agg file covers only one class (see below) |
| Short interest | Sep 15, 2026 | 31,099,792 shares short, 1.25 days to cover, 0.42% of underlying shares outstanding (indicative — see Limits). | Five straight falls from Jun 30; 59.3% below the Dec 2021 peak; −9.9% year over year |
Chart: PBR through six filing lenses — who is actually there?
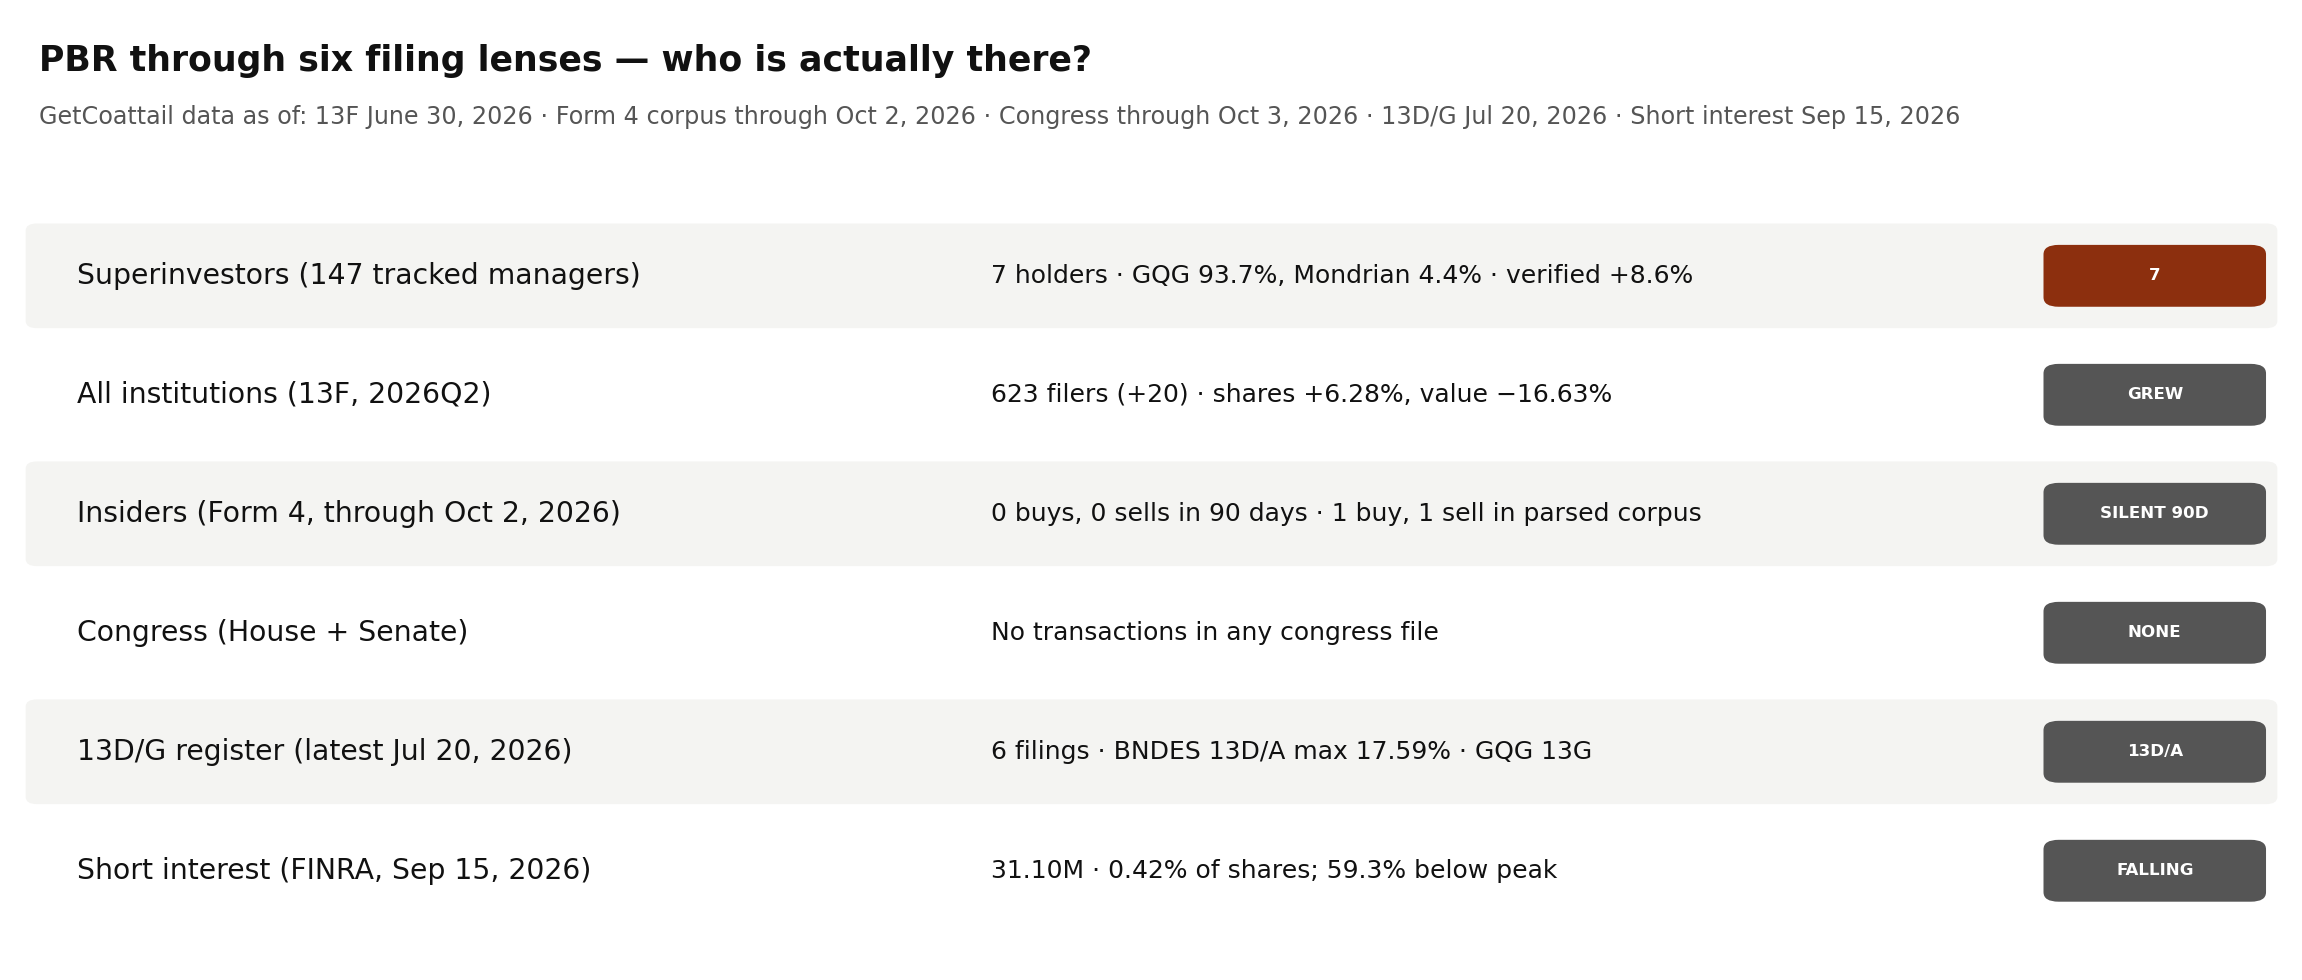
Superinvestors. The tracked register for PBR is, in substance, one manager's position with six footnotes. Seven of 147 tracked managers hold 206,095,387 ADR shares across both classes — $3,325,762,712 reported — and the largest holder alone is 93.7% of it. GQG Partners holds 193,198,230 shares (5.81% of its portfolio), INCREASED +11.4% (Q1 pair 173,440,105). Mondrian Investment Partners holds 8,977,218 shares (2.24%), DECREASED −19.2% (Q1 11,104,808). Sarah Ketterer - Causeway Capital Management holds 3,096,624 shares (0.49%), INCREASED +107.0% (Q1 1,495,664). DJE Kapital holds 697,963 shares (0.21%), DECREASED −77.5% (Q1 3,103,800). Richard Pzena - Pzena Investment Management holds 53,138 shares (0.0%), DECREASED −73.0% (Q1 196,970). Thornburg Investment Management holds 42,214 shares (0.01%), DECREASED −87.8% (Q1 345,693). Dodge & Cox Funds holds 30,000 shares (0.0%), DECREASED −3.8% (Q1 31,200). All seven continuing labels recompute exactly, under both pairing methods.
The class split matters more here than in any recent Filing Tape: the tracked file groups two ADR classes under the single ticker PBR, and their share counts are not one security's position. The 408 class (filed "SPONSORED ADR") holds 202,945,625 shares (98.5%, $3,279,650,197); the 101 class (filed "SP ADR NON VTG", non-voting) holds 3,149,762 shares (1.5%, $46,112,515), split between Causeway and Pzena only. GQG is 95.2% of the 408 class alone. Blended implied price $16.14 is 0.1% below the June 30 close, but by class the 408 holders imply exactly $16.16 while the 101 holders imply $14.64 — two prices for two classes.
The verified continuing cohort grew in the quarter the price fell: the 7 holders held 189,718,240 shares in Q1, so the cohort added 16,377,147 shares, or 8.6%, in Q2. That growth is entirely GQG plus Causeway: GQG added 19,758,125 shares and Causeway added 1,600,960, while the other five cut a combined 4,981,938 shares. The Q2 register is exactly the cohort, and the Q1 register is exactly the cohort's Q1 pairs plus one exited holder, Howard Marks - Oaktree Capital Management, with 6,089,413 shares in Q1 and nothing in Q2. The cohort is 20.0% of the full market's reported PBR shares — but 93.7% of it is GQG.
All institutions. The broad market added shares in Q2 while the price fell, so its reported value fell anyway. Filers rose by 20 to 623, of which 614 are long, while reported shares rose 6.28% (+60,875,445 shares to 1,030,704,053). Reported value fell 16.63% to $17.19 billion — value down while shares rose, because the implied price fell from $21.26 at March 31 to $16.67 at June 30, tracking the price file's 22.1% Q2 fall. 571 filers entered and 551 exited, net +20. Excluding the tracked cohort, other institutions hold 824,608,666 shares — the broad market's Q2 share growth is 3.7 times the tracked cohort's growth, so the cohort is a concentrated version of the broad move. One counting trap is stated plainly: the two by-CUSIP fixture rows sum to 784 holders against the by-ticker row's 623, because a filer holding both ADR classes counts once in the by-ticker row and twice in the by-CUSIP sum. Shares and value match exactly across the two views; only the holder count differs, and the by-ticker count is quoted.
Insiders. This lens is silent in the recent window and nearly silent across the whole parsed corpus — and the corpus itself is short. In the 90 days to October 2, 2026, insiders reported zero open-market buys and zero open-market sells: 6 filings, 0 buy transactions, 0 sell transactions. Across the parsed corpus, there is exactly one buy and one sell, both by the same person — Laureano Angelica Garcia Cobas, Chief Commercial Officer, in a single filing dated April 14, 2026: a 19-share sell at $9.09 on April 1 and a 1,000-share buy at $9.49 on April 2, both officer transactions. Those sizes are trivial against a 206-million-share tracked register, and their implied prices ($9.49 and $9.09) sit below the price file's one-year range of $11.54–$22.03, so the article reports them as filed, flags the mismatch, and draws no conclusion from them. The key qualifier is the corpus span: parsed files for this issuer cover filing dates April 6, 2026 to August 24, 2026 only, so "all" means the whole parsed corpus, not a multi-year history. The 90-day window's 6 filings are all dated August 24, 2026, and none carries any non-derivative transaction code.
Congress. This lens is blank, and the blank is reported, not interpreted. There is no PBR row in the combined file, no House row, no Senate row, and no member-file row through October 3, 2026. That is "no congressional transactions in the files", not proof that no member ever traded PBR outside these files' coverage. Had there been transactions, they would be member-disclosure aggregates, not Form 4 insider transactions, and would never be added to insider totals.
13D/G. The control register holds this article's most unusual finding — and a disagreement between its own data files. The parsed register across both classes holds 6 filings: 3 Schedule 13D/A forms, 1 Schedule 13G form, and 2 Schedule 13G/A amendments, from 4 distinct reporter names. The largest reported percentage is 17.59% for Banco Nacional de Desenvolvimento Economico e Social - BNDES (957,806,254 shares, event May 19, 2026, filed May 21, 2026, SC 13D/A). The latest filing is a BNDES SC 13D/A dated July 20, 2026 (event July 16, 2026), reporting 730,495,645 shares at 13.41% and 865,743,903 shares at 15.90% under the two BNDES reporter names. Across the three BNDES events, each reporter's percentage stepped down: 15.10% to 14.35% to 13.41% for BNDES Participacoes S.A., and 17.59% to 16.83% to 15.90% for Banco Nacional de Desenvolvimento Economico e Social - BNDES. Percentages are as reported; denominators differ by filing date and are not recomputed, and the two BNDES rows within one filing are not summed — related entities reporting overlapping positions, not additive holdings. GQG's 13G history on the 408 class: 237,236,034 shares at 6.38% (event December 31, 2024, filed February 11, 2025), then two prints showing 0.0 shares at 3.88% (event November 30, 2025) and 5.03% (event May 19, 2026), quoted as reported — no share count is claimed for those rows. The disclosure: the aggregate file covers the 408 class only (3 filings, max 6.38%, latest May 22, 2026) and misses all three BNDES filings on the 101 class. The article uses the parsed register, not the aggregate, and says so.
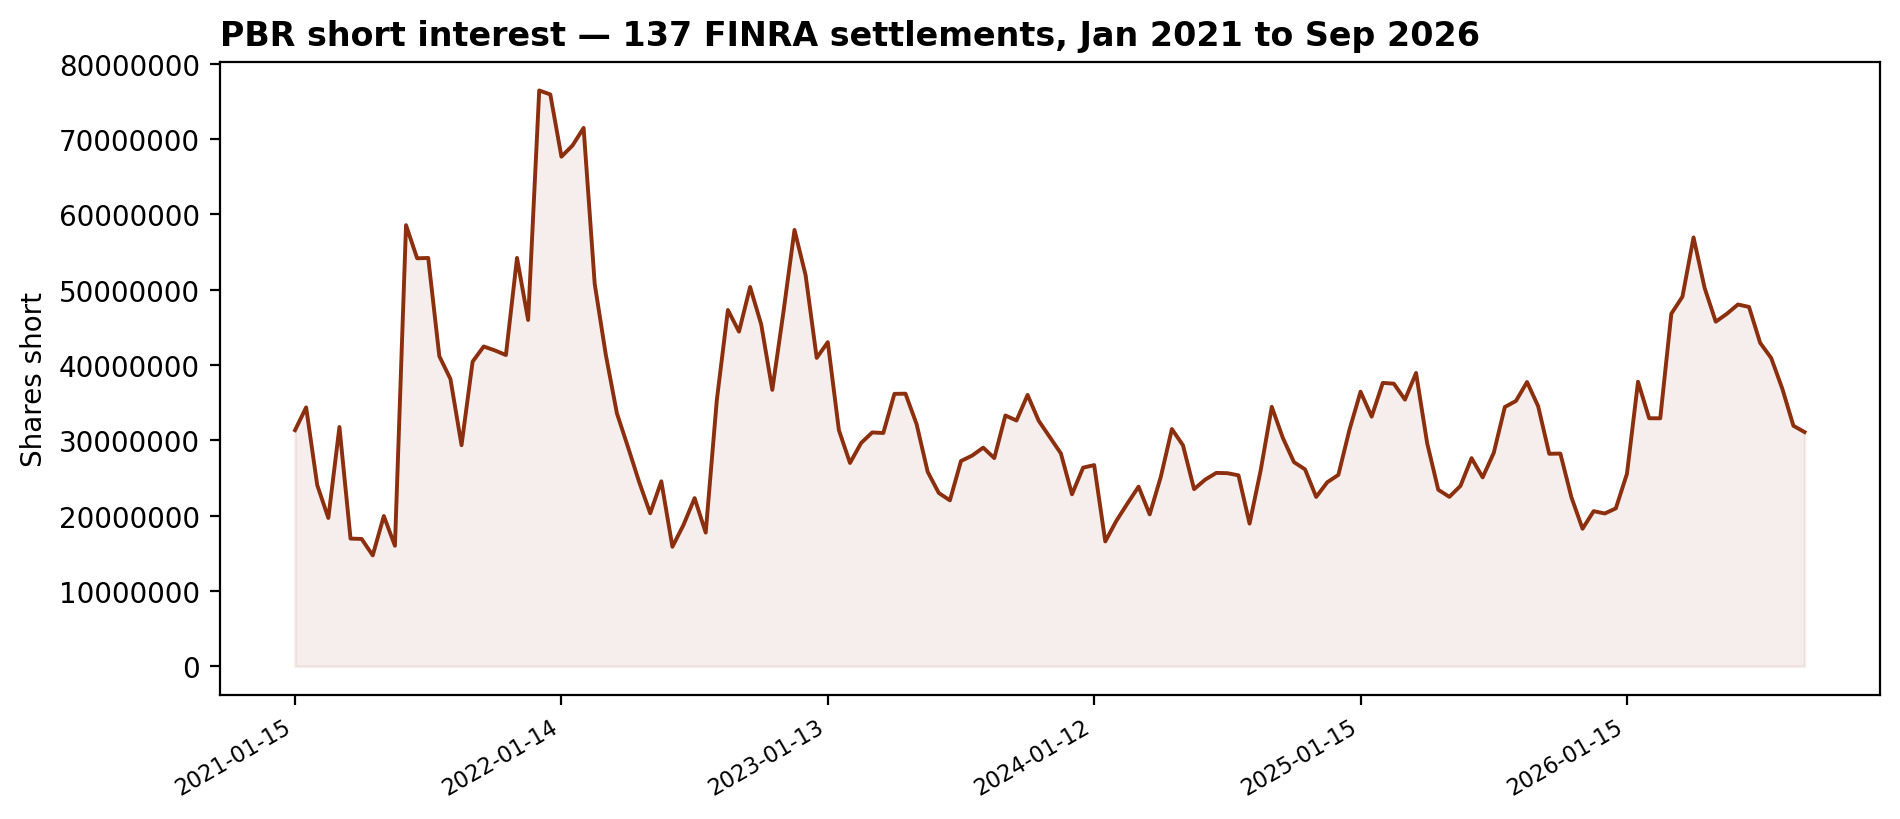
Short interest. The bear trade fell all summer and sits well below its peak. FINRA short interest stood at 31,099,792 shares at September 15, 2026, with 1.25 days to cover and 0.42% of the 7,442,231,382 shares outstanding — indicative, because the denominator is underlying shares while the series is the ADR. That latest settlement is 59.3% below the series peak of 76,461,668 (December 15, 2021), 2.6% below the prior settlement (31,928,583 at August 31), 34.8% below June 30 (47,713,240), and 9.9% below the year-ago figure (34,530,510 at September 15, 2025). The last six settlements — 47,713,240, 42,950,958, 40,920,034, 36,847,350, 31,928,583, 31,099,792 — are five straight falls. One early-series break is flagged, not treated as a signal: a 3.663× step from May 28 to June 15, 2021 (15,991,804 to 58,574,499).
The Gap
The attention story and the filing tape disagree about timing, and the tracked register hides its own split behind the headline count. The October 26 selloff is a political-news event after the tape's June 30 snapshot: nothing in the June filings can confirm or refute a move driven by a Sunday election result, and the September 15 short-interest print predates the election too, so the five straight falls in short interest are the pre-election baseline. Within the quarter the tape does cover, the tracked cohort added 8.6% and the broad market added 6.28% in shares while the price fell 22.1% — accumulation into a falling price, not flight from it — but 93.7% of the tracked story is GQG alone, and the second-largest holder cut 19.2%. The control register adds the one filing-based political thread: BNDES filed three activist-form amendments in May, June, and July 2026 with stepping-down percentages, while the aggregate file shows none of it. Insiders and Congress add nothing: no open-market insider transaction in 90 days, no congressional transaction in any file.
What Would Change the Picture
Nothing above is a recommendation. It is a record. What would change it:
- 1. Q3 13F season (filings due by November 16, 2026). Watch whether GQG adds again from 193,198,230 shares or trims after +11.4% in Q2, whether any new holder appears, whether Mondrian keeps cutting, and whether Oaktree returns after exiting 6,089,413 shares.
- 2. A first open-market insider transaction after October 2, 2026 would end a 90-day window with no P/S transaction — and a first transaction by anyone other than the corpus's single trader would change a lens resting on two tiny, price-mismatched prints.
- 3. A first congressional transaction would change a lens that currently holds nothing.
- 4. A new Schedule 13D/A filing, a new reporter above 17.59%, or GQG's 13G share count reappearing (its two latest prints show 0.0 shares) would change a control register whose largest percentages belong to BNDES and are stepping down.
- 5. Short-interest direction. A fall below the September 15 level of 31,099,792 — or a rise back toward the June 30 level of 47,713,240 — in a post-election settlement would each tell a different story about a bear position that fell five straight settlements into September.
As-of & Limits
| Lens | As of | Limit or note |
|---|---|---|
| Superinvestors (13F) | Jun 30, 2026 | 13F figures are as of June 30, 2026, the quarter-end. Funds have up to 45 days after quarter-end to file, so this is the most recent complete picture — and it is always a lagging one. Both ADR classes (CUSIPs 71654V101 and 71654V408) are counted as long rows; no option rows. Combined share totals sum two classes and are labelled as such everywhere; the class split (408: 202,945,625 shares; 101: 3,149,762 shares) is the primary figure. All continuing labels recompute exactly under both pairing methods. Both registers reconcile exactly with residual 0; one exit (Oaktree, 6,089,413 Q1 shares), no new June holders. |
| All institutions (13F) | Jun 30, 2026 | Reported value includes option rows by definition; implied price ($16.67) is not a price check. Value fell while shares rose because the implied price fell from $21.26 to $16.67. By-ticker holder count (623) is de-duplicated across classes; the by-CUSIP holder sum (784) double-counts dual-class filers and is never quoted. |
| Insiders (Form 4) | Oct 2, 2026 | This lens counts only P and S codes. In 90 days: 6 filings, 0 buys, 0 sells; in the parsed corpus: 1 buy (1,000 shares, $9,490.00) and 1 sell (19 shares, $172.71), both by Laureano Angelica Garcia Cobas, both officer transactions. Implied prices ($9.49 buy, $9.09 sell) sit below the price-file one-year range ($11.54–$22.03) and are flagged, not explained away. The parsed corpus covers filing dates April 6, 2026 to August 24, 2026 only. The scan (32 files, issuer CIK 1119639) matches the aggregate exactly. |
| Congress | Oct 3, 2026 | No transactions: no combined row, no House row, no Senate row, no member-file row. Reported as "no congressional transactions in the files", not as proof about trading outside these files' coverage. Congress findings are member-disclosure aggregates, not Form 4 insider transactions, and are never added to insider totals. |
| 13D/G | Jul 20, 2026 | Parsed register (6 filings) is primary. The aggregate file covers the 408 class only (3 filings, max 6.38%, latest May 22, 2026) and misses the three BNDES 13D/A filings on the 101 class — agg-vs-parsed does NOT match, and that mismatch is disclosed. Filing percentages are as reported in each filing; denominators differ by filing date and are not recomputed. Reporter rows within one filing are not summed. GQG's two latest prints show 0.0 shares and are quoted as reported. Reporter-row sums across dates are not economic totals. |
| Short interest | Sep 15, 2026 | Shares-outstanding count is underlying common shares as of December 31, 2025, while the short series is the ADR — the 0.42% figure is indicative. One early-series break (3.663×, May 28 → Jun 15, 2021) is flagged; the only flag rows are two revision flags. |
| Prices | Oct 23, 2026 (fresh close) | Price file ends Oct 2, 2026; the Oct 23 close ($26.16) is cross-source (chart_stats) and labelled as such. The October 26 premarket slide (more than 20%) is a WSJ-reported figure cited as the attention story, not a price-file figure. The price file's splits field is empty and its rows show no break. |
| Fundamentals | FY2024 | Recorded market capitalisation uses the record's own price_close ($23.80 as of Oct 6, 2026), not the Oct 2 close, and is quoted only as the record's figure. The record itself notes the FPI caveat: share count is underlying shares and the close may be ADR-based, so the market cap may not reflect the ADR ratio. Shares outstanding are a point-in-time count as of December 31, 2025. |
| Hype source | Oct 26, 2026 (WSJ Stocks to Watch) | WSJ "Stocks to Watch" live coverage for October 26, 2026 (Brazil election result; XP more than 40% premarket, Petrobras more than 20%, MercadoLibre 10%) — cited with link as the attention story, not as figures this article verifies. Price moves are measured from the price file. |
Methodology & disclaimer: 13F holdings are long ADR shares unless stated; reported values include option rows for the all-institutions lens by definition. Short interest is FINRA twice-monthly settlements. Trading costs and taxes are not reflected in any figure. Past patterns are not a promise of future results. For education only — not investment advice.
This article describes filings and market data for education. It is not investment advice. Data: SEC EDGAR 13F (as of June 30, 2026, filed within 45 days), Form 4 corpus checked through October 2, 2026 (32 parsed files for issuer CIK 1119639, filing dates April 6, 2026 to August 24, 2026), House/Senate disclosures through October 3, 2026, SC 13D/G parsed register through July 20, 2026, FINRA short interest at September 15, 2026 settlement. 13F covers long positions of $100M+ managers only and is always a lagging picture. Trading costs and taxes are not reflected.
Related research: Five of 147: Dodge & Cox Is 73.8% of the Tracked Norfolk Southern Stake — and the Cohort Cut 48.9% in Q2 · Seven of 147: Edgewood Is 49.8% of the Tracked Blackstone Stake — and the Cohort Cut 26.0% in Q2 · Track the tape on PBR's stock page and the 13F filing season hub.
Revision history: v1.0 — October 26, 2026. Initial publication. Signals and lens aggregates: pbr_lens_data.csv. Short-interest series: pbr_short_interest_series.csv.