GetCoattail Research — The Filing Tape #171. Dollar General (DG) is Zacks' Bull of the Day on October 23, 2026, carrying a Zacks Rank #1 (Strong Buy) after a run that took the stock roughly 11% above our October 2 file close. The filings show 8 of 147 tracked funds holding 18,695,423 shares of Dollar General common stock, $2.15 billion reported: Richard Pzena's Pzena Investment Management is 54.7% of that stake and added 48.2% in Q2; the verified continuing cohort grew 27.4%; insiders have never recorded an open-market buy in our parsed record; the full 13F market reported 14.38% more shares; and short interest sits at its lowest since the January 2025 peak.
① The Hype
On October 23, 2026, Zacks Equity Research named Dollar General Corp. (DG) its Bull of the Day, carrying a Zacks Rank #1 (Strong Buy). A day earlier, the same outlet called it a "Strong Value Stock": VGM Score B, Value Style Score B, a forward P/E of 16.65, 13 analysts raising estimates in the last 60 days for fiscal 2027, a consensus estimate of $7.94, and an average earnings surprise of +19.1%.
The numbers behind the designation: on October 21, Zacks reported DG closing at $132.12, down 1.54% that day — but up 9.43% in the run before it, outpacing both the Retail-Wholesale sector (+4.75%) and the S&P 500 (+0.97%). The outlet's consensus looks for the upcoming quarter to deliver EPS of $1.39 (+8.59% year over year) and revenue of $11.13 billion (+4.51%), with the full fiscal year at $7.94 per share and $44.55 billion in revenue (+15.91% and +4.27%). The valuation framing is that DG trades at a forward P/E of 16.91 against an industry average of 21.73, with a PEG of 1.78 against 1.85 for Retail - Discount Stores — a discount store priced like one, in a good way.
Our price file ends October 2, 2026, so we cannot verify the rally that follows. Through that date, DG closed at $118.94 — down 3.0% in Q2 ($118.73 to $115.11), down 10.4% year to date, 23.9% below its February 27 high of $156.24, and 24.0% above its November 2025 low of $95.94. The Bull of the Day call sits on top of a stock that has been climbing out of a deep drawdown.
That is the story the market is reading. The filings tell their own version.
② The Tape
| Lens | As of | What the filings show | Direction vs prior period |
|---|---|---|---|
| Superinvestors (13F) | Jun 30, 2026 | 8 of 147 tracked funds hold 18,695,423 shares, $2.15B reported; Pzena 54.7% | Verified continuing cohort +27.4% |
| All institutions (13F) | Jun 30, 2026 | 1,136 filers, 215,354,067 shares | −3 filers; shares +14.38% |
| Insiders (Form 4) | Through Oct 2, 2026 | 0 open-market buys in the record; 1 officer sell in 90 days ($0.73M) | Selling, never buying |
| Congress | Through Oct 3, 2026 | No disclosed trades in our record | None |
| 13D / 13G | Through Aug 7, 2026 | State Street 4.9% passive (latest); Vanguard Capital 7.51% max | Latest print is passive |
| Short interest (FINRA) | Sep 15, 2026 | 6,030,543 shares; 2.73% of shares outstanding | −53.4% from Jan 2025 peak |
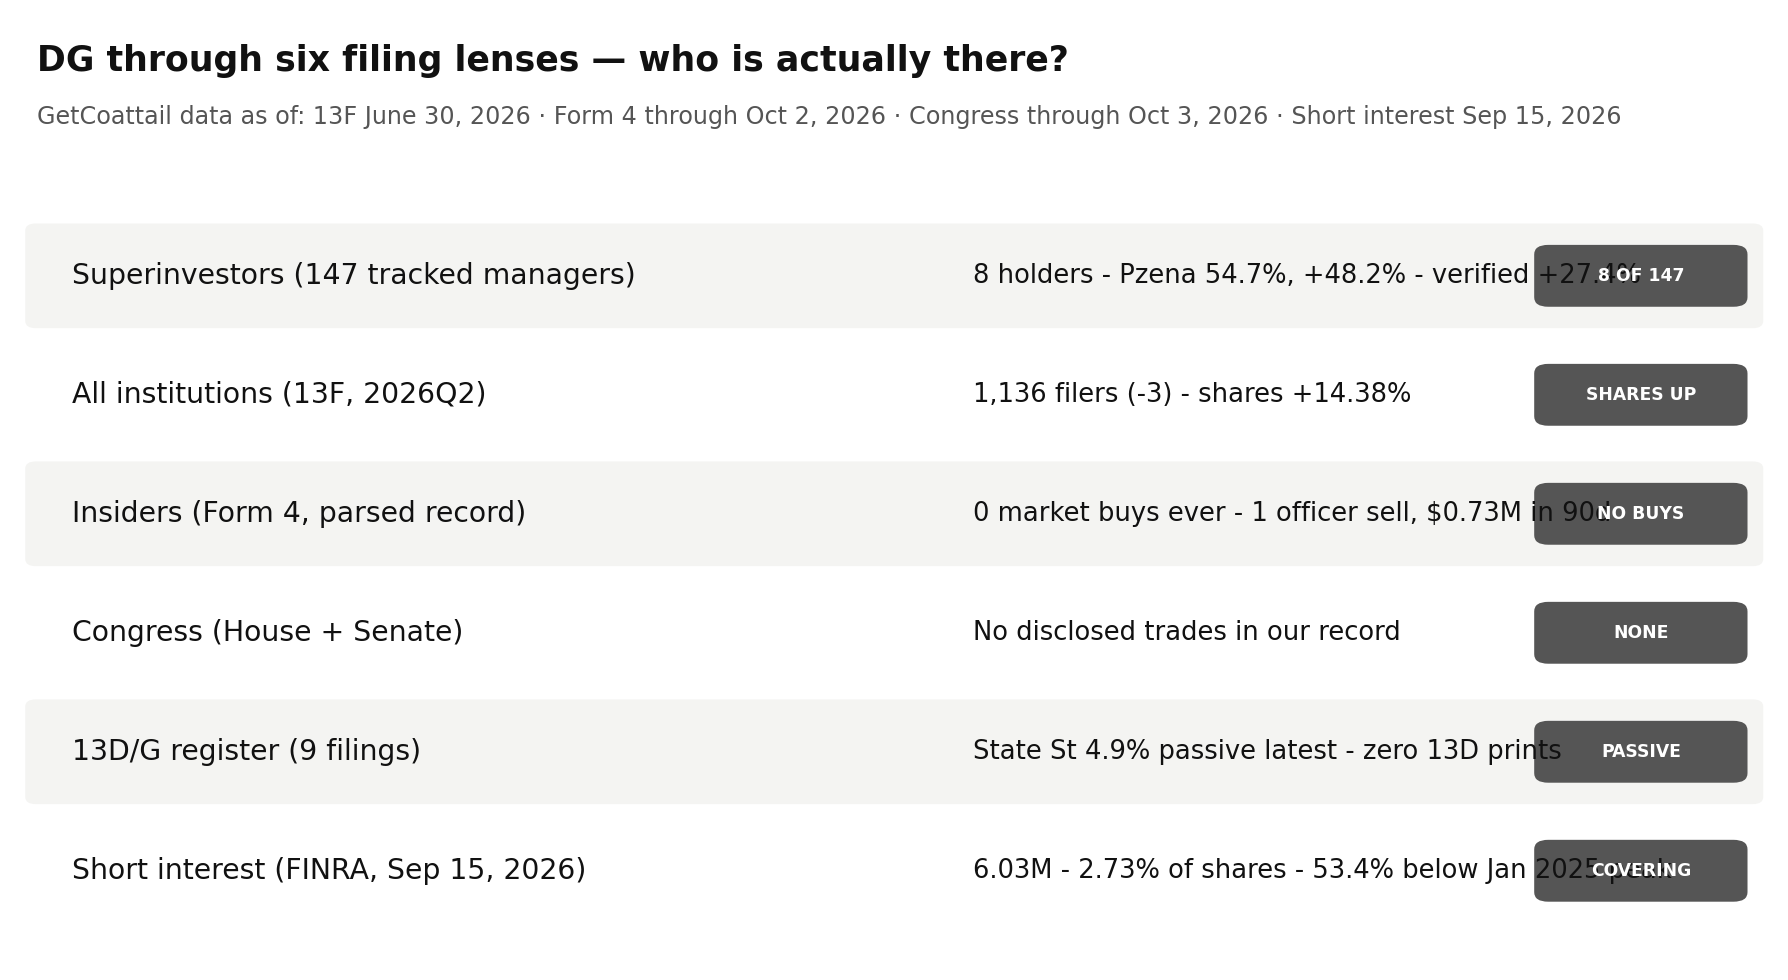
Superinvestors. Eight of 147 tracked funds held DG common stock at June 30, 2026: 18,695,423 shares, $2.15 billion reported — 8.68% of all 13F-reported DG shares. The register has one dominant name. Richard Pzena's Pzena Investment Management holds 10,222,060 shares (54.7% of the cohort, a 3.45% portfolio weight) and added 48.2% in Q2. Then comes First Eagle Investment Management with 4,500,001 shares (24.1% of the cohort, a 0.85% weight, +1.0%), ACR Alpine Capital Research with 1,727,299 shares (9.2% of the cohort, a 2.82% weight, +53.9%), Thomas Gayner's Markel Group with 869,250 shares (unchanged), Flossbach von Storch with 705,223 shares (+3.7%), Christopher Bloomstran's Semper Augustus with 665,307 shares (+2.6%, an 8.66% portfolio weight — the heaviest position in the register by weight), Mondrian Investment Partners with 4,095 shares (unchanged) and Ruane Cunniff with 2,188 shares (unchanged).
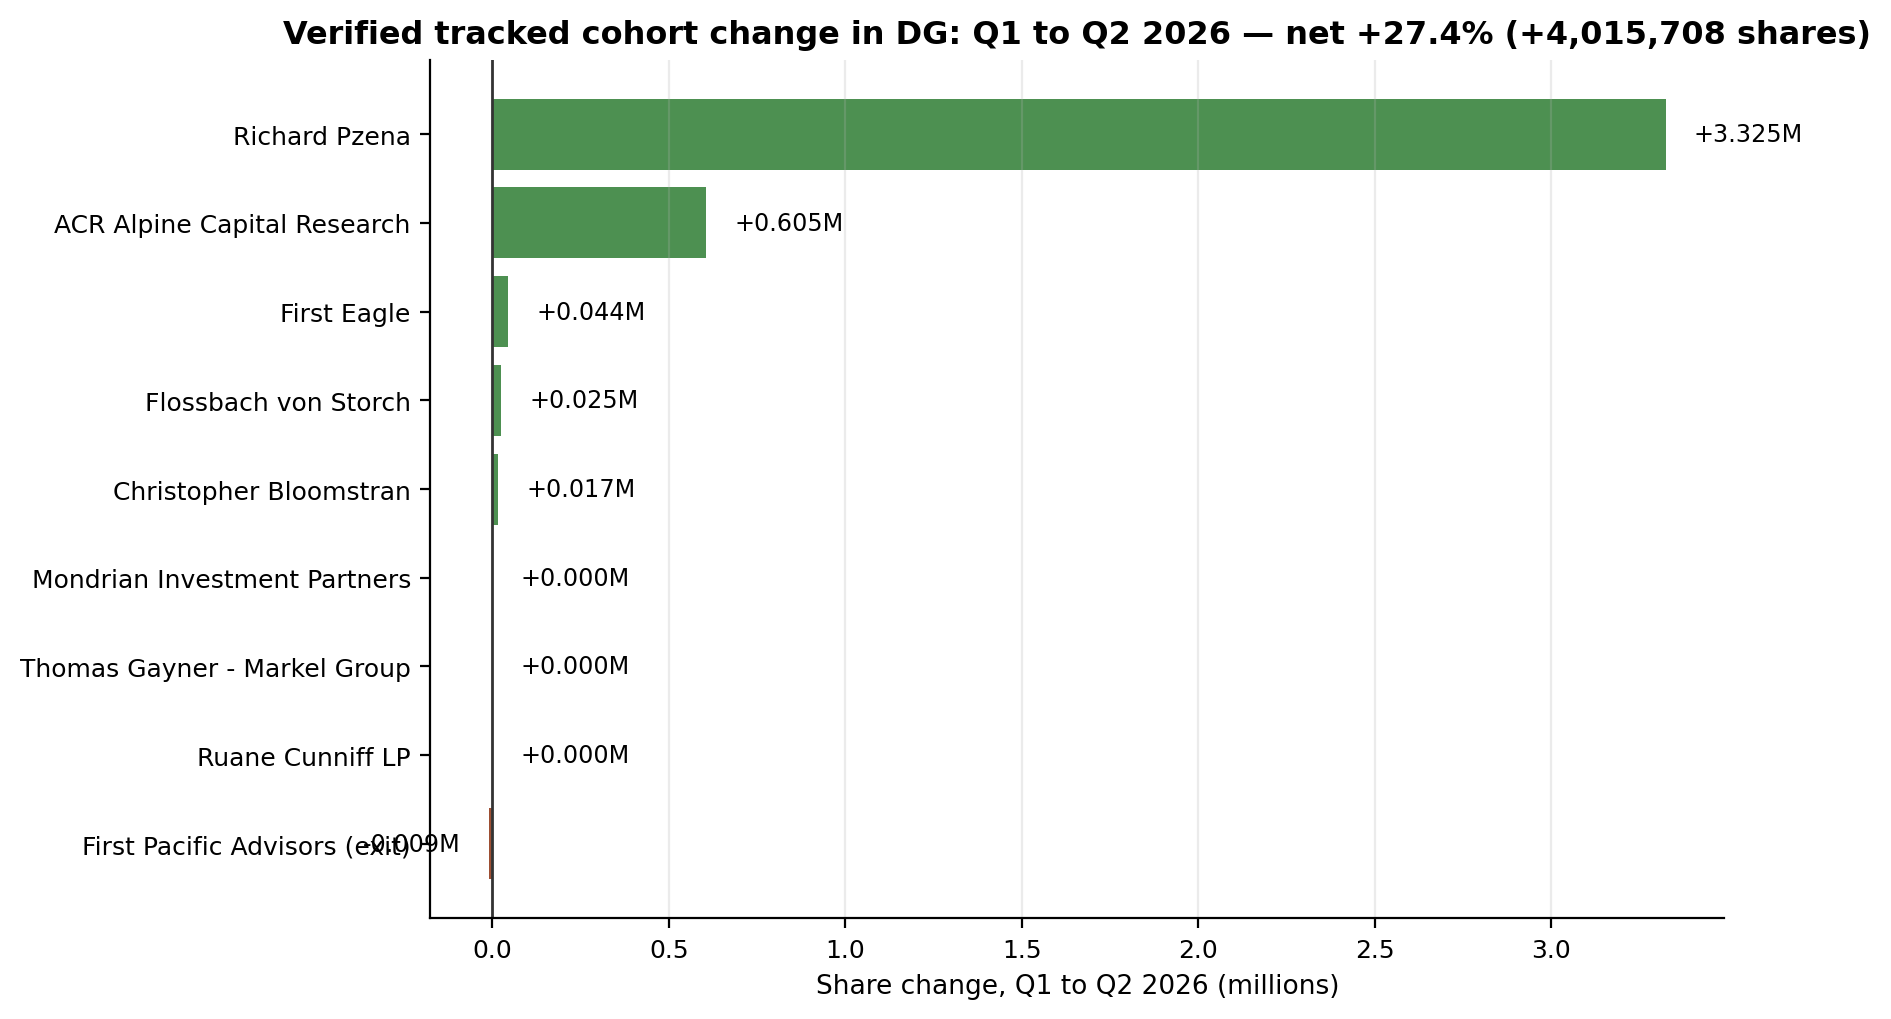
Direction labels lean one way: 5 increased, 3 unchanged, none new, none cut. The verified continuing cohort (all 8 holders, confirmed by two independent pairing methods with a register that reconciles to zero residual in both quarters) grew 27.4%: 14,679,715 shares to 18,695,423, a net +4,015,708. The decomposition: Pzena added 3,324,519 shares (6,897,541 → 10,222,060, +48.2%); ACR added 604,734 (1,122,565 → 1,727,299, +53.9%); First Eagle added 44,379 (+1.0%); Flossbach von Storch added 24,996 (+3.7%); Bloomstran added 17,080 (+2.6%); the other three held still. No holder cut a single share. First Pacific Advisors exited entirely, at 9,077 shares the smallest line in either register. The cohort's implied price of $115.11 lands exactly on the June 30 close of $115.11. No September early filer holds this name.
All institutions. The broad 13F market was also buying, though less aggressively than the tracked value crowd. Filers slipped to 1,136 (−3, −0.26%) while reported shares grew 14.38% to 215,354,067 — a net add of 27.07 million shares; reported value rose 11.2% to $24.76 billion (value includes option rows, so shares are the cleaner signal). The single-CUSIP fixture check matches exactly. The tracked cohort's +27.4% is the sharper edge of a register that was broadly adding.
Insiders. The parsed record is a one-way ledger: 80 filings from January 3, 2025 to September 3, 2026, zero open-market buys, 20 sells totaling 83,862 shares and $10.47 million from 9 sellers. Over the last year, 47 filings show 9 sells of 68,646 shares ($9.00 million) from 7 sellers — every one an officer row. In the last 90 days: a single filing, a single officer sell — REARDON KATHLEEN A, 5,578 shares, $732,554.84, at an implied $131.33 that sits inside the window's price range. Implied sale prices pass their price gates in every window (w90 $131.33, w1y $131.16, full-record $124.88). Our site's insider aggregate matches the 90-day window exactly. There is no late-reporting artifact to qualify here — there are simply no P-coded transactions, ever.
Congress. Our record has nothing. The combined aggregate (through October 3, 2026), the House aggregate, and the Senate aggregate (through October 1, 2026) carry no DG row, and no member file rows mention the ticker. Silence, not signal.
13D / 13G. Nine filings, all passive, zero activist prints. Vanguard Capital Management's 7.51% (16,549,451 shares, filed April 29, 2026, as of March 31) is the register maximum. The latest is State Street Corporation at 4.9% (10,732,866 shares, filed August 7, 2026, as of June 30), followed by Vanguard Portfolio Management at 5.24% (filed July 31, 2026). The aggregate file matches the parsed filings exactly.
Short interest. Shorts have been leaving for a year and a half. From the January 31, 2025 peak of 12,929,026 shares, the series bled to 6,030,543 shares at September 15, 2026 — −53.4% from the peak, −27.0% since the June 30 settlement (8,264,353), and −33.7% versus a year ago (9,096,507). The latest print is 2.41 days to cover and 2.73% of shares outstanding — the lowest since the January 2025 peak (the 137-settlement absolute minimum is an older print from 2021, so this is not an all-time low). In other words: the bear case was at its loudest 20 months ago and has been unwinding through the stock's own recovery — shorts covered while the price climbed out of its November low.
③ The Gap
The market story is Zacks' Bull of the Day: a Strong Buy rating, rising estimates, and a ~9.4% pre-call run. The filings side with that call more than usual in this series — the tracked cohort added a verified 27.4% in Q2, and no holder cut a share. But the details narrow the picture. The +27.4% is not a register-wide embrace: it is Pzena's +3.32 million shares and ACR's +0.60 million against a quarter in which the stock fell 3.0% — two value managers buying the dip, while the other six added little or nothing and none were new.
And the gaps that persist matter more than the alignment. Insiders have never bought a share in the open market across the entire parsed record — 80 filings, 9 sellers, 0 buyers — even as officers collected $9.00 million in sales over the last year. No member of Congress has disclosed a trade. The 13D/G register is 100% passive; no activist has touched the name. The Zacks story is an earnings-and-valuation story (13 analysts raising FY2027 estimates, a +19.1% average earnings surprise) — but the people with the closest view of the business, its insiders, have been sellers, and the only market participants adding conviction are the two value shops that bought the weakness.
One plausible reading is that the short-interest unwind is doing part of the price work the estimates story takes credit for: shorts covered 53.4% of the January 2025 peak by September 15, and the stock's climb from its November 2025 low of $95.94 happened alongside that unwind. We don't know who covered — FINRA prints totals, not names — so this is a temporal coincidence, not a cause. The tape does say the bear case emptied before the Bull of the Day arrived.
④ What Would Change the Picture
Nothing above is a recommendation. It is a record. The next filing cycles will rewrite that record one row at a time — here is what would change the picture, all checkable in future filings:
- 1. The Q3 13F season (deadline November 16, 2026). Do the three unchanged holders (Markel, Mondrian, Ruane) start adding? Does Pzena hold its 10.2 million shares after buying the dip, or take the rally Zacks prices at ~$132? Does the verified +27.4% keep compounding?
- 2. A genuine insider buy. Any open-market purchase in a future Form 4 would be the first in our parsed record — against 20 sells and $10.47 million of selling across it.
- 3. Short interest turning. Shorts covered 53.4% from the January 2025 peak to September 15. A renewed build would signal the bear case is rearming; continued covering through October settlements would confirm the unwind.
- 4. A new 13D. Zero activist prints in our register. A fresh SC 13D would change the register's character from passive to contested.
- 5. Congressional trades. Nothing disclosed now, in either chamber. Any print would be the first data point in an empty record.
⑤ As-of & Limits
| Lens | As of |
|---|---|
| Superinvestors (13F) | Jun 30, 2026 (13F figures are as of the quarter-end; funds have up to 45 days after quarter-end to file, so this is the most recent complete picture — and it is always a lagging one) |
| All institutions (13F) | Jun 30, 2026 (same lag) |
| Insiders (Form 4) | Filings through Oct 2, 2026 (parsed record from Jan 3, 2025) |
| Congress | Through Oct 3, 2026 (Senate through Oct 1, 2026) |
| 13D / 13G | Filings through Aug 7, 2026 |
| Short interest (FINRA) | Settlements through Sep 15, 2026 |
| Prices | Through Oct 2, 2026 (our file) |
Methodology and data notes
- As-of & limits: The lenses rest on different clocks, none live: 13F is a June 30, 2026 snapshot published up to 45 days later; Form 4 windows run through October 2, 2026; Congress aggregates run through October 3, 2026 (Senate through October 1, 2026); 13D/G through August 7, 2026; short-interest settlements through September 15, 2026; the price file ends October 2, 2026. Limits specific to this audit. First, the tracked cohort is 8 managers with one dominant holder — Pzena at 54.7% of the cohort is a 3.45% portfolio weight; the verified +27.4% is Pzena's +3,324,519 shares and ACR's +604,734 against no cuts, not a register-wide move. Second, DG common stock carries a single CUSIP (256677105), and the full-market by-CUSIP row matches the by-ticker aggregate on every field — holders, long holders, shares, reported value, prior holders and prior reported value — so no CUSIP blending question arises. Third, the tracked change labels are verified, not taken on trust: all 8 continuing positions were verified by two methods that agree — a total-value prefix pass and accession identity plus CUSIP-overlap pairing — with each label recomputing exactly from share counts; there are no NEW labels; the single exit (First Pacific Advisors, 9,077 shares) is confirmed in the Q2 register's absence. No September early filer holds this name. The registers reconcile with no remainder: the March 31 register equals the verified continuing holders' 14,679,715 shares plus the exited 9,077 shares; the June 30 register equals the June cohort's 18,695,423 shares exactly (all common stock, no option rows). Fourth, the June cohort's implied price is $115.11 against the June 30 close of $115.11 (+0.00%). Fifth, the full-market aggregate implies $114.97 against the $115.11 close (−0.12%): the aggregate is a reported sum that includes option rows, so its implied price need not equal the close; this audit uses filer counts and share counts as this lens's primary measures and reports the value as reported only. Sixth, the insider lens rests on a single aggregate bucket — this issuer's filings sit under one symbol spelling, "DG", with no case split — cross-checked against a row-level scan of all 80 parsed filings for the issuer (CIK 29534): filing counts, transaction counts, share counts, officer-row counts and values reproduce exactly in every window, and no accession appears under more than one symbol spelling. There are zero P-coded transactions in the entire parsed record; the implied sale prices pass their price gates (the 90-day implied sale price of $131.33, the one-year implied sale price of $131.16 and the full-record implied sale price of $124.88 each sit inside their filing-window close ranges). The 90-day window contains a single officer sell by REARDON KATHLEEN A (5,578 shares, $732,554.84). Form 4 windows in this audit are filing-date windows. Our site's insider aggregate carries a DG row (checked October 23, 2026) and matches the 90-day window exactly: 0 buys, 1 sellTx, $732,554.84. Seventh, the congressional lens is reported across four files: the combined aggregate, the House aggregate, the Senate aggregate and the member files — none carries a DG row; that absence is reported, not interpreted. Eighth, the 5% register holds only passive prints: Vanguard Capital Management's SC 13G (filed April 29, 2026) prints 16,549,451 shares at 7.51% as of March 31, 2026 — the register maximum; State Street Corporation's SC 13G (filed August 7, 2026) prints 10,732,866 shares at 4.9% as of June 30, 2026 — the latest print; Vanguard Portfolio Management's SC 13G (filed July 31, 2026) prints 11,598,896 shares at 5.24% as of June 30, 2026. The parsed totals match the aggregates exactly, and each print is reported individually in the text. Ninth, the short-interest series holds 137 settlements beginning January 15, 2021, so its maximum and minimum describe that span only. Within it, the series carries no discontinuity of 2x or one-half on consecutive settlements on this measure. No row carries a split flag; three rows (April 15, 2021 at 3,096,035 shares; June 15, 2021 at 4,893,961; November 15, 2023 at 5,911,015) carry FINRA revision flags. The series reads 12,929,026 (Jan 31, 2025, the maximum) → 9,096,507 (Sep 15, 2025) → 8,264,353 (Jun 30, 2026) → 8,090,747 (Jul 15) → 7,524,336 (Jul 31) → 6,509,120 (Aug 14) → 5,887,587 (Aug 31) → 6,030,543 (Sep 15, −53.4% below the maximum). The 2.73% short-interest figure uses 220,616,790 shares from our fundamentals file (a measured period-end count), not a float estimate. Our price file records no split factor for this name. The fundamentals record is status ok: FY2026 revenue $42,724,369,000 and net income $1,512,311,000 are reported as stored. The Zacks figures in The Hype — the Bull of the Day designation, the Rank #1, the Value and VGM scores, the forward P/E and PEG figures, the consensus estimates and earnings surprise — are that outlet's published figures, cited as such, not blended into file-based calculations; our price file cannot confirm or refute post-October-2 price levels.
- Market context sources: Zacks.com, October 23, 2026 ("Dollar General and Las Vegas Sands have been highlighted as Zacks Bull and Bear of the Day": DG named Bull of the Day; Zacks Rank #1 Strong Buy); Zacks.com, October 22, 2026 ("Here's Why Dollar General (DG) is a Strong Value Stock": #1 Strong Buy, VGM Score B, Value Style Score B, forward P/E 16.65, 13 analysts raised estimates in 60 days for fiscal 2027, consensus $7.94, average earnings surprise +19.1%); Zacks.com, October 21, 2026 ("Dollar General (DG) Stock Falls Amid Market Uptick": closed $132.12, −1.54%; shares had gained 9.43% before that session vs Retail-Wholesale +4.75% and S&P 500 +0.97%; Rank #1; Forward P/E 16.91 vs industry 21.73; PEG 1.78 vs industry 1.85; Industry Rank 18, top 8% of 250+ industries; upcoming EPS $1.39, +8.59% y/y; revenue $11.13B, +4.51%; full-year consensus EPS $7.94, revenue $44.55B, +15.91% / +4.27% y/y).
- DG is in the GetCoattail stock-page universe: DG (DG) stock page. Tracked manager page: Richard Pzena - Pzena Investment Management. Series data: dg_lens_data.csv · dg_short_interest_series.csv. Earlier audits: TJX · McKesson.
Past patterns are not a promise of future results. For education only — not investment advice.
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history: v1.0 — October 23, 2026: first publication.