GetCoattail Research — The Filing Tape #176. Danaher through six filing lenses, as of the latest filings. Past patterns are not a promise of future results. For education only — not investment advice.
The Hype
Danaher is having an analyst moment. On TipRanks' "Trending Stocks by Analyst" screener, DHR sits at #9 — 10 Buy ratings, zero Holds, zero Sells, a Strong Buy consensus, and an average price target of $253.86 implying about 10% upside from the screener's reference price (TipRanks trending screener, checked October 24, 2026). The stock closed at $230.50 on October 23, 2026, within about 5% of its 52-week high of $242.80, extending a rebound that began at the May 15 low of $161.91 (the October 2 close of $214.06 was already 32.2% above that low).
The story being told is familiar: a life-sciences and diagnostics compounder — the kind of business analysts reach for when they want "quality" on sale after a drawdown — repairing itself. The question the filings let us ask is different: while the analyst count was unanimous, who was actually holding the stock, and what were the people closest to the company doing with their own shares?
The Tape
| Lens | As of | What the filings show | Direction vs prior period |
|---|
Chart: DHR through six filing lenses — who is actually there?
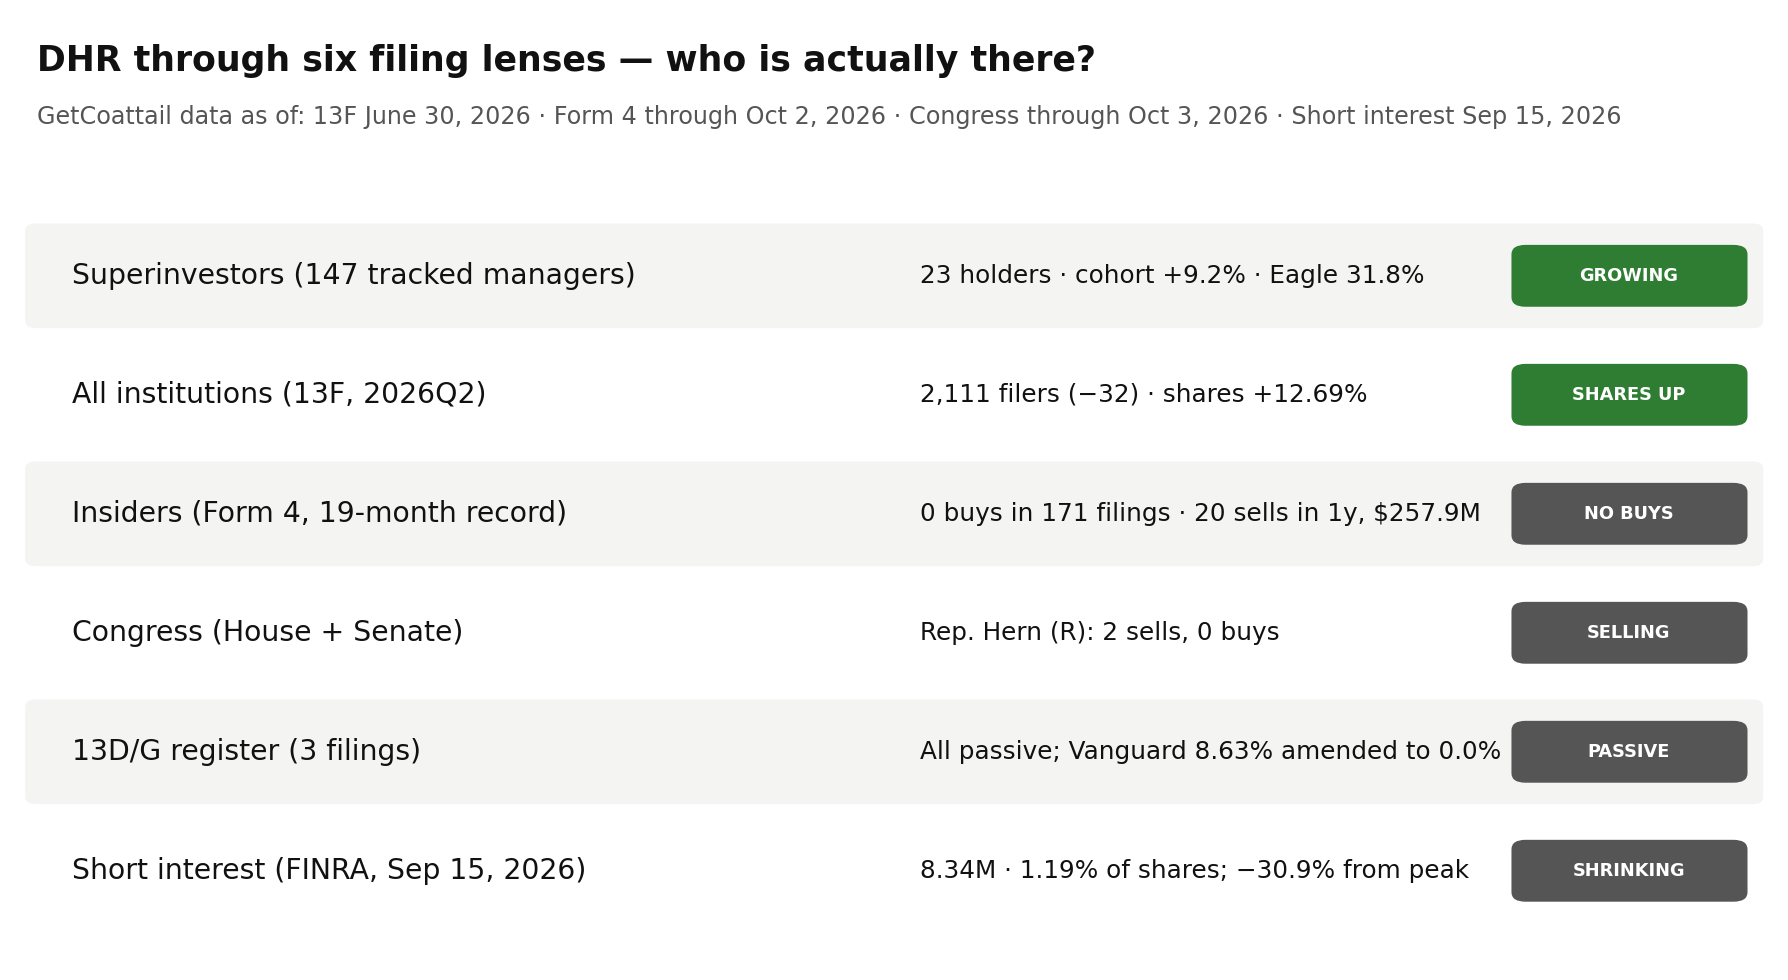
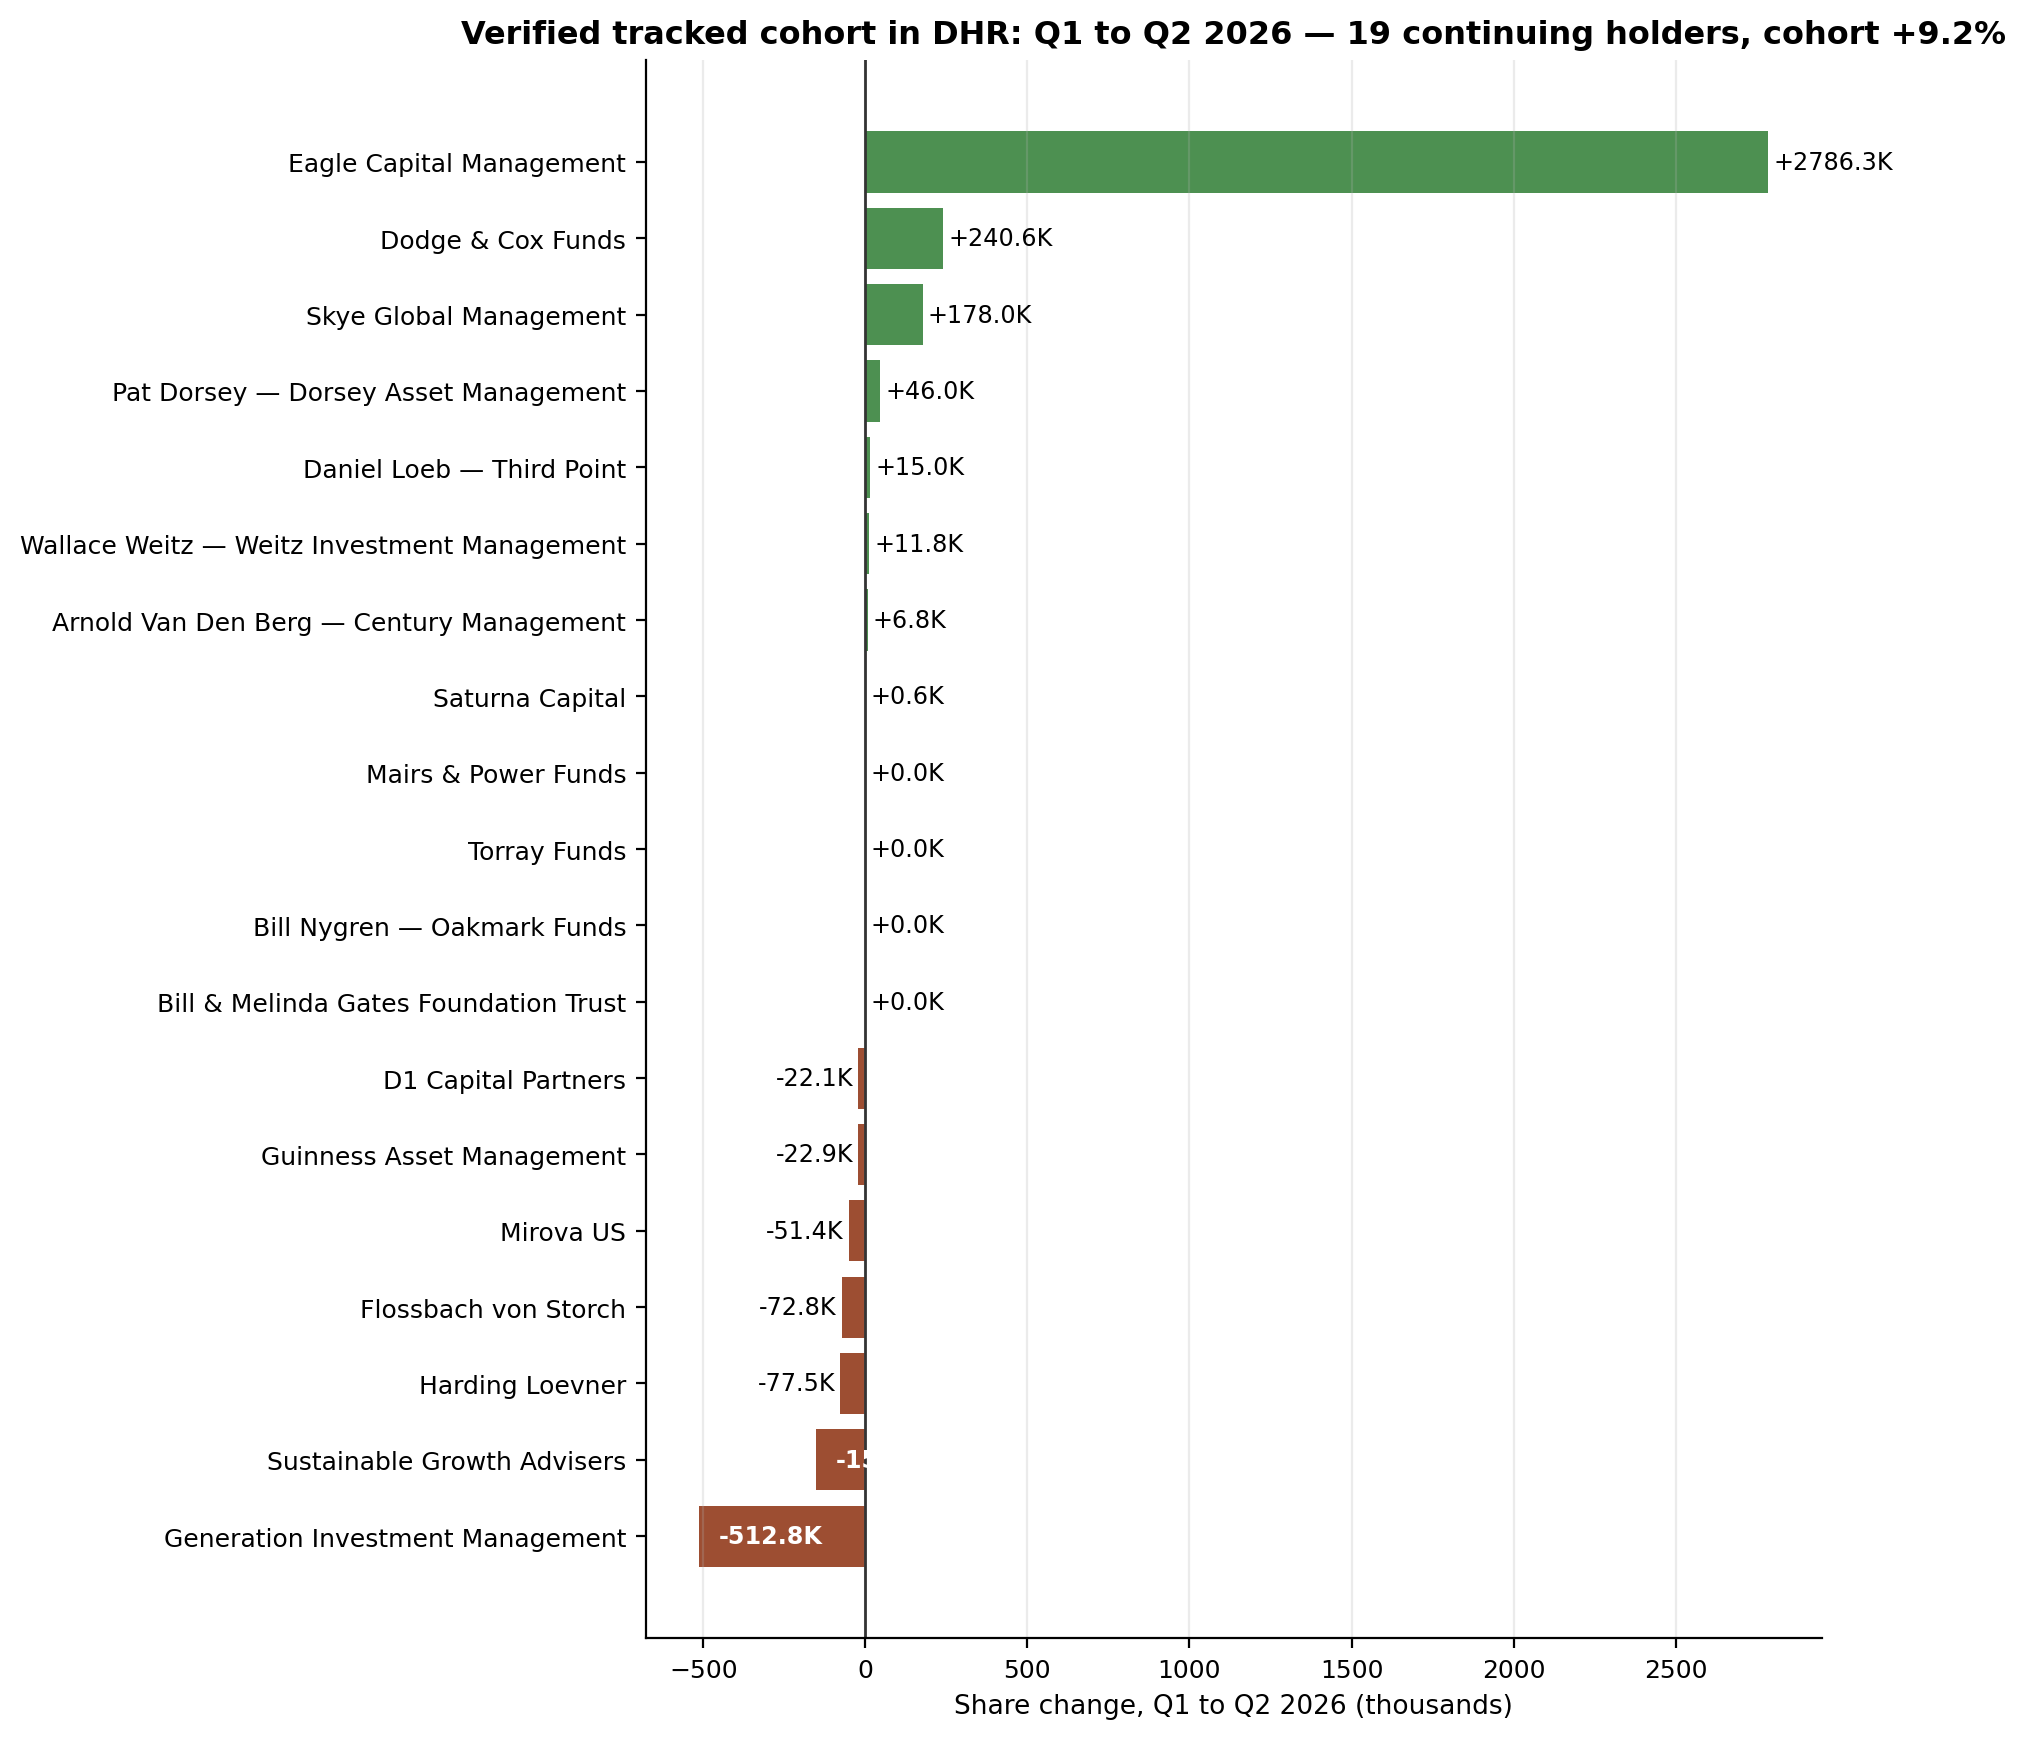
Superinvestors. The June-quarter register shows 23 of the 147 tracked managers holding Danaher common stock — 29,435,724 shares, $5.61B at reported values, about 5.1% of all institutionally reported DHR shares. The concentration is high: Eagle Capital Management's 9,361,490 shares are 31.8% of the cohort, and Generation Investment Management's 6,761,596 are another 23.0% — the top two names are 54.8% of the tracked stake. Eagle's position is the story's engine: it grew its DHR holding 42.4% in Q2 (from 6,575,159 to 9,361,490 shares, a +2,786,331-share add), while Generation trimmed 7.0%.
The verified continuing cohort — 19 managers present in both Q1 and Q2, paired by accession identity and CUSIP overlap with every change label recomputed exactly — grew from 25,680,551 to 28,054,943 shares, +9.2%. The direction mix beneath that: 9 increased, 7 decreased, 3 unchanged, and 4 genuine new positions. The new money is notable for its names: Tiger Global opened 456,000 shares ($86.9M), First Pacific Advisors 564,781 ($107.6M), RTW Investments 230,000, and Perceptive Advisors 130,000. Against that, four managers exited entirely — Maverick (819,679 shares), Axiom (446,062), OrbiMed (265,800), and Edgewood (6,767). The implied cohort price of $190.48 matches the June 30 close exactly, so the share arithmetic is clean.
Two September early filers sit outside the June cohort: Montrusco Bolton cut its DHR stake 14.3% to 912,150 shares, and Matrix Asset Advisors held 1,681 shares unchanged. One bookkeeping note: filer CIK 1172661 is a shared series CIK hosting several funds, so the naive prefix pairing would have double-counted Mirova's verified Q1 row as Matrix's — the register reconciliation forced the correction, and both quarterly registers now reconcile to zero residual.
Chart: verified tracked cohort in DHR — Q1 to Q2 2026 share change.
All institutions. The full 13F market added 12.69% more DHR shares in Q2 (+64,668,817 shares to 574,177,465) even as the filer count slipped by 32 to 2,111 — fewer filers holding more stock. Reported value rose 15.7% to $105.7B. The superinvestor cohort's +9.2% sits inside a broader institutional bid, not against it.
Insiders. The Form 4 record is one-sided. Across 171 parsed filings for Danaher's CIK (record span January 31, 2025 through August 24, 2026; aggregated as of October 2, 2026), there are zero open-market purchases — 0 buy transactions, 0 buyers, in the 90-day, 1-year, and full-record windows alike. In the last year, insiders filed 20 sell transactions covering 1,184,978 shares and $257.9M, from 8 distinct sellers; 18 of the 20 sells were officer sells. In the last 90 days: 3 sells, 58,255 shares, $12.7M, one seller. The parsed-file scan matches the aggregate buckets on every transaction count and value, and the site's insider aggregate matches the 90-day window — this is not a coverage artifact.
Congress. One House member, Kevin Hern (R), reported two DHR sales, the latest on September 2, 2026 (amounts $15,001–$50,000 and $1,001–$15,000). No member of either chamber reported a DHR purchase.
13D/G. The control register is passive-only: three filings, all Schedule 13G. The notable event is an exit — The Vanguard Group's 8.63% position (60,973,344 shares, event December 31, 2025) was amended on March 26, 2026 to 0 shares and 0.0%, i.e., below the reporting threshold. Vanguard Capital Management reported 6.69% (47,383,707 shares) on April 29, 2026. No activist 13D filings.
Short interest. The bear case has been unwinding. FINRA short interest fell to 8,344,032 shares at the September 15 settlement — down 30.9% from the July 31 peak of 12,074,192, down 23.2% from the June 30 settlement, and down 12.4% from a year ago. At 1.19% of the 702,986,054 shares outstanding, with 2.69 days to cover, the short book is small and shrinking.
Fundamentals context. FY2025 revenue was $24,568M with $3,614M net income. The stock's Q2 price move was nearly flat (+0.5%, $189.60 → $190.48) while the tracked cohort added 9.2% — the buying happened into a flat tape, not a rally.
The Gap
The analyst tape and the filing tape agree on the direction of institutional interest but diverge on who is confirming it. The unanimous Buy consensus and the 10%-plus upside target sit alongside a tracked-manager cohort that did, in fact, buy in Q2 (+9.2% verified, plus Tiger Global and three other new positions) and a full institutional market that added 12.7% more shares. The gap is inside the building: Danaher's own insiders have not bought a single share on the open market in the 19-month parsed record while selling $257.9M in the last year, and the only member of Congress on the register was selling too. The passive-register exit — Vanguard's 8.63% 13G amended to zero — is a reminder that the Q2 institutional bid came from active stock-pickers, not index flows. And the short-interest collapse (−30.9% from peak) means one traditional source of future buying pressure (short covering) is already largely spent.
One plausible reading is that professional managers are buying the drawdown repair while insiders see no urgency to add — a split that has historically meant the "smart money" thesis rests entirely on the 13F cohort's judgment, not on insider confirmation. The 45-day 13F lag cuts the other way too: the June picture is the latest complete one, and the September early filers (Montrusco cutting 14.3%) hint the cohort's enthusiasm may already be cooling at the margin.
What Would Change the Picture
Nothing above is a recommendation. It is a record. What would change it:
- 1. An insider open-market purchase. Any Form 4 buy code "P" would end a 19-month, 171-filing drought and would show up on DHR's insider page within days of filing.
- 2. Q3 13F season (filings due by November 16, 2026). Watch whether Eagle's 42.4% Q2 add was the start of a build or a one-quarter move, whether the four new Q2 positions (Tiger Global, First Pacific, RTW, Perceptive) were added to, and whether Generation's trim continued.
- 3. Montrusco's trajectory. The September filer cut 14.3% after cutting in Q2 — a third consecutive cut in the full Q3 filings would confirm cooling at the margin.
- 4. A new 13D or 13G. Any activist 13D, or a fresh 13G above 5% replacing Vanguard's exited 8.63%, would reset the control-register picture.
- 5. Short-interest re-acceleration. Two consecutive settlements of rising short interest after the −30.9% unwind would signal the bear trade is re-engaging.
This article describes filings and market data for education. It is not investment advice. Data: SEC EDGAR 13F (as of June 30, 2026, filed within 45 days), Form 4 parsed filings span January 31, 2025 – August 24, 2026 (aggregated as of October 2, 2026), House/Senate disclosures through October 3, 2026, FINRA short interest at September 15, 2026 settlement. 13F covers long positions of $100M+ managers only and is always a lagging picture. Trading costs and taxes are not reflected.
Revision history: v1.0 — October 24, 2026. Initial publication. Signals and lens aggregates: dhr_lens_data.csv. Short-interest series: dhr_short_interest_series.csv.
Past patterns are not a promise of future results. For education only — not investment advice.