GetCoattail Research — Micron is the memory trade at the centre of the AI build-out: revenue that went from $37.4 billion to $133.2 billion in a year, a stock up roughly 273% in 2026, and search interest in DRAM names breaking out. We ran it through every filing lens we maintain. This time the filings partly agree with the story — and the parts that do not are specific.
Start with the narrative, because it is an unusually well-documented one. Micron, the US maker of DRAM and high-bandwidth memory (HBM) for AI accelerators, reported fiscal 2026 results on September 30, 2026: fourth-quarter revenue of $54.23 billion, full-year revenue of $133.19 billion against $37.38 billion a year earlier, and non-GAAP earnings of $33.42 per share against a $31.61 consensus. Guidance for the next quarter was $61.5 billion of revenue. Management says agreements already cover the vast majority of its calendar-2027 HBM supply, at higher prices. The shares closed at $1,063.96 on October 5, 2026, up 272.78% year to date on quote-provider figures; the MarketBeat consensus target on October 1 stood at $1,375.58 (40 Buys, five Holds). "DRAM stocks" is also a breakout investing search this October, with Micron named as the name at its centre.
Now the filings. GetCoattail tracks the portfolios, trades and disclosures of the investors with the most information about any given company: concentrated superinvestors, institutions as a whole, corporate insiders, members of Congress, and 5% holders. For Micron — the third Filing Tape audit, after IREN and CoreWeave — the record is more mixed than in either earlier audit.
Lens 1: the superinvestors — five names, one position
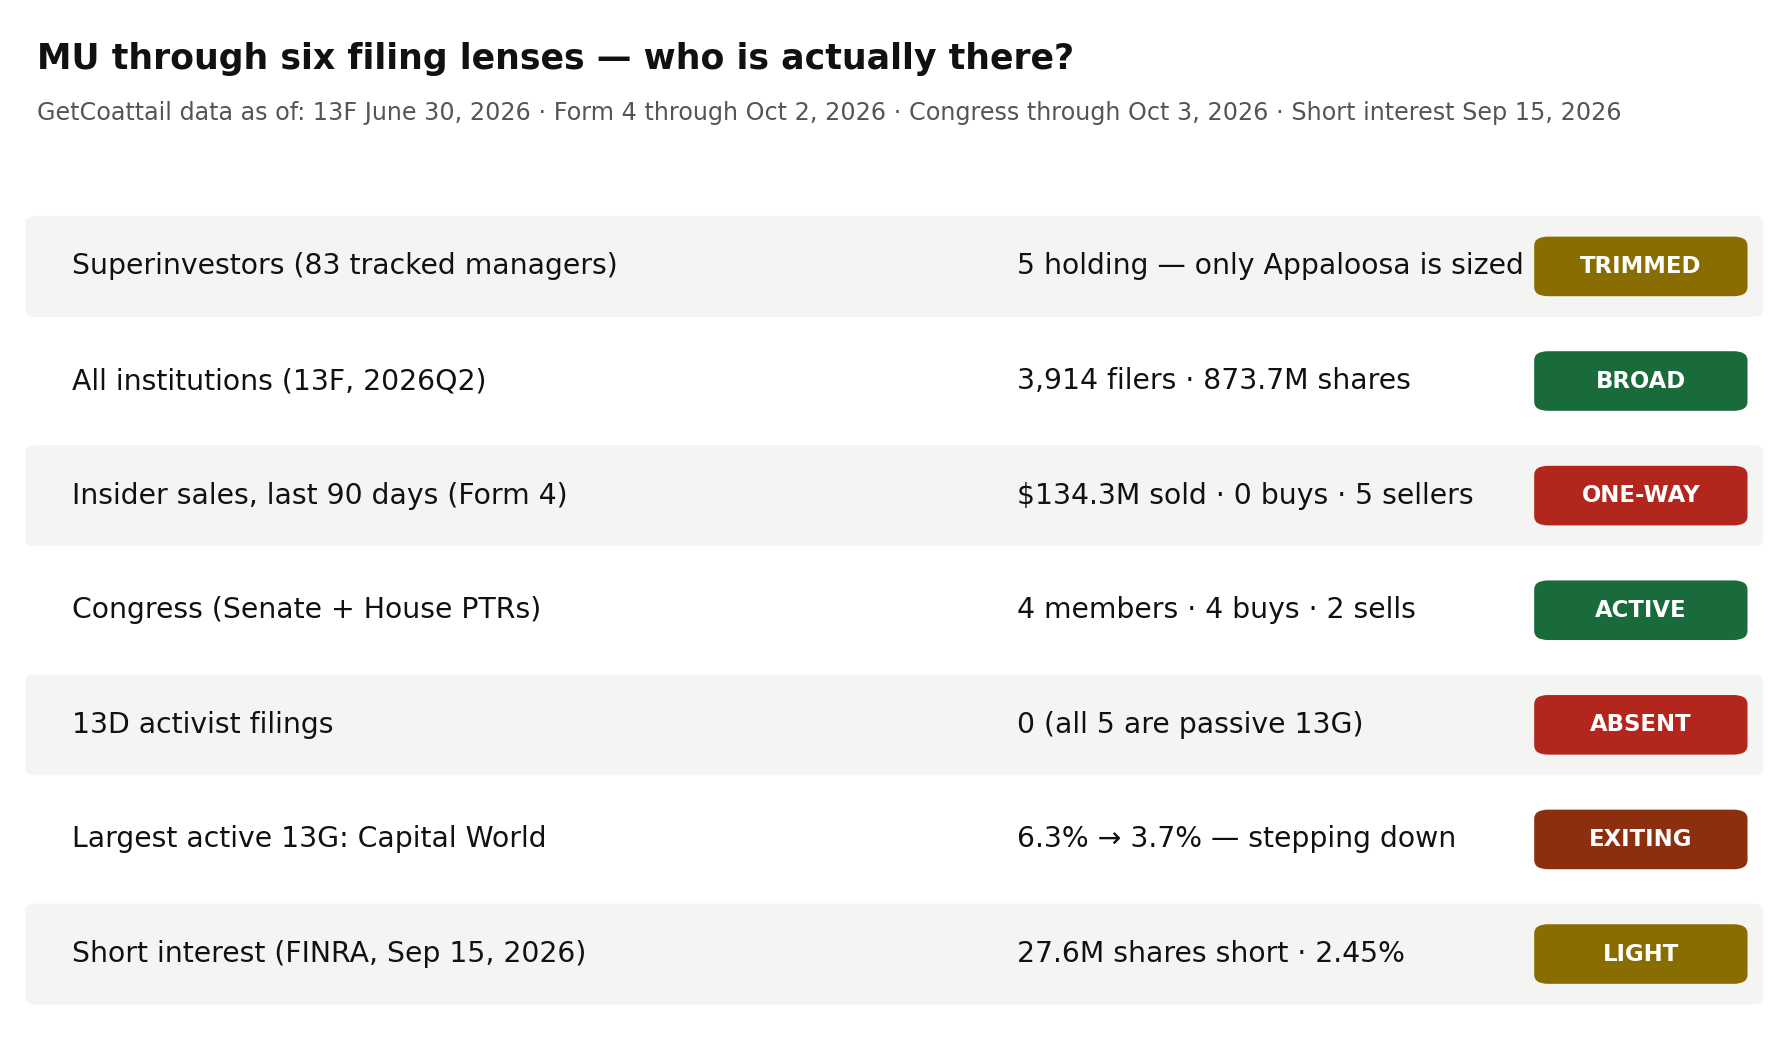
We track 83 large, mostly long-only managers whose 13F portfolios we collect directly from SEC EDGAR. As of June 30, 2026, five held Micron, up from three at March 31. Read the five closely and the headline count does most of the work. The only position of size belongs to Appaloosa Management: 975,000 shares worth $1,125,432,750 — 14.57% of Appaloosa's portfolio. The other four holders total 4,425 shares between them: Oakmark Funds with 180 shares (new), Maverick Capital with 1,673 shares (new, 0.02% of its portfolio), Mairs & Power with 410 shares, and Ruane Cunniff with 2,162 shares, unchanged. Combined, those four positions are worth $5,107,733 — about 0.45% of the Appaloosa position's reported value.
And the one position that matters shrank. Appaloosa held 1,665,000 Micron shares at March 31, 2026. At June 30 it held 975,000 — 41.4% fewer shares. Its reported value still doubled, from $562,503,600 to $1,125,432,750, because the share price went from a $337.84 close at the end of the first quarter to $1,154.29 at the end of the second in our price file. The filings do not say why a holder trims into a triple, and we do not guess. What they establish is the shape: in the quarter Micron became a consensus AI name, the superinvestor count rose from three to five while the cohort's share count, in its only material position, fell by two-fifths. For scale, 19 of the same 83 managers hold NVIDIA.
Lens 2: institutions — breadth, arriving fast, with heavy churn
Zoom out to the whole 13F market and the picture is unambiguous. At June 30, 2026, 3,914 institutions reported positions in Micron, up from 2,978 at March 31 — a 31.4% jump in one quarter — and 3,889 of them reported long positions. Reported share counts rose 18.81%, from 735,359,501 to 873,676,541 shares. The dataset's reported aggregate value rose 327.2%, from $295.61 billion to $1,263.0 billion; most of that increase is the share price itself, and the aggregate includes option rows, so we treat filer and share counts as the reliable series and the dollar figure as reported (see methodology).
The churn underneath is worth a sentence: 2,518 filers entered the register in the quarter and 1,582 left it. One plausible reading is that much of this breadth is mechanical — index baskets, ETF flows and benchmark rebalancing produce filer counts like this without any filer forming a view. The next lens shows who sits at the top of the register, and which way they have been moving.
Lens 3: the 5% register — passive, and the largest active name is stepping down
Five SC 13D/G filings cover Micron, and all five are 13G — the passive form. There is not one 13D, the filing an investor uses when it wants something from management. The largest reporter is Vanguard Capital Management at 7.47% (84,297,629 shares, as of March 31, 2026) — an index complex, filing passively. A separate Vanguard Group amendment reported 0 shares and 0.0% as of March 13, 2026; we record the filing without interpreting the internal reorganisation it appears to reflect.
The register's most informative line is Capital World Investors, the large active manager in Capital Group. It reported 6.3% (71,003,502 shares) at June 30, 2025, then 5.2% (58,472,522 shares) at December 31, 2025, then 3.7% (42,208,309 shares) at March 31, 2026 — two consecutive step-downs across three reports, the last below the 5% line, across exactly the period in which the stock multiplied. No activist has filed.
Lens 4: insiders — ninety days, $134 million sold, zero bought
In the 90 days through October 2, 2026, Micron insiders filed 11 reports covering 90 sale transactions totalling $134,325,384.10 — 135,904 shares sold by five insiders, 89 of the transactions by officers. Open-market purchases in the same window: zero.
Widen the window and the asymmetry persists, with one small exception. Over the full year through October 2, 2026, the record shows exactly three open-market purchase transactions — 23,200 shares worth $7,821,723.40, all by a single buyer, and none of them by an officer — against 338 sale transactions totalling $383,735,389.16 by twelve sellers. Across the entire parsed Form 4 record (134 filings), purchases remain those same three transactions, against 399 sales worth $435,587,204.06. Some selling is mechanical — vesting and tax withholding generate filings regardless of anyone's view — and we assign no motives. But the purchase side has no mechanical explanation: during a year in which the stock rose from a $181.60 closing low (October 10, 2025) to above $1,200, no Micron officer bought a single share at market price.
Lens 5: Congress — the lens that, for once, is lit
Across the Senate and House transaction record we maintain (as of October 3, 2026), four members of Congress have traded Micron: four purchases and two sales, with the most recent purchase on July 10, 2026, and buyers from both parties. The House accounts for three members (three buys, two sells); the Senate for one member (one buy, no sells, on June 25, 2026). Micron is the first name in this series where the political-money lens is not dark — both IREN and CoreWeave recorded zero congressional trades. The counts are small, and congressional disclosures report ranges rather than exact values, so we record direction only: on this lens, unusually, the filings lean the same way as the narrative.
Lens 6: short interest — the scepticism is not in the borrow
As of September 15, 2026 — the most recent FINRA settlement date — 27,633,780 Micron shares were sold short: 2.45% of the 1,129,393,151 shares the company most recently reported outstanding, with days-to-cover of 1.10. That is a different world from our first two audits — roughly 23% of the share count in IREN, roughly 10% in CoreWeave.
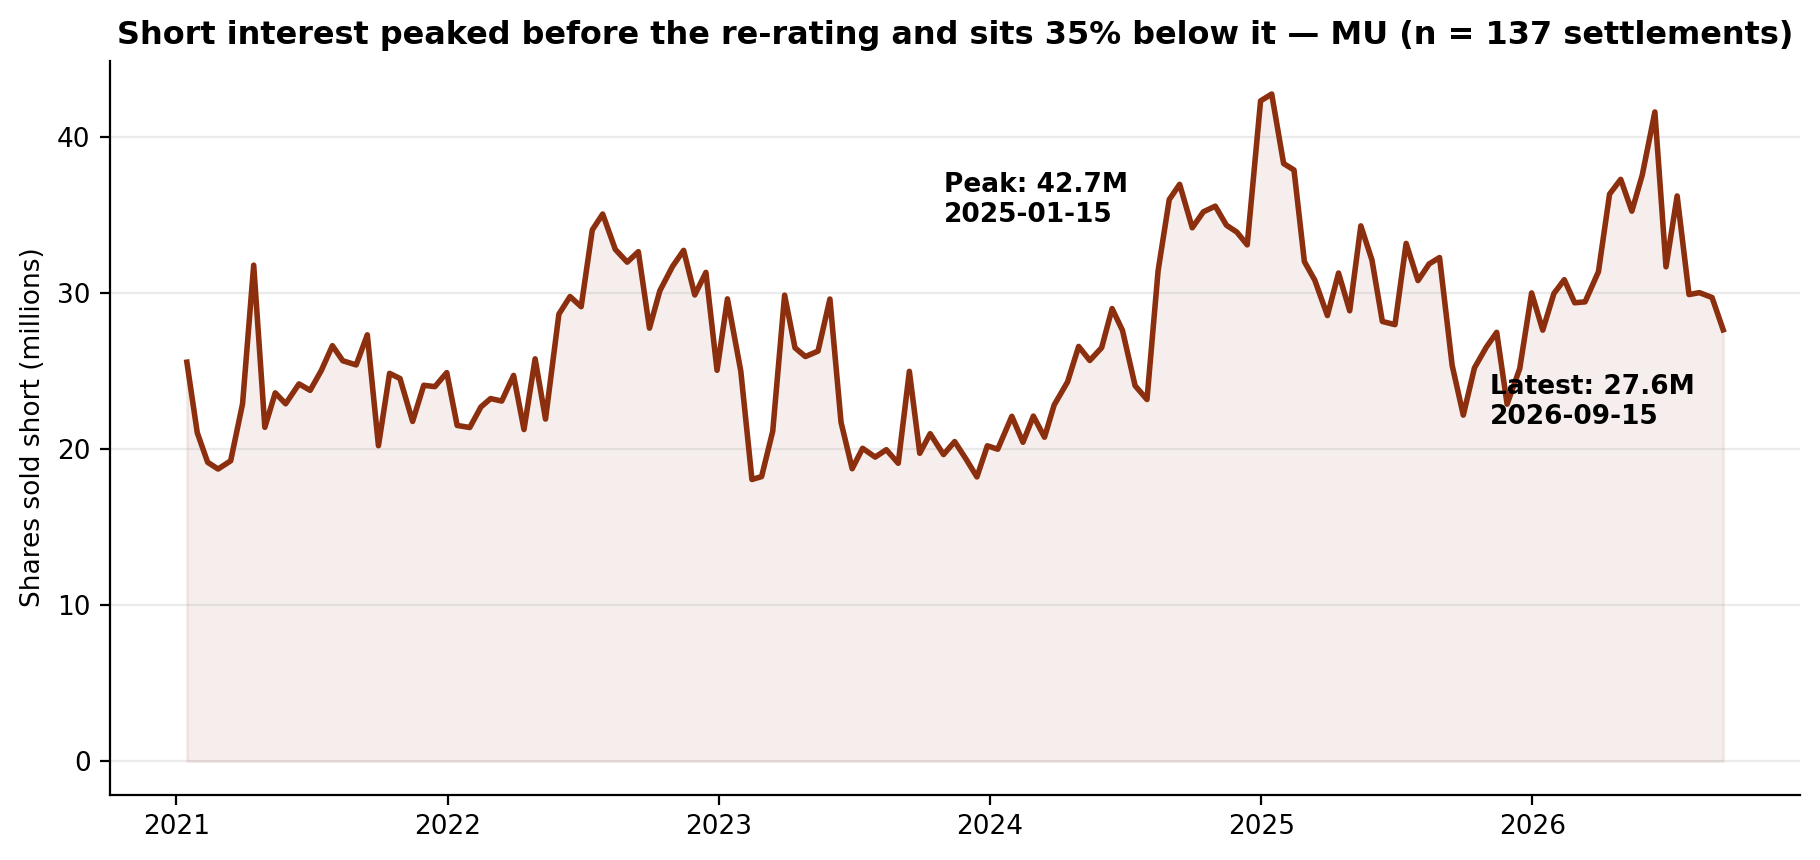
The series peaked at 42,739,272 shares on January 15, 2025 — before the AI-memory re-rating — and the latest reading sits 35.3% below that peak, though 9.0% above its year-ago level of 25,357,200 shares. Within 2026 it spiked to 41,592,382 shares at June 15, then dropped 23.86% in a single settlement to 31,669,690 at June 30. Memory stocks attract cyclical scepticism by habit; whatever that scepticism amounts to in commentary, it is not currently expressed as a large short position.
The gap, stated plainly
Line the narrative up against the tape and Micron is neither IREN nor CoreWeave. Institutional breadth (Lens 2) and Congress (Lens 5) genuinely support the story — the sponsorship is broad, and it arrived in one quarter. But the conviction cohorts point the other way on the specific measures this series exists to check: the only material superinvestor position was cut by 41.4% in shares during the stock's best quarter; the largest active 5% holder stepped down at successive reports; insiders sold $134.3 million in ninety days and officers have never, in the parsed record, bought. And the short side — the usual fingerprint of a crowded, doubted rally — is nearly empty at 2.45% of shares outstanding. The filings describe a stock the whole market now owns a little of, that its best-informed holders are trimming at the edges, and that almost nobody is betting against.
What would change the picture
Nothing above is a recommendation. It is a record. These are the filings that would change the description, in the order the data will arrive:
- 1. The 2026Q3 13Fs (filing window closing mid-November 2026). Whether Appaloosa rebuilds toward 1,665,000 shares, holds at 975,000, or exits ends the ambiguity of Lens 1. So does breadth: if the filer count stalls below 3,914 after a +31.4% quarter, Q2's sponsorship was flow, not sponsorship.
- 2. The first officer open-market purchase. A single Form 4 purchase code by an officer — at any size, at any price — would be the first in the parsed record. Watch also whether the sales pace — $134.3 million in the last 90 days — slows now that the fiscal year has closed.
- 3. Capital World's next 13G amendment, and any 13D. Two consecutive step-downs (6.3% → 5.2% → 3.7%) define the register's direction; a stabilisation or reversal changes that reading, and a first 13D from anyone converts the register from passive to intent.
- 4. Delivery against the $61.5 billion first-quarter guidance. The financing and share count behind the HBM capacity build show up in future 13F share counts and 13G percentages; the revenue print itself arrives with the December-quarter report.
- 5. The short-interest series from its June spike. Short interest fell 23.86% in the settlement after reaching 41,592,382 shares on June 15, 2026. Whether it rebuilds toward the January 2025 peak of 42,739,272 — or keeps drifting near 2.45% of shares outstanding — is the fastest-updating series in this audit: FINRA publishes it every two weeks.
Until one of those prints, the filing record describes the market's favourite memory stock as broadly owned, lightly shorted, bought by Congress — and trimmed, on the record, by the holders with the most information about it.
Related reading: Zero of 83: The Superinvestors Aren't in IREN — Filing Tape #1; One of 83: The Superinvestors Barely Own CoreWeave — Filing Tape #2; 80% Overlap, No Copycat Signal: Congress vs. the Superinvestors. Micron's own page: Micron (MU) on GetCoattail.
Methodology and data notes
- Superinvestor lens: 83 managers collected directly from SEC EDGAR Form 13F (managers_13f collection), positions as of June 30, 2026; Micron identified by CUSIP 595112103. First-quarter positions (Appaloosa 1,665,000 shares) are from the site pipeline's 2026Q1 holdings file, cross-checked by CUSIP; the 2026Q2 Appaloosa position matches exactly in both collections. The Appaloosa share change is −41.4% ((975,000 / 1,665,000) − 1).
- Full-market lens: SEC Form 13F Data Sets full-market aggregation (the fixtures underlying our 2026Q1–Q2 market tables). Holders = distinct filers reporting the CUSIP; 3,889 of the 3,914 reported long positions. Reported-value caution: the aggregate value ($1,262,987,070,303 over 873,676,541 shares) implies ≈$1,445.60 per share against a June 30, 2026 close of $1,154.29 in our price file. The gap is definitional, not a filer error: the aggregate sums the VALUE of every information-table row — including put and call option rows — while the share count covers long common-stock rows only. We therefore headline filer and share counts and label dollar values "reported."
- Insider lens: full-parse Form 4 aggregation (agg_by_ticker), record as of October 2, 2026 (134 filings). Sale and purchase counts are transaction-code counts (S and P) in non-derivative rows; grants and exercises are not counted as purchases. The site's 90-day insider aggregate, compiled on a different as-of date (October 8, 2026), shows the same shape (0 buys; 72 sales; $90,967,911.02; four sellers).
- 13D/G lens: full-parse SC 13D/G aggregation and parsed filings (5 filings, 3 of them amendments, 3 reporters in aggregate), filings through May 14, 2026. Reporter percentages are as reported in each filing for its event date; the same holder can appear in several filings.
- Congress lens: Senate PTR archive and House PTR archive as maintained on this site, combined record as of October 3, 2026. Counts are transaction counts in the aggregated member record; congressional disclosures report value ranges, so no dollar figures are used for this lens.
- Short interest lens: FINRA Equity Short Interest files (biweekly settlement dates), collected directly from FINRA's public distribution; the MU series covers 137 settlements from January 15, 2021 to September 15, 2026 — MU appears in every settlement file in the collection. FINRA publishes each settlement about two weeks after the fact. The share-count ratio uses the company's dei reported shares outstanding — 1,129,393,151 shares as of June 17, 2026.
- Fundamentals note: our fundamentals collection carries Micron's fiscal-2025 figures — revenue $37,378,000,000, net income $8,539,000,000, assets $82,798,000,000 — because it was compiled before the fiscal-2026 annual figures were ingested. The fiscal-2026 figures in the introduction are from the company's September 30, 2026 results as reported by multiple outlets (see market context sources), not from our fundamentals file.
- Prices: our own daily-close file for MU through October 2, 2026 ($1,074.89 close, +276.6% year to date on that file; 252-session closing high $1,213.56 on June 25, 2026; closing low $181.60 on October 10, 2025; closes of $337.84 at March 31, 2026 and $1,154.29 at June 30, 2026). The October 5, 2026 close of $1,063.96 and +272.78% year-to-date figure are quote-provider figures (Yahoo Finance, as reported by Watcher.Guru and BitNewsBot, checked October 8, 2026) and differ from our file because of the as-of date.
- Market context sources: fiscal-2026 results and first-quarter fiscal-2027 guidance (September 30, 2026) — company results as reported by ad-hoc-news, Watcher.Guru, EquitySwarm and The Motley Fool; consensus target ($1,375.58; 40 Buy, five Hold, October 1, 2026) — MarketBeat via ad-hoc-news; HBM supply agreements — company earnings commentary as reported by Watcher.Guru; DRAM search breakout and Micron's centrality to it — RisingTrends, Top 50 Investing Trends (October 2026), checked October 8, 2026. Figures we could not confirm against two sources were left out.
- Data files: MU lens summary — every figure in this audit by lens and as-of date (CSV) · MU short interest at all 137 FINRA biweekly settlements, Jan 15, 2021 – Sep 15, 2026 (CSV).
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history
- v1.0 — October 8, 2026: first publication.