GetCoattail Research — NVIDIA is the AI trade itself: a $150 billion buyback increase, a record closing high, and an index weight larger than Japan's entire market. We ran it through every filing lens we maintain. For the first time in this series, the smart money is visibly there — and the disagreements are in who is quietly reducing, and the one cohort that has never bought at all.
Start with the narrative. NVIDIA, maker of the GPUs the AI build-out runs on, closed at a record high in the first week of October 2026, with a market value of about $5.77 trillion at the October 6 price of $239.24 in our fundamentals file. On September 28, 2026, its board authorized a $150 billion increase to the share repurchase program, lifting the remaining total to $235 billion — reported as the largest buyback authorization increase in history. NVIDIA now accounts for 5.21% of the MSCI All Country World Index — more than Japan's 5.16% — and Wedbush's Dan Ives rates it outperform with a $300 target. On Reddit's investing boards it was the third most-mentioned ticker on October 7. Fiscal 2026 revenue — the year ended January 2026 — was $215.94 billion, with net income of $120.07 billion.
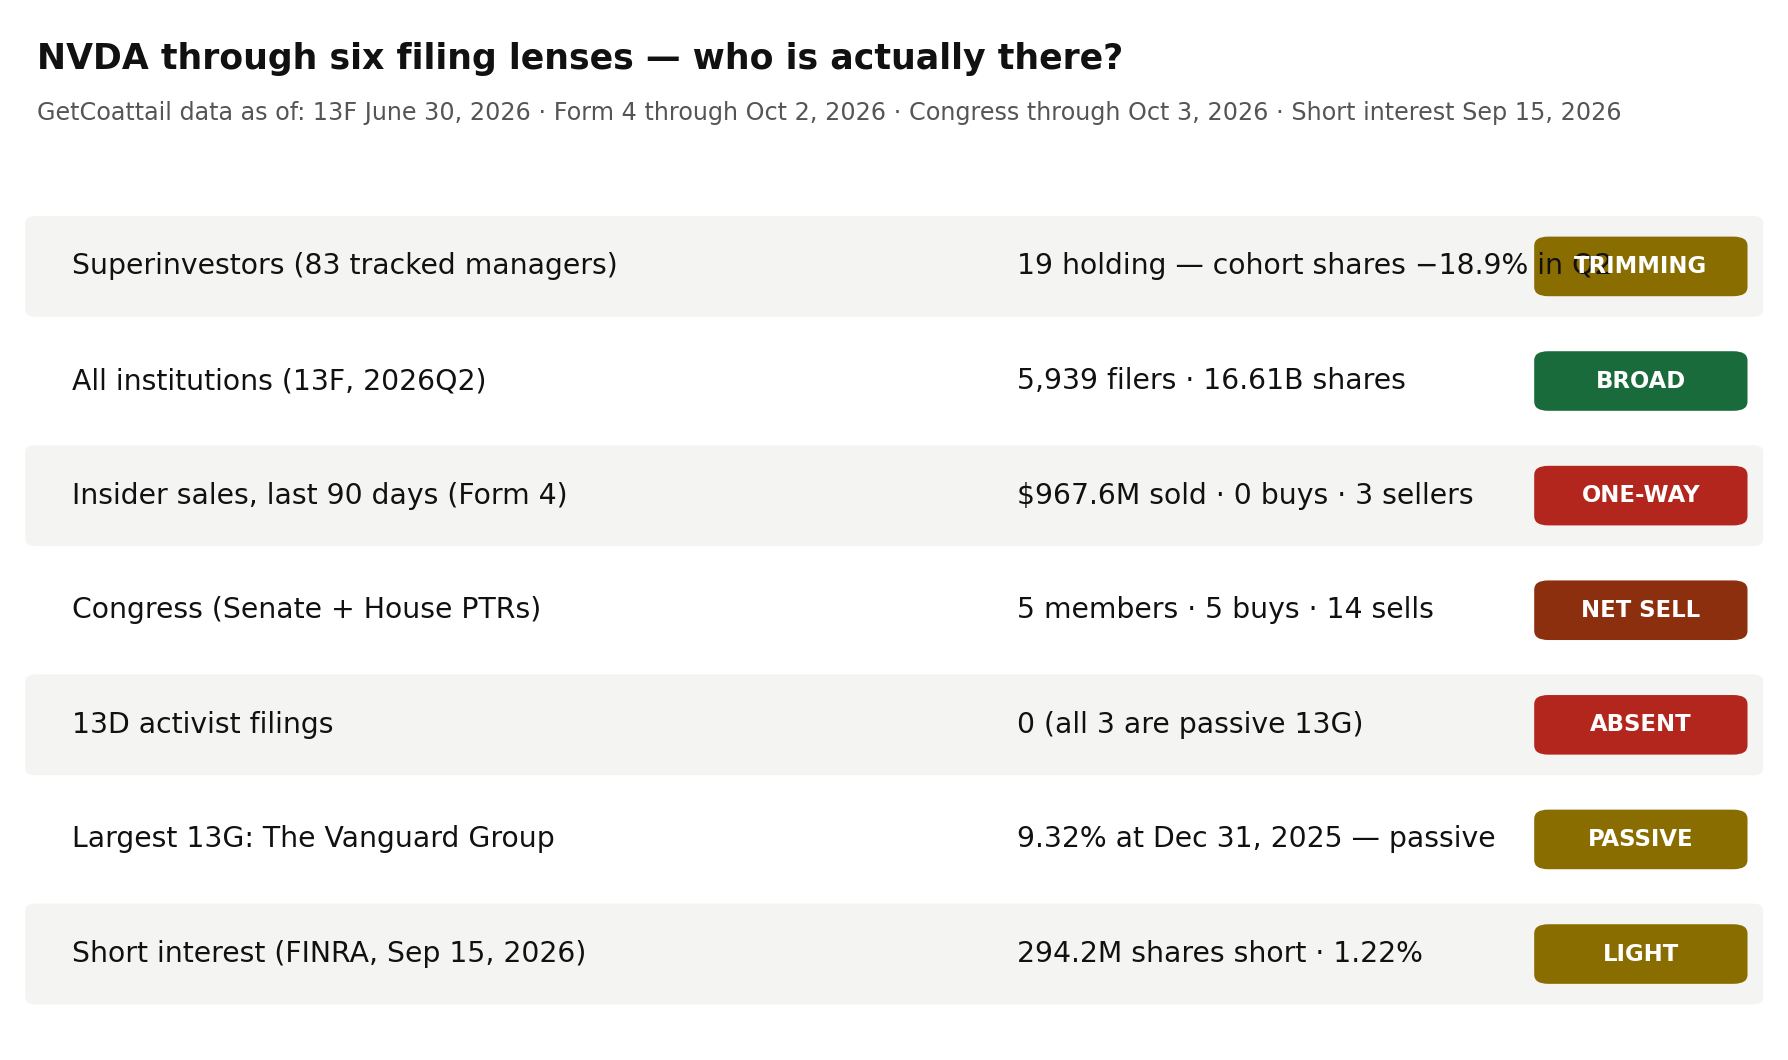
Now the filings. GetCoattail tracks the portfolios, trades and disclosures of the investors with the most information about any given company: concentrated superinvestors, institutions as a whole, corporate insiders, members of Congress, and 5% holders. For NVIDIA — the fourth Filing Tape audit, after IREN, CoreWeave and Micron — the first lens finally lights up. The rest of the tape is more complicated.
Lens 1: the superinvestors — nineteen names, reducing on balance
We track 83 large, mostly long-only managers whose 13F portfolios we collect directly from SEC EDGAR. As of June 30, 2026, nineteen held NVIDIA — the most of any name in this series (twenty reported rows; one manager reports common stock and a put separately). The cohort owns it in size: Tiger Global holds 11,198,773 shares worth $2,240,762,490 (9.34% of its portfolio), H&H International holds 6,280,675 shares worth $1,256,700,261 (6.58%), and Mairs & Power, Polen Capital, Egerton Capital and Maverick Capital each hold positions worth between roughly $612 million and $942 million.
Read the direction column, though, and the quarter was a trimming quarter. Of the nineteen long positions, eleven were decreased, four increased, three were unchanged and one was new. In aggregate, on the pipeline basis we use to compare quarters consistently, the cohort held 44,756,174 NVIDIA shares at March 31, 2026 and 36,293,621 at June 30 — 18.9% fewer shares — in a quarter when the share price rose 14.7%, from a $174.40 close to $200.09 in our price file. The largest single move was H&H International, the cohort's biggest NVIDIA holder at March 31 with 13,843,775 shares: it reported 6,280,675 at June 30, a cut of 54.6%. Tiger Global trimmed 6.8% and became the largest holder. The increases were smaller: Egerton added 27.8%, Appaloosa added 3.6% to 1,525,000 shares, and Davis Advisors added 36.3% to a 154,727-share position. The filings do not say why holders trim into strength, and we do not guess. The balance: the superinvestors are in NVIDIA, and in the second quarter they collectively owned less of it.
Lens 2: institutions — already everywhere
Zoom out to the whole 13F market and NVIDIA is simply ubiquitous. At June 30, 2026, 5,939 institutions reported positions, up from 5,742 at March 31 — a 3.4% increase, the slowest breadth growth in this series, in a register that added 1,845 filers and lost 1,648 in the quarter. Reported share counts rose 20.43%, from 13,794,758,461 to 16,613,221,322 shares, and 5,909 filers reported long positions. The dataset's reported aggregate value rose 37.6% to $3,373,216,090,722; the aggregate includes option rows, so we treat filer and share counts as the reliable series and the dollar figure as reported (see methodology). One plausible reading of the modest filer growth is saturation: a stock already held by nearly six thousand institutions has few left to arrive. Note the contrast inside the quarter: existing holders, in aggregate, reported more shares, while the tracked cohort cut its count 18.9%.
Lens 3: the 5% register — passive, as expected
Three SC 13D/G filings cover NVIDIA, and all three are 13G — the passive form. There is not one 13D, the filing an investor uses when it wants something from management. The largest reporter is The Vanguard Group at 9.32% (2,266,625,855 shares, as of December 31, 2025, in an amendment filed January 30, 2026). Vanguard Capital Management reported 7.31% (1,777,408,252 shares, as of March 31, 2026) in the most recent filing, on April 28, 2026. For a company of NVIDIA's size, a quiet, index-dominated register is the expected shape. No activist has filed.
Lens 4: insiders — $968 million sold in ninety days, zero bought, ever
In the 90 days through October 2, 2026, NVIDIA insiders filed 16 reports covering 25 sale transactions totalling $967,599,313.46 — 4,332,118 shares sold by three insiders. Open-market purchases in the same window: zero.
Widen the window and the zero does not move. Over the full year through October 2, 2026, the record shows 300 sale transactions totalling $2,123,341,834.60 by twelve sellers — and zero open-market purchases. Across the entire parsed Form 4 record — 178 filings, 715 sale transactions, $3,797,459,610.89 sold by sixteen sellers, 607 of the sales by officers — there is not one open-market purchase by any insider, officer or otherwise, at any price. Our site's separate 90-day insider aggregate, compiled on a different as-of date, matches the full-parse figure exactly: zero buys, 25 sales, $967,599,313.46, three sellers. Some insider selling is mechanical — vesting and tax withholding generate filings regardless of anyone's view — and we assign no motives. But the purchase side has no mechanical explanation: through a multi-year run that carried the stock from a $165.17 closing low on March 30, 2026 to a $235.74 closing high on May 14, 2026, nobody inside NVIDIA has paid market price for a share in the parsed record.
Lens 5: Congress — buying Micron, selling NVIDIA
Across the Senate and House transaction record we maintain (as of October 3, 2026), five members of Congress have traded NVIDIA: five purchases and fourteen sales, with the most recent purchase on August 18, 2026, and both parties represented. The House accounts for all five purchases and eight of the sales; the Senate record shows six sales and no purchases. The direction is the reverse of our previous audit: Micron recorded four congressional buys against two sells, while NVIDIA — the larger, more celebrated name — records sells at nearly three times the buy count. Congressional disclosures report ranges rather than exact amounts, and the counts are small; direction is all this lens claims, and here it points against the narrative.
Lens 6: short interest — large in shares, small in everything else
As of September 15, 2026 — the most recent FINRA settlement date — 294,225,803 NVIDIA shares were sold short, with days-to-cover of 2.55. Against the 24,100,000,000 shares the company most recently reported outstanding, that is 1.22% — a smaller share of the company than in any previous audit in this series (Micron 2.45%, CoreWeave roughly 10%, IREN roughly 23%).
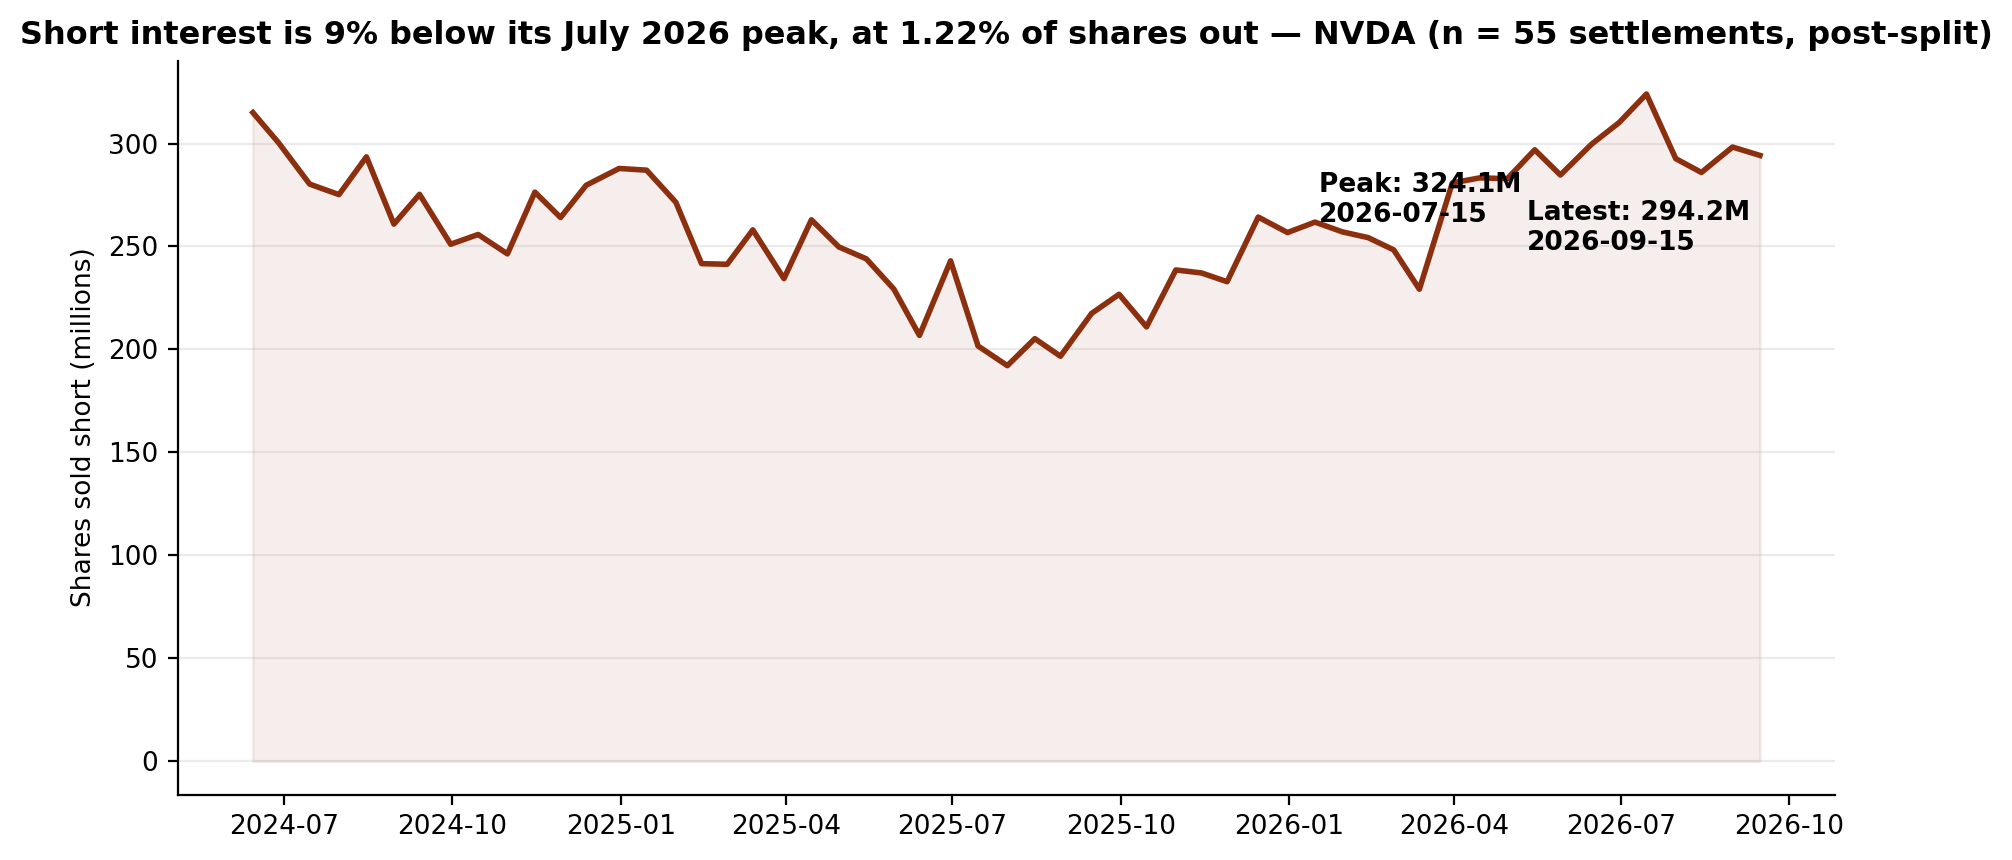
The level is up 35.3% from a year ago (217,485,473 shares at September 15, 2025) and sits 9.2% below the post-split peak of 324,052,767 shares on July 15, 2026. It is also below the 315,033,985 shares reported at the first post-split settlement on June 14, 2024: in share terms, the short position is roughly where it stood two years — and a near-doubling of the share price — ago. Whatever scepticism exists about NVIDIA's valuation, it is not expressed as a large borrow.
The gap, stated plainly
NVIDIA is the mirror image of this series' first audit. IREN had breadth without a single tracked superinvestor; NVIDIA has nineteen of them, 5,939 reporting institutions, and a passive register headed by a 9.32% index holder. The sponsorship the earlier names lacked is here, in full. What is missing is the same thing that was missing there, in the cohorts closest to the company: insiders have never, in the parsed record, bought a share on the open market, and sold $967.6 million worth in the last ninety days; the tracked superinvestors, while heavily invested, cut their aggregate share count 18.9% in the stock's rising second quarter, led by the largest holder cutting by more than half; and members of Congress, on the record, filed nearly three sale transactions for every purchase. The filings describe the market's most-owned stock as one the whole world holds, the best-informed holders are trimming at the margin, and the people inside the building have only ever sold.
What would change the picture
Nothing above is a recommendation. It is a record. These are the filings that would change the description, in the order the data will arrive:
- 1. The first insider open-market purchase, ever. A single Form 4 purchase code — at any size, at any price — would be the first in the parsed record of 178 filings. Watch also whether the sales pace — $967.6 million in the last 90 days, by three sellers — broadens or slows.
- 2. The 2026Q3 13Fs (filing window closing mid-November 2026). Whether the tracked cohort's share count stabilises after an 18.9% cut — and whether H&H holds at 6,280,675 shares, rebuilds, or exits — is the cleanest test of whether the second-quarter trimming was rebalancing or the start of a reduction.
- 3. Congress into year-end. Five buys against fourteen sells is a small sample; the fourth-quarter PTRs will show whether the political-money lens keeps leaning against the stock or reverses, as it pointed the other way on Micron.
- 4. Any 13D, and Vanguard's next 13G amendment. The register is passive at 9.32% and 7.31% for the two Vanguard reporters; a first activist filing, from anyone, would be a change of kind, not degree.
- 5. The short-interest series from its July peak. Short interest has fallen 9.2% from 324,052,767 shares (July 15, 2026). Whether it rebuilds through that peak into the next earnings cycle — or keeps drifting near 1.22% of shares outstanding — is the fastest-updating series in this audit: FINRA publishes it every two weeks.
Until one of those prints, the filing record describes the defining stock of the AI era as broadly owned, lightly shorted, trimmed by its largest tracked holders — and never once bought, on the open market, by the people who run it.
Related reading: Five of 83: Micron's Superinvestor Count Rose. Its Biggest Holder Cut Shares 41%. — Filing Tape #3; Zero of 83: The Superinvestors Aren't in IREN — Filing Tape #1; 80% Overlap, No Copycat Signal: Congress vs. the Superinvestors. NVIDIA's own page: NVIDIA (NVDA) on GetCoattail.
Methodology and data notes
- Superinvestor lens: 83 managers collected directly from SEC EDGAR Form 13F (managers_13f collection), positions as of June 30, 2026; NVIDIA identified by CUSIP 67066G104. Nineteen distinct managers hold it, in twenty rows (one manager reports common stock and a put row). Quarter-to-quarter cohort share totals (44,756,174 at March 31; 36,293,621 at June 30) are from the site pipeline's holdings files on the same CUSIP basis in both quarters; the pipeline's second-quarter total differs from the EDGAR collection's long-row total (36,294,621) by 1,000 shares, one manager's smallest row, which the pipeline does not carry. The H&H and Tiger Global share changes match the EDGAR collection's reported change percentages (−54.6% and −6.8%).
- Full-market lens: SEC Form 13F Data Sets full-market aggregation (the fixtures underlying our 2026Q1–Q2 market tables). Holders = distinct filers reporting the CUSIP; 5,909 of the 5,939 reported long positions. Reported-value caution: the aggregate value ($3,373,216,090,722 over 16,613,221,322 shares) implies ≈$203.04 per share against a June 30, 2026 close of $200.09 in our price file. The gap is definitional, not a filer error: the aggregate sums the VALUE of every information-table row — including put and call option rows — while the share count covers long common-stock rows only. We therefore headline filer and share counts and label dollar values "reported."
- Insider lens: full-parse Form 4 aggregation (agg_by_ticker), record as of October 2, 2026 (178 filings). Sale and purchase counts are transaction-code counts (S and P) in non-derivative rows; grants and exercises are not counted as purchases. The site's 90-day insider aggregate, compiled on a different as-of date (October 8, 2026), matches the full-parse 90-day figures exactly (0 buys; 25 sales; $967,599,313.46; three sellers).
- 13D/G lens: full-parse SC 13D/G aggregation and parsed filings (3 filings, 2 of them amendments, 2 reporters in aggregate), filings through April 28, 2026. Reporter percentages are as reported in each filing for its event date; the same holder can appear in several filings.
- Congress lens: Senate PTR archive and House PTR archive as maintained on this site, combined record as of October 3, 2026 (Senate component as of October 1, 2026). Counts are transaction counts in the aggregated member record; congressional disclosures report value ranges, so no dollar figures are used for this lens. The Senate aggregate records six sales and no purchases; its member-count field is not used here.
- Short interest lens: FINRA Equity Short Interest files (biweekly settlement dates), collected directly from FINRA's public distribution; NVIDIA appears in all 137 settlement files from January 15, 2021 to September 15, 2026. FINRA figures are as reported at the time and are not split-adjusted: the series jumps at the July 2021 (4-for-1) and June 2024 (10-for-1) split settlements, so all comparisons in this audit use the post-split window (55 settlements, June 14, 2024 – September 15, 2026). FINRA publishes each settlement about two weeks after the fact. The share-count ratio uses the company's dei reported shares outstanding — 24,100,000,000 shares as of August 21, 2026.
- Fundamentals note: our fundamentals collection carries NVIDIA's fiscal-2026 figures — revenue $215,938,000,000, net income $120,067,000,000, assets $206,803,000,000 — for the fiscal year ended January 2026. The market value of about $5.77 trillion uses that file's October 6, 2026 price ($239.24) and reported share count.
- Prices: our own daily-close file for NVDA through October 2, 2026 ($233.95 close, +25.4% year to date on that file; 252-session closing high $235.74 on May 14, 2026; closing low $165.17 on March 30, 2026; closes of $174.40 at March 31, 2026 and $200.09 at June 30, 2026).
- Market context sources: repurchase authorization increase ($150 billion, September 28, 2026; remaining total $235 billion) — company announcement as reported by Investorideas; index weight (5.21% of MSCI ACWI) and record closing high — StockTwits news and Barron's, checked October 8, 2026; analyst target ($300, Wedbush) — Asianet Newsable, October 8, 2026; social mention counts — AltIndex Reddit and StockTwits aggregations, October 7, 2026. Figures we could not confirm against two sources were left out.
- Data files: NVDA lens summary — every figure in this audit by lens and as-of date (CSV) · NVDA short interest at all 137 FINRA biweekly settlements, Jan 15, 2021 – Sep 15, 2026 (CSV).
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history
- v1.0 — October 8, 2026: first publication.