GetCoattail Research — The Filing Tape #159. Union Pacific reports third-quarter 2026 results before the open on October 22, 2026 — one of the day's earnings-focus names. The June filings show 19 tracked holders, a verified continuing cohort up 6.4% with one large new position, and an insider record with no purchase in it and no sale at all in the last 90 days.
The Hype
The attention is an earnings morning. Union Pacific is on the October 22 earnings-focus list, reporting before the open. WEEX TradFi Daily, October 22, 2026 Zacks puts the third-quarter consensus at $3.47 a share, up 12.7% from a year ago, on revenue of $7.12 billion, up 13.97%. Zacks, October 20, 2026 A TickerOn preview frames the questions as freight volumes, the operating ratio, and any update on the company's proposed Norfolk Southern combination. TickerOn, October 2026 Our price file, which ends October 2, shows a stock that already ran into this print: up 12.1% in Q2 ($242.62 on March 31 to $272.00 on June 30), then $278.28 at October 2 — still 10.4% below the 252-day high close of $310.62 on August 26, 2026, and up 20.3% for the year on the file's closes.
The Tape
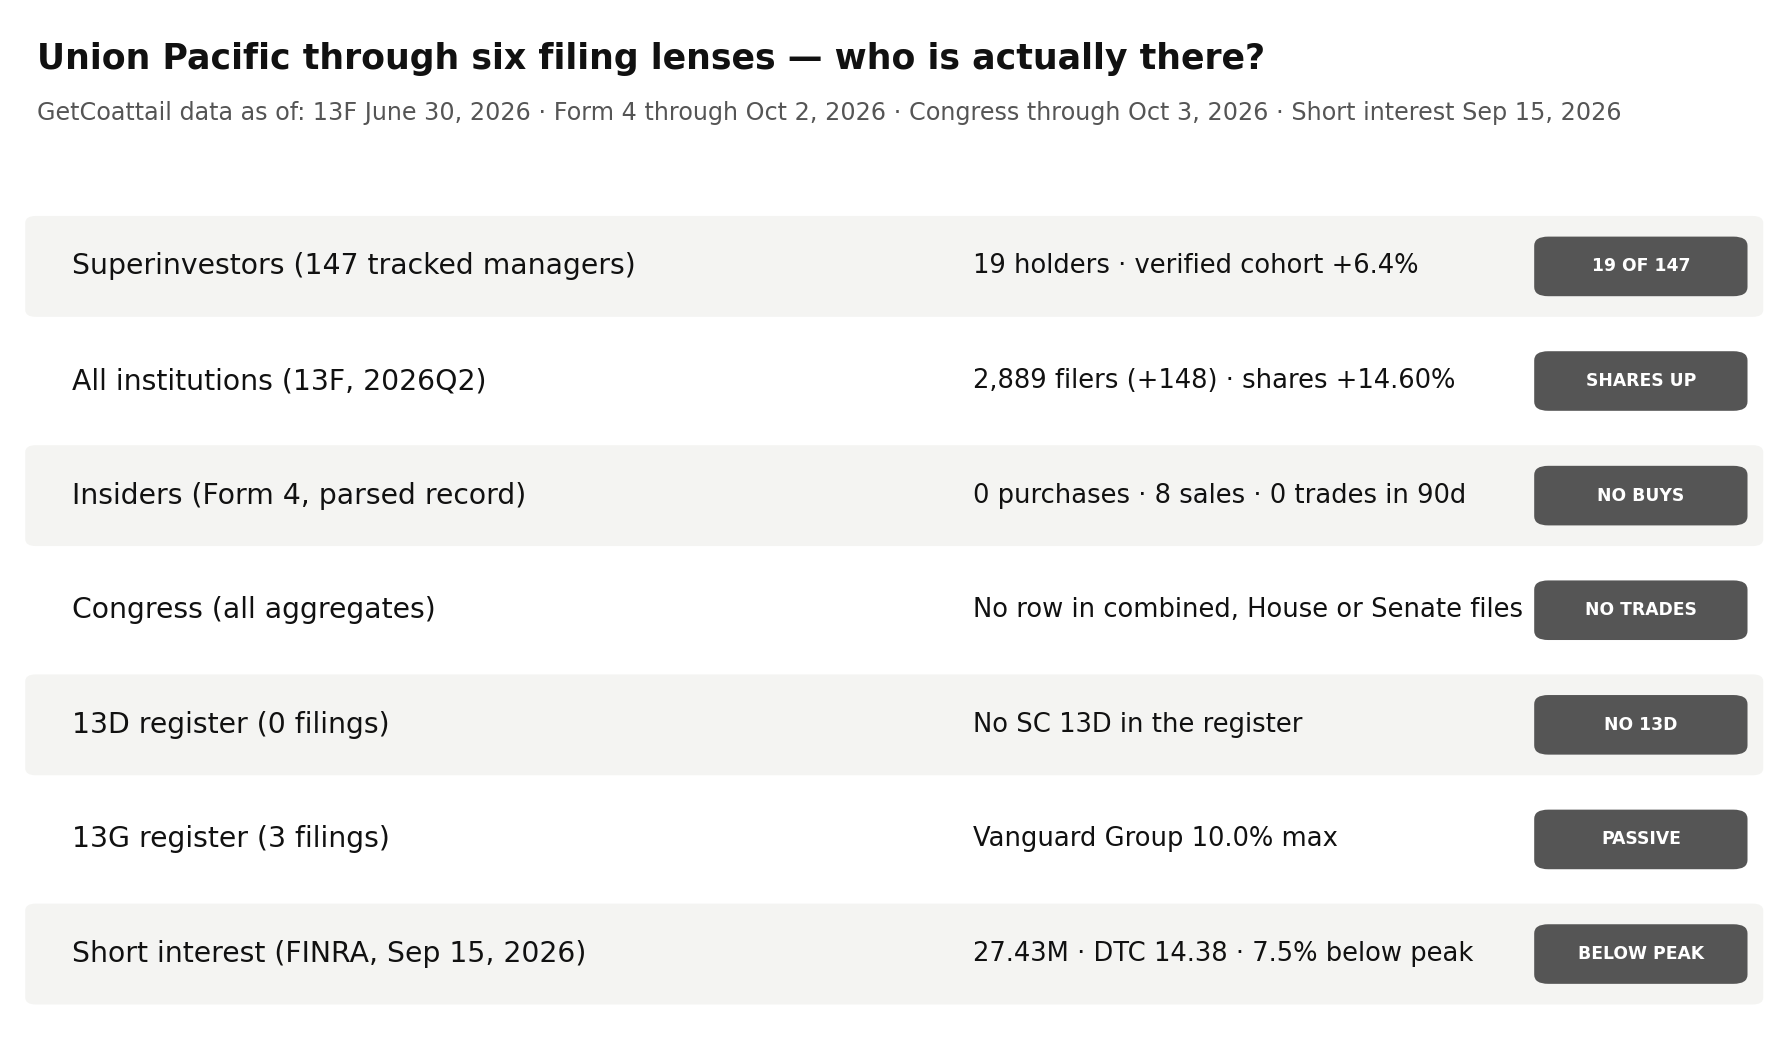
For Union Pacific, the one hundred and fifty-ninth Filing Tape audit, the tape shows 19 tracked managers — the verified continuing cohort up 6.4%, with one large new position and heavy rotation underneath — a full market that added 66,956,912 shares, an insider record with no purchase and a silent last 90 days, no congressional trades at all, a 5% register topped by a 10.0% passive print, and a borrow of 4.62% that is up 89.3% in a year.
| Lens | As of | What the filings show | Direction vs prior period |
|---|---|---|---|
| Superinvestors (13F) | Jun 30, 2026 | 19 holders of 147 tracked managers hold 12,128,043 shares; 1 NEW label (Viking) | Verified continuing holders +6.4% (9,477,395 → 10,080,711 shares); register total +28.0% |
| All institutions (13F) | Jun 30, 2026 | 2,889 filers; 525,565,208 shares; reported value $140,624,147,576 | Filers +148; shares +14.60%; reported value +29.32% |
| Insiders (Form 4) | Oct 2, 2026 | Last 90 days (by filing date): 0 purchases, 0 sales; parsed record: 0 purchases, 8 sales | No purchase in the parsed record: 0 across 229 filings |
| Congress | Oct 3, 2026 | No row in the combined, House or Senate aggregates; no member-file rows | No recorded trades in any congressional file |
| 13D/G | Apr 30, 2026 | 3 parsed filings, all SC 13G family (0 SC 13D); register maximum 10.0% | Latest filing, Apr 30, 2026, prints Vanguard Capital Management at 7.55% as of Mar 31, 2026 |
| Short interest (FINRA) | Sep 15, 2026 | 27,430,602 shares; 14.38 days to cover; 4.62% of the share count | Down 7.5% from the May 29, 2026 series maximum; up 89.3% from a year ago |
Lens 1 — the superinvestors: 19 holders, adding on balance, rotating hard. The collection holds 147 managers (144 at June 30; 3 early filers at September 30). The June 30, 2026 common-stock register is 19 distinct managers holding 12,128,043 shares worth $3,298,827,094, long only, with no option rows. Bill Nygren – Oakmark Funds holds 3,844,522 shares, 31.7% of the cohort, at a 1.39% weight, labelled INCREASED at +1.6%; Slate Path Capital holds 2,302,604 shares, 19.0%, at an 8.67% weight, labelled INCREASED at +214.2% — the top two together are 50.7% of the cohort. The direction across all 19 is 9 decreased, 6 increased, 3 unchanged and 1 NEW: Viking Global Investors, 2,047,332 shares at a 1.59% weight, whose March filing contains no position in this name, so the label is a genuine first position (methodology). Every continuing label verifies under accession identity plus CUSIP-overlap pairing: the 18 continuing holders held 9,477,395 shares at March 31 and 10,080,711 at June 30, a verified change of +6.4% — an aggregate that hides the rotation inside it, from Third Point at +250.0% and Slate Path at +214.2% to EdgePoint at −40.4% and W.H. Reaves at −74.6%. None of the three September early filers holds the name. One tracked name exited: Mondrian Investment Partners, 455 shares at March 31, gone by June. Every holder's implied price is exactly $272.00, the June 30 close, and at 2.31% of reported institutional shares the cohort is a sample, not the register. 13F figures are as of June 30, 2026, published up to 45 days later.
Lens 2 — institutions: 148 more filers, 67.0 million more shares. At June 30, 2026, 2,889 institutions reported positions on the name's single common-stock CUSIP, up 148 from 2,741 at March 31 (+5.40%); 2,878 are long. Reported shares rose 14.60% to 525,565,208 (+66,956,912 shares), while reported value rose 29.32% to $140,624,147,576, labelled "reported" because the aggregate includes option rows (methodology). Flow counts agree (2,001 entered, 1,853 exited, net +148), and the single-CUSIP aggregate matches the by-ticker total on every field. The aggregate implies $267.57 against the $272.00 close (−1.63%). The quarter's price gain was 12.1%, so part of the reported-value rise is the price itself; the share count, which no price move can inflate, rose 14.60% on its own. The tracked cohort's verified +6.4% is the same direction, at less than half the market's pace in share terms.
Lens 3 — insiders: no purchase, eight sales, and a silent quarter. The parsed Form 4 record holds 229 filings, from January 3, 2025 through October 1, 2026, inside windows that run through October 2, 2026. The last 90 days (a filing-date window, per the aggregate's own definition) hold 26 filings and no open-market purchase and no sale at all. The last year holds no purchase either, against 5 sale-coded rows across 34,377 shares worth $9,251,220.55, by 3 sellers, all 5 of them officer rows. The full parsed record holds no purchase at all: 0 purchase rows, against 8 sale-coded rows across 48,372 shares worth $12,762,960.55, all 8 of them officer rows, by 5 sellers — 3 sale rows, in 109 filings dated before October 3, 2025, sit outside the last year's window. The claim is bounded by the record's span: within this record, which begins in January 2025, the purchase column is blank, and the most recent window is blank on both sides.
Lens 4 — Congress: no recorded trades. This lens is empty, and the audit says so rather than skipping it. The combined aggregate (as of October 3, 2026), the House aggregate (as of October 3, 2026) and the Senate aggregate (as of October 1, 2026) each carry no row for this ticker, and the House member file (as of October 3, 2026; 2026 House PTR filings, transactions dated on or after April 1, 2026) lists no member with a position in it. There is nothing to total.
Lens 5 — the 5% register: a 10.0% passive maximum, no activist filing. Our full parse holds 3 SC 13D/G filings, all in the SC 13G family (1 SC 13G and 2 SC 13G/A amendments); there is no SC 13D. The 3 filings carry 3 reporter rows from 2 reporters. The register maximum is The Vanguard Group, 59,326,968 shares and 10.0%, as of December 31, 2025, filed January 7, 2026. The same reporter later prints 0 shares and 0.0% as of March 13, 2026, filed March 27, 2026. The latest filing is Vanguard Capital Management, 44,823,799 shares and 7.55%, as of March 31, 2026, filed April 30, 2026. The prints are reported as printed, without attributing a reason (methodology).
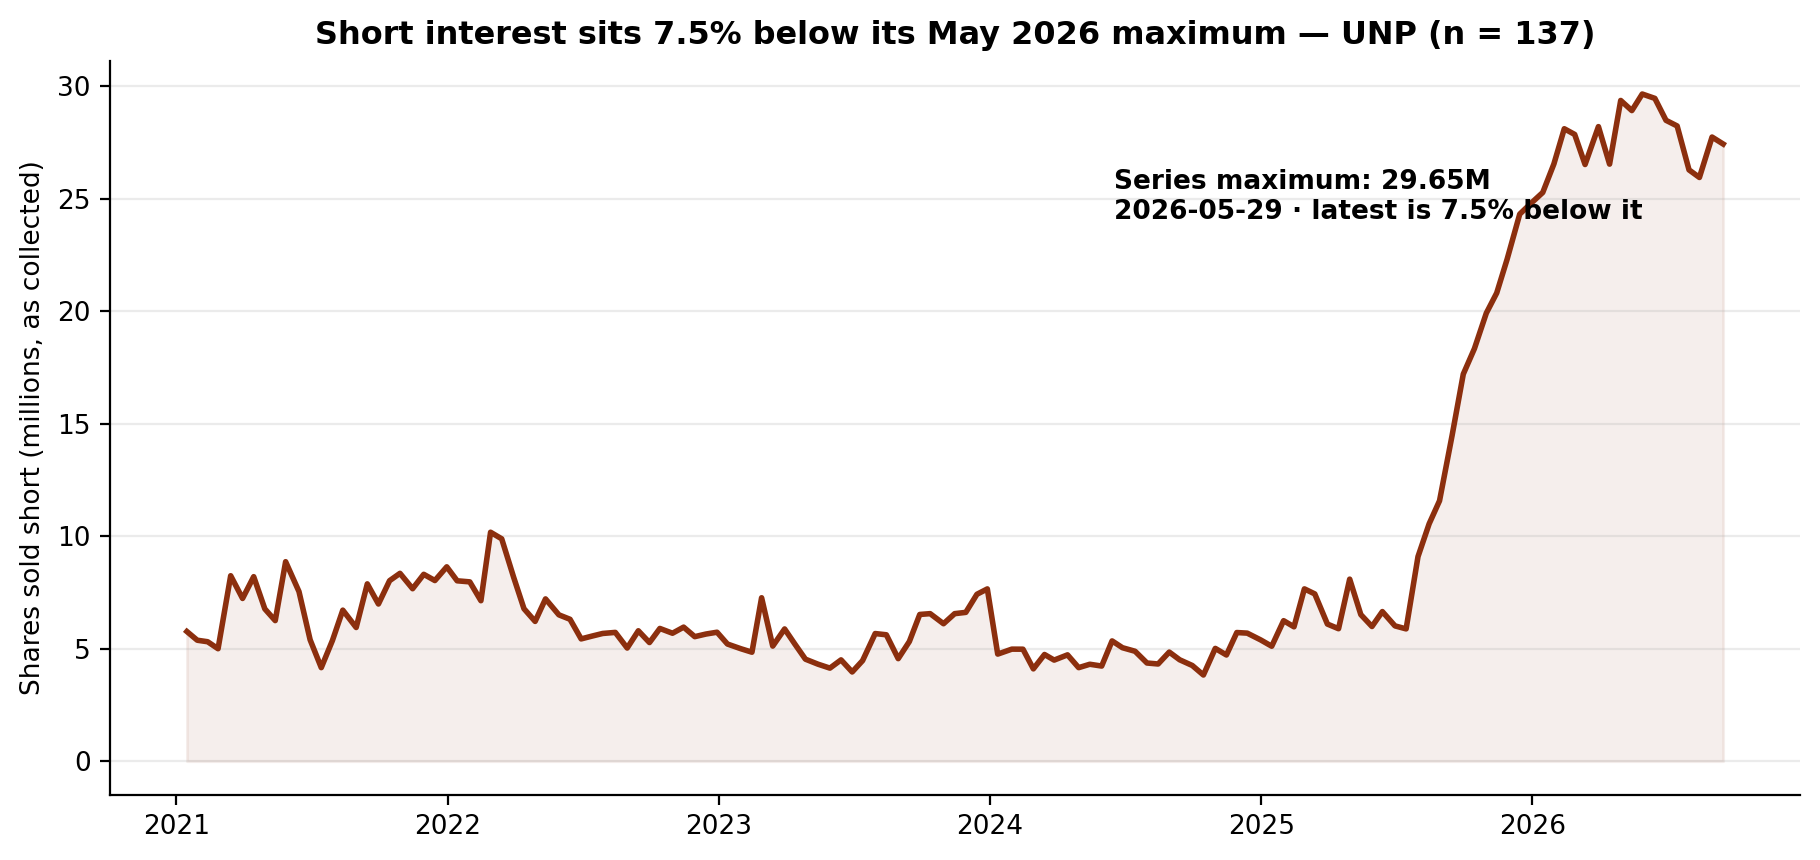
Lens 6 — short interest: 4.62% of shares, up 89.3% in a year, just below its maximum. The latest FINRA settlement, September 15, 2026, records 27,430,602 shares sold short at 14.38 days to cover, 4.62% of the share count in our fundamentals file (a measured count, methodology). The days-to-cover figure is the file's own arithmetic — the settlement's average daily volume prints at 1,906,923 shares, small against the borrow — and is reported as printed. The borrow is down 1.12% from the prior settlement, down 3.7% from the June 30, 2026 settlement (28,484,157 shares) and up 89.3% from the year-ago settlement (14,491,431 shares). The series maximum is 29,652,815 shares at May 29, 2026, and the latest reading sits 7.5% below it; the minimum is 3,831,236 shares at October 15, 2024. The summer's path: 28,484,157 (June 30), 28,233,358 (July 15), 26,281,287 (July 31), 25,944,217 (August 14), 27,740,373 (August 31), 27,430,602 (September 15) — six settlements in a high, narrow band.
The Gap
The narrative arriving this morning is an earnings print with raised expectations: a consensus of $3.47 a share, revised upward, freight volumes and an operating ratio to grade, and a proposed Norfolk Southern combination hanging over the story. The June tape underneath is busier than most. Institutions added 66,956,912 shares (+14.60%) in a quarter when the price itself rose 12.1%, and the tracked cohort added too — verified at +6.4% for continuing holders, plus a new 2,047,332-share Viking position — but the cohort's aggregate conceals two opposite books: Slate Path more than tripled and Third Point went from 100,000 to 350,000 shares, while EdgePoint cut 40.4% and Baupost cut 23.1%. Insiders contribute silence: no purchase anywhere in the parsed record, eight sales in all, and not one purchase or sale filed in the last 90 days. Congress contributes nothing at all — no aggregate row, no member row. The one lens that has moved decisively is the borrow: 4.62% of the share count, up 89.3% in a year, parked just below its May maximum through the summer. One plausible reading is that the October story is carried by the earnings setup and the merger question, while the filing record underneath shows institutions accumulating into a rising price, tracked managers rotating rather than agreeing, and a borrow that grew while nobody in the insider or congressional record traded at all.
What Would Change the Picture
Nothing above is a recommendation. These filings would change it:
- 1. The 2026Q3 13F season (filing window closing mid-November 2026). The baseline is 19 June common-stock holders with 12,128,043 shares, the continuing cohort verified at +6.4%, Viking new at 2,047,332 shares, and no September early filer holding the name. Whether Viking holds or extends its first position, whether Slate Path and Third Point keep adding after tripling and 3.5x-ing, and whether EdgePoint's cut continues would change this lens.
- 2. A first insider open-market purchase — the first in the parsed record — or any sale at all. The record through the October 2 window end holds 0 purchases against 8 sale-coded rows, and the last 90 days hold neither a purchase nor a sale. A single purchase filed after that date would break a pattern that currently has no exception in the record; a first sale in months would end the silence on the other side.
- 3. A first congressional trade in any file. The combined, House and Senate aggregates and the House member file all carry no row for this name. Any recorded purchase or sale, by any member, would change this lens.
- 4. A first SC 13D, or a 13G print above 10.0%. The register holds no activist filing at all; its maximum is the passive 10.0% print dated December 31, 2025. A 13D from any reporter, or a passive print above 10.0%, would change this lens.
- 5. Short interest above 29,652,815 shares, or below 25,944,217 shares. Above the May 29, 2026 series maximum would set a new series high; below the August 14, 2026 reading — the lowest of the last six settlements — would break the summer's high band on the downside.
Methodology and data notes
- As-of & limits: The lenses rest on different clocks, none live: 13F is a June 30, 2026 snapshot published up to 45 days later; Form 4 windows run through October 2, 2026 (the last Union Pacific filing in the parsed record is itself dated October 1, 2026); Congress aggregates run through October 3, 2026 (Senate through October 1, 2026); 13D/G through April 30, 2026; short interest through September 15, 2026; the price file ends October 2, 2026. Nine limits are specific to this audit. First, the roster expanded before the recent audits — from 85 managers (83 filing) to 149 (147 filing) — so "of 147" counts are not comparable to earlier pieces' "of 83" figures. Second, this name's common stock carries a single CUSIP (907818108), and the full-market by-CUSIP row matches the by-ticker aggregate on every field — holders, long holders, shares, reported value, prior holders and prior reported value — so no CUSIP blending question arises. Third, the tracked register's change labels are verified, not taken on trust: all 18 continuing holders were verified by accession identity plus CUSIP-overlap pairing — each June filing paired to a unique March filing, with every label recomputing exactly. The registers then reconcile with no remainder: the March 31 register holds 9,477,850 shares, equal to the verified continuing holders' 9,477,395 plus Mondrian's exited 455; the June 30 register holds 12,128,043 shares, equal to the June cohort's 12,128,043 exactly, because no September early filer holds this name and none carries a June register row for it. Two method notes belong here. A simpler prefix-matching pass verifies only 17 of the 18: Baupost is a unit-corrected filer whose manager-file total is restated in dollars while the pipeline register keeps the as-filed total, so a total-value lookup cannot find its June accession. Its June accession (0001061768-26-000010) is instead the unique register accession holding this CUSIP at exactly Baupost's 1,185,395 shares, its March pairing (accession 0001061768-26-000007; CUSIP overlap 20, unique) recomputes its −23.1% label exactly, and the register's own Baupost row prints its value as 322,427 in as-filed thousands against the manager file's corrected $322,427,000 — a units artefact in the value field only; every share count agrees. Viking's NEW label was audited the same way: Viking's March filing (accession 0001103804-26-000004, CUSIP overlap 55 with its June filing) contains no row for this CUSIP, so the position is genuinely new. Fourth, the full-market aggregate implies $267.57 against the June 30 close of $272.00 (−1.63%): the aggregate is a reported sum that includes option rows, so its implied price need not equal the close; this audit uses filer counts and share counts as this lens's primary measures and reports the value as reported only. The tracked cohort's own aggregate implied price is exactly $272.00 — all 19 holders imply the close exactly. Fifth, the insider lens rests on a single aggregate bucket — this issuer's filings sit under one symbol spelling, "UNP", with no case split — cross-checked against a row-level scan of all 229 parsed filings for the issuer (CIK 100885): filing counts, transaction counts, share counts, officer-row counts and values reproduce exactly in every window, with a value difference of $0.00 in all three windows and no accession appearing under more than one symbol spelling. On that record, the insider implied-price checks that apply pass: the one-year implied sale price of $269.11 sits inside its filing-window close range ($216.37–$310.62), and the full-record figure ($263.85) inside the full price range ($185.72–$310.62); the 90-day window holds no sale rows and no window holds any purchase rows, so no other implied-price check applies. The site's insider aggregate (dated October 22, 2026, a 90-day window ending that day) carries no row for this name at all, consistent with a 90-day window in the full parse that holds no purchase or sale rows; this audit uses the full parse throughout. Sixth, the congressional lens is absent in every file this audit reads — combined, House and Senate aggregates and the House member file — and is reported as absent; no figure is estimated for it. Seventh, the 5% register's cross-date share total of 104,150,767 is an arithmetic sum of 3 single-reporter rows across different reporters and as-of dates, including one reporter's own 0-share print, and is not a current combined stake; each print is reported individually in the text. Parsed totals match the aggregates exactly. Eighth, the short-interest series holds no step of 2x or more and no step to one-half or less (the largest step is 1.649x, at March 15, 2021, from 4,998,746 to 8,242,888 shares; the smallest is 0.622x, at January 12, 2024), so the series is continuous on this measure across its full span. No row carries a split flag; two rows carry a FINRA revision flag (April 15, 2021; June 15, 2021). The issuer-name field reads "Union Pacific Corp." at all 137 settlements, on a single market class (NYSE) throughout. The latest settlement's 14.38 days to cover is the file's arithmetic on its own average daily volume of 1,906,923 shares, reported as printed. The share count behind the short-interest percentage is 594,075,498 shares in our fundamentals file, a measured period-end count (dei/EntityCommonStockSharesOutstanding, as of July 17, 2026), so the 4.62% figure rests on a measured denominator. Ninth, our price file records no single-day close move across the thresholds this audit normally treats as split patterns, and records no split factor for this name. The company's fundamentals as collected print fiscal 2025 revenue of $24,510,000,000, net income of $7,138,000,000 and assets of $69,698,000,000; those figures are reported as collected and are not used in any lens above. Every price statement from our own file is mechanical, a date and a close. The October figures in The Hype — the October 22 earnings date and the consensus estimate — are events published after our price file ends, and are cited as such, not blended into file-based calculations.
- Market context sources: WEEX TradFi Daily, October 22, 2026 (Union Pacific among the October 22 earnings-focus names, before the open). Zacks, October 20, 2026 (third-quarter 2026 results on October 22 before market open; consensus EPS $3.47, up 12.7% year over year; revenue estimate $7.12 billion, up 13.97%; consensus revised upward 2.06% over 60 days). TickerOn earnings preview, October 2026 (focus on freight volumes, the operating ratio, and updates on the proposed Norfolk Southern combination). Google Trends US daily snapshot via Cyber Kendra, updated October 22, 2026 (top queries are sports and entertainment names; no stock query appears, so the earnings-focus selection above is the fallback basis). Figures we could not confirm were left out; the external items above are reported figures from those outlets, not GetCoattail measurements.
- Union Pacific is in the GetCoattail stock-page universe: Union Pacific (UNP) stock page. Series data: unp_lens_data.csv · unp_short_interest_series.csv. Earlier audits: Procter & Gamble · ON Semiconductor.
Past patterns are not a promise of future results. For education only — not investment advice.
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history: v1.0 — October 22, 2026: first publication.