GetCoattail Research — The Filing Tape #192. United Rentals through six filing lenses, as of the latest filings. Past patterns are not a promise of future results. For education only — not investment advice.
The Hype
United Rentals is having a week. On October 23, 2026, Zacks added United Rentals to its Rank #1 (Strong Buy) list — one of five additions that day — noting that the Zacks Consensus Estimate for its current-year earnings had risen 0.7% over the last 60 days (Zacks, "New Strong Buy Stocks for October 23rd", October 23, 2026). The reason is fresh: on October 21, United Rentals reported record third-quarter 2026 results — $4.893 billion of total revenue (+15.7% year over year), rental revenue of $4.316 billion (+17.8%, a quarterly record), adjusted EPS of $15.55 (+32.9% year over year, beating the Zacks consensus of $13.83 by 12.4%), and raised its full-year 2026 guidance (revenue $18.0–$18.2B, adjusted EBITDA $8.3–$8.4B) (press release, October 21, 2026).
The tape reacted: +2.41% on earnings day to $1,068.98, then +3.93% the next day to $1,111.02 on 1.1 million shares — well above the ~476,000 50-day average — before slipping 1.09% to $1,098.88 on Friday, October 23 (MarketWatch, checked October 24, 2026). That close sits 6.8% below the 52-week high of $1,179.18 reached August 7 (stockscan.io, checked October 24, 2026).
The story being told is straightforward: the world's largest equipment rental company is riding a large-project construction cycle, and the analysts want more. The question the filings let us ask is different: while the earnings tape played, what were the professional holders and the company's own people actually doing with their shares?
The Tape
| Lens | As of | What the filings show | Direction vs prior period |
|---|---|---|---|
| Superinvestors (13F) | Jun 30, 2026 | 8 of 147 tracked managers hold; 67,770 shares ($76.8M reported). Markel's 31,150 shares are 46.0% of the cohort, unchanged; Wedgewood cut −33.6%. | Cohort −10.1% (verified, 8 continuing) |
| All institutions (13F) | Jun 30, 2026 | 1,600 filers hold 56,932,822 shares ($64.6B reported). | Shares +14.18%; filers +158 |
| Insiders (Form 4) | Oct 2, 2026 | One open-market buy (68 shares, $53.3K) in 91 filings; 12 sells, $35.4M, 6 sellers, officer buys 0. | Selling continued; buys near-absent |
| Congress | Oct 3, 2026 | Rep. Salazar (R) reported 1 buy, Apr 24, 2026 ($1,001–$15,000). No Senate transactions. | One small buy |
| 13D/G | Apr 30, 2026 | Passive only. The Vanguard Group amended to 0.0%; Vanguard Capital Management filed a new 7.5% 13G. | Churn among passives |
| Short interest | Sep 15, 2026 | 1,546,035 shares short, 2.47% of shares outstanding; −63.1% from the Jan-2021 peak. | Low and steady |
Chart: URI through six filing lenses — who is actually there?
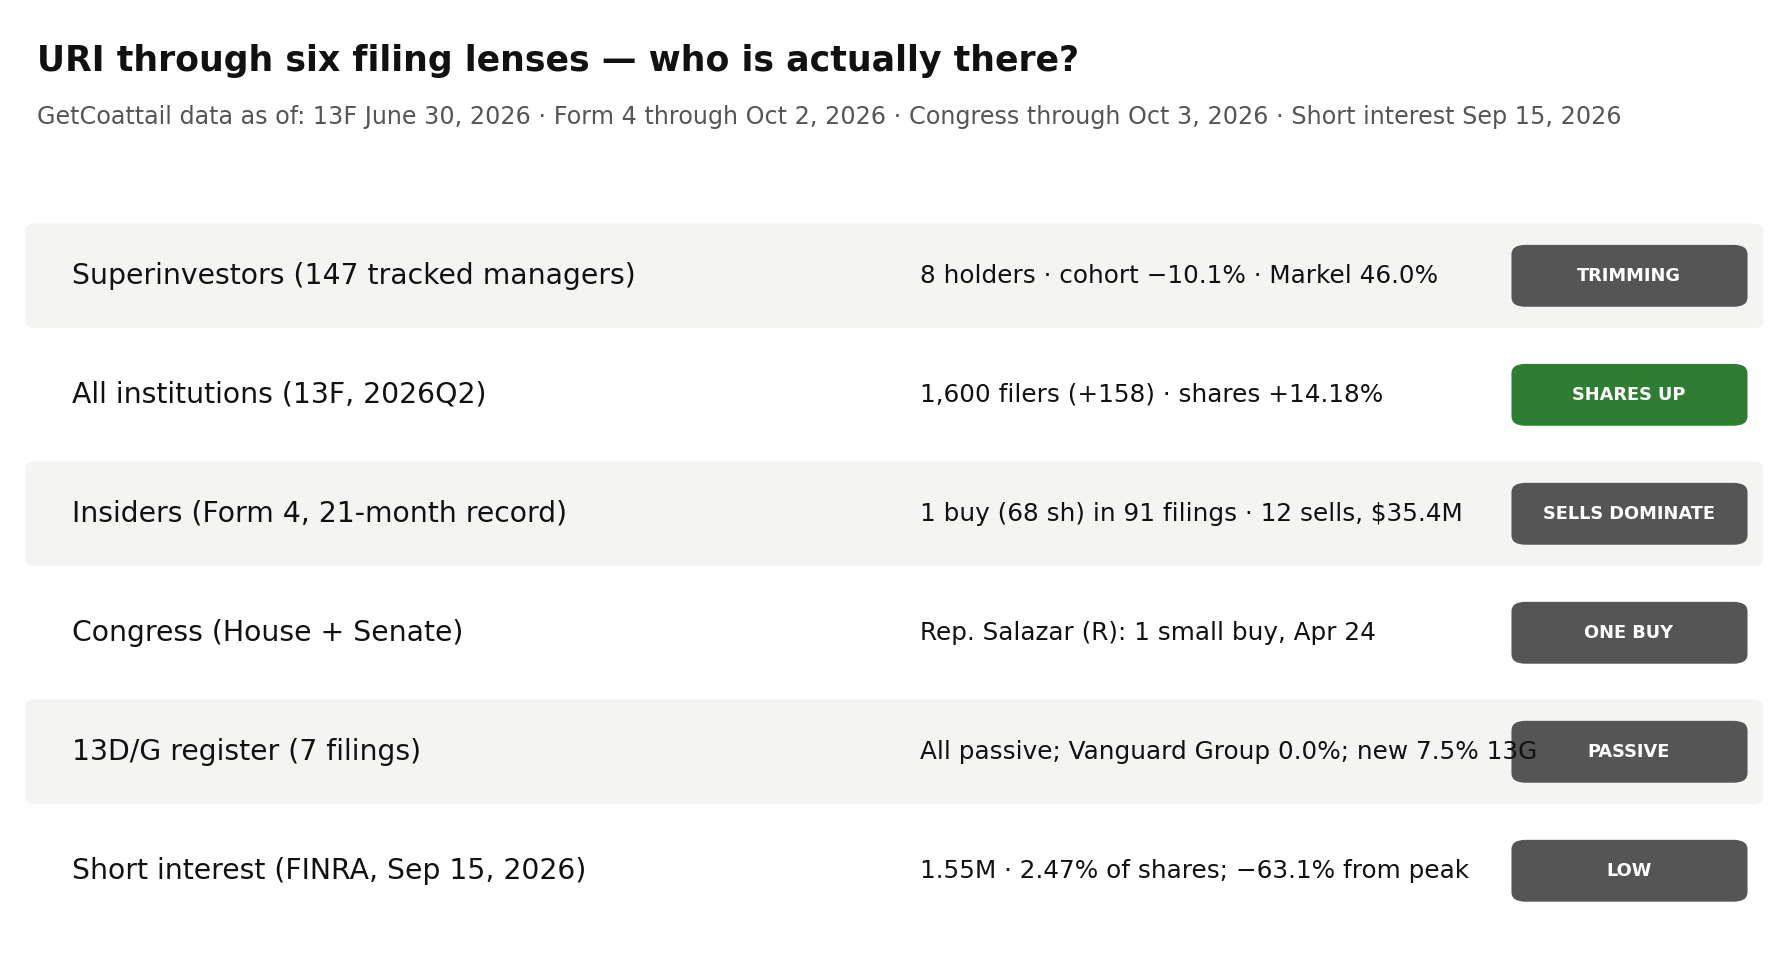
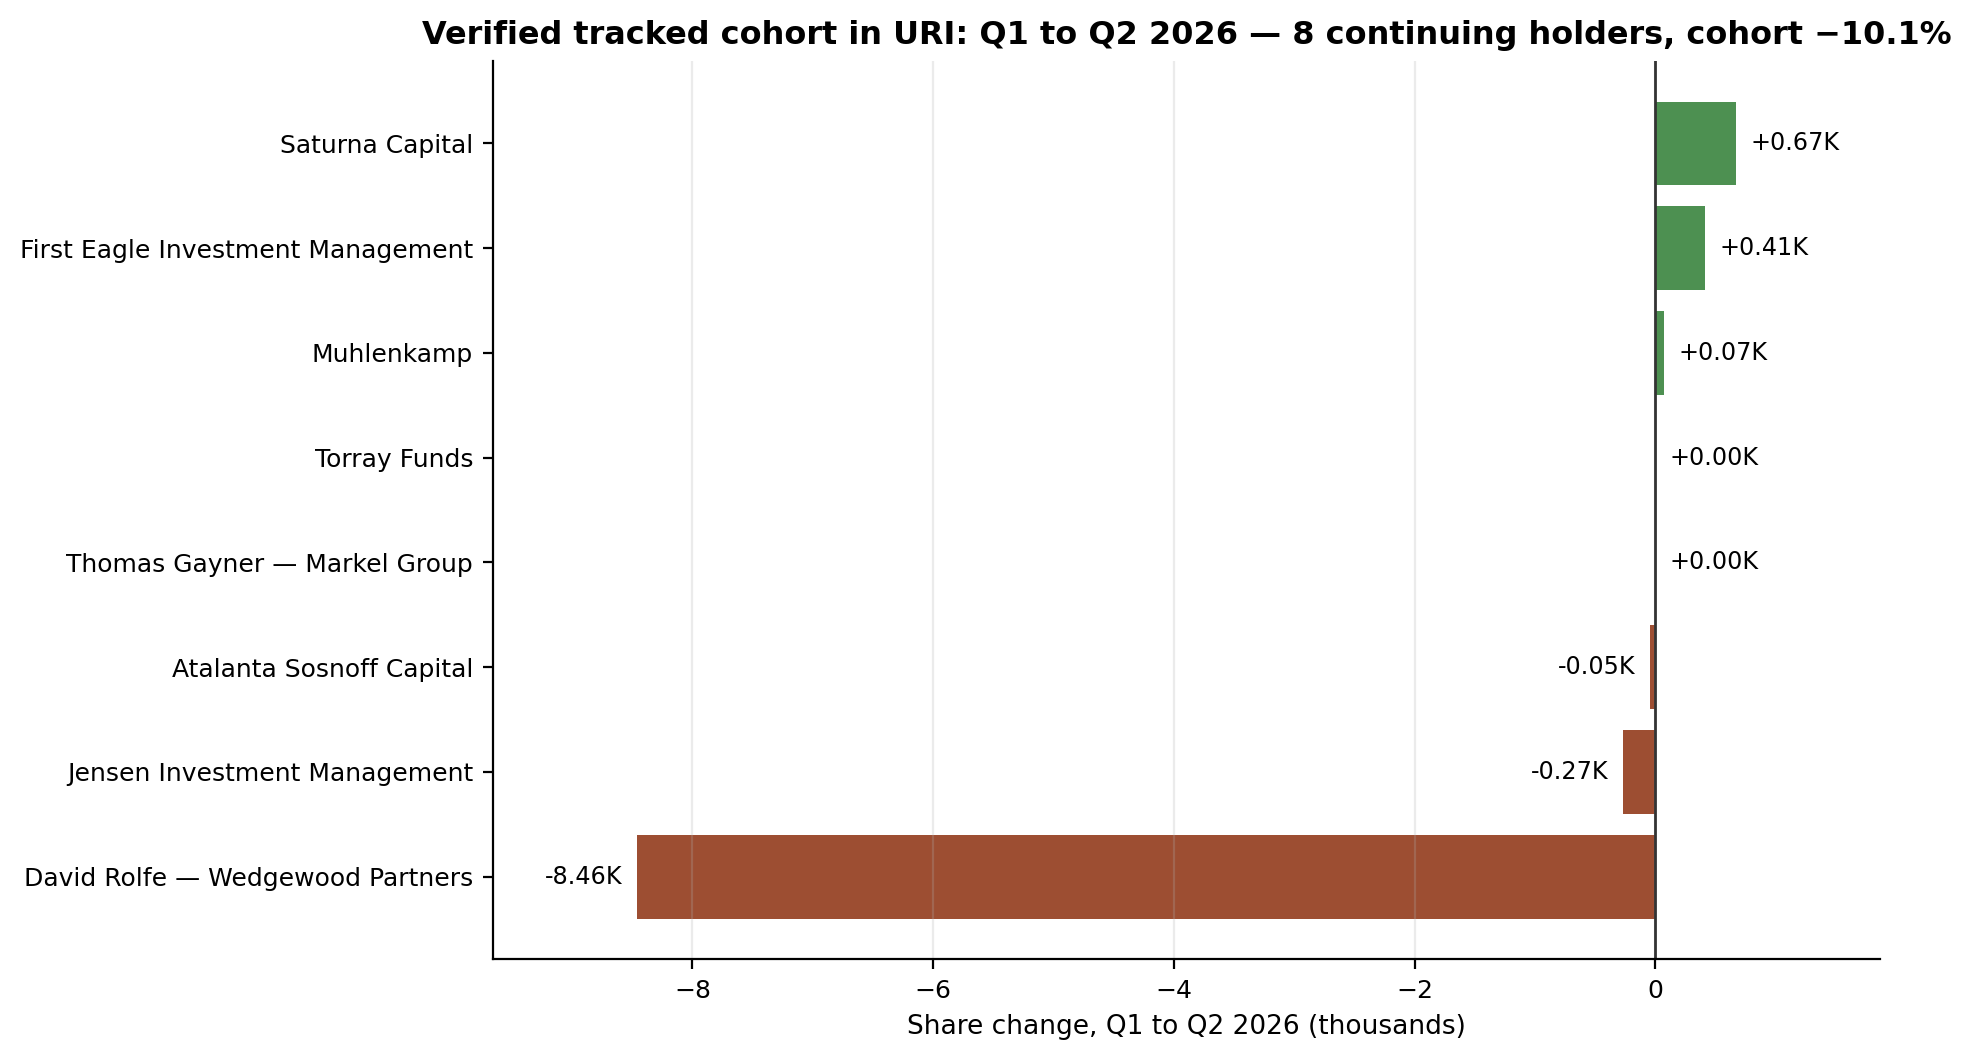
Superinvestors. The June-quarter register shows 8 of the 147 tracked managers holding United Rentals common stock — 67,770 shares, $76.8M at reported values, about 0.12% of all institutionally reported URI shares. The concentration is extreme: Thomas Gayner of Markel Group's 31,150 shares are 46.0% of the cohort, and David Rolfe's Wedgewood Partners 16,732 another 24.7% — two names are 70.7% of the tracked stake. Gayner sat still. Wedgewood cut 33.6% (25,192 → 16,732 shares). The verified continuing cohort — all 8 managers present in both Q1 and Q2, paired by accession identity and CUSIP overlap with every change label recomputed exactly — shrank from 75,400 to 67,770 shares, −10.1%. The direction mix beneath that: 3 increased, 2 unchanged, 3 decreased — with no new positions opened and no full exits. The two big percentage gainers (Saturna +230%, First Eagle +6,833%) came from 290- and 6-share bases respectively: trivial in share terms. The cohort's implied price of $1,132.88 sits within $0.01 of the June 30 close, so the share arithmetic is clean.
Chart: verified tracked cohort in URI — Q1 to Q2 2026 share change.
All institutions. The full 13F market went the other way: shares rose 14.18% (+7,070,190 to 56,932,822) and the filer count grew by 158 to 1,600, with 1,330 entering filers against 1,172 leaving. Reported value jumped 76.03% to $64.6B — the price did the heavy lifting there. The tracked cohort's −10.1% sits against a broader institutional bid, not with it.
Insiders. The Form 4 record is lopsided. Across 91 parsed filings for United Rentals (record span January 2, 2025 through October 1, 2026; aggregated as of October 2, 2026), there is exactly one open-market purchase: 68 shares for $53,268.33, bought by Singh Shiv on February 2, 2026 (filed February 9, 2026, as an amended Form 4) — a non-officer. Officer buys are zero in the 90-day, 1-year, and full-record windows alike. Against that single buy: 12 sell transactions covering 39,277.71 shares and $35.4M, from 6 distinct sellers. In the last year: 7 sells, 31,575.71 shares, $30.5M — every one an officer sell. In the last 90 days: 1 sell, 1,500 shares, $1.7M (Grace, an officer). The parsed-file scan matches the aggregate buckets on every transaction count and value, and United Rentals' filings appear in the corpus under issuer CIK 1067701 — this is not a coverage artifact.
Congress. One House member, Maria Elvira Salazar (R), reported a single URI purchase on April 24, 2026 (amount $1,001–$15,000). No member of the Senate reported any URI transaction. That is the entire congressional tape on this stock.
13D/G. The control register is passive-only: 7 filings, all Schedule 13G, no activist 13D. But the passive crowd has been churning. Capital International Investors filed at 5.4% (event September 30, 2025) and then amended down to 1.1% (event December 31, 2025). Capital Research Global Investors went from 4.4% (event December 31, 2024) to 5.2% (event June 30, 2025) and back to 4.6% (event September 30, 2025). The Vanguard Group amended its 13G to 0 shares and 0.0% (event March 13, 2026) — exited. And Vanguard Capital Management filed a new 13G at 7.5% (4,720,155 shares, event March 31, 2026, filed April 30, 2026).
Short interest. The bear trade is long gone and the book is quiet. FINRA short interest stood at 1,546,035 shares at the September 15 settlement — 2.47% of the 62,646,557 shares outstanding, 3.87 days to cover, and 63.1% below the January 2021 peak of 4,190,355. It did tick up 8.21% from the August 31 settlement (1,428,713 → 1,546,035) and sits 3.4% above the June 30 settlement — a mild uptick off a low base, not a re-engagement. It is 18.4% below where it was a year ago.
Fundamentals context. The fundamentals record is complete on the fields quoted here: shares outstanding 62,646,557 as of April 20, 2026, revenue $16,099,000,000, net income $2,494,000,000 and assets $29,866,000,000, all for FY2025. The recorded market capitalisation is $67,697,122,119.45, on the record's own price_close ($1,080.62 as of October 6, 2026), not the October 23 close. The Q2 price move frames the setup: the stock ran 55.5% in Q2 ($728.56 → $1,132.89) while the tracked cohort was trimming −10.1% — the cohort sold into strength, not weakness. Through October 2 the stock was up 33.6% year to date; the October 2 close ($1,081.04) sat 4.6% below June 30, and the October 23 close ($1,098.88) sits 3.0% below June 30 and 6.8% below the 52-week high.
The Gap
The analyst tape and the filing tape agree that institutions want this stock — but they disagree on whose money it is. Zacks' Strong Buy addition, the record-quarter beat, and the raised guidance sit alongside a full 13F market that added 14.18% more shares and 158 filers in Q2. Yet the managers GetCoattail tracks — the concentrated stock-pickers — were trimming (−10.1% verified), led by Wedgewood's 33.6% cut, with not a single new position opened. The gap is inside the building too: officers have not bought a share on the open market in the 21-month parsed record, while insiders sold $35.4M in it, $30.5M of that in the last year alone. Even Congress's lone recorded trade is a sub-$15,000 purchase — a token next to the insider selling. And the passive register's churn — Vanguard Group out to 0.0% while Vanguard Capital Management files a new 7.5% 13G — reads like the index crowd rebalancing rather than a conviction change.
One plausible reading is that the "smart money" that matters here is the crowd of 1,600 filers buying the equipment-rental cycle, while the named managers we track took Q2's 55.5% rally as a gift to lighten. The 45-day 13F lag cuts the other way: the June picture predates the earnings beat, and none of the three September early filers holds URI.
What Would Change the Picture
Nothing above is a recommendation. It is a record. What would change it:
- 1. An officer open-market purchase. Any Form 4 buy code "P" from an officer would end a 21-month drought and would show up on URI's insider record within days of filing.
- 2. Q3 13F season (filings due by November 16, 2026). Watch whether Markel added or stayed still, whether Wedgewood's 33.6% cut continued, and whether any of the 147 managers opened a new URI position after the earnings beat.
- 3. The next short-interest settlements. The +8.21% uptick off a low base bears watching: two more rising settlements would signal the bear trade re-engaging; a reversal would confirm it was noise.
- 4. A new 13D or 13G. An activist 13D, or the passive crowd (Capital, Vanguard) moving again after March's churn, would reset the control-register picture.
- 5. Post-earnings Form 4s. Q3 results landed October 21; the next insider filing window will show whether anyone inside the company bought the beat — or sold it.
As-of & Limits
| Lens | As of |
|---|---|
| Superinvestors (13F) | June 30, 2026 — quarter-end; funds have up to 45 days after quarter-end to file |
| All institutions (13F) | June 30, 2026 — same 45-day lag |
| Insiders (Form 4) | Aggregated October 2, 2026 (parsed record span January 2, 2025 – October 1, 2026) |
| Congress | October 3, 2026 (House 2026 PTR filings, transactions on/after April 1, 2026) |
| 13D/G | April 30, 2026 (latest filing date in the corpus) |
| Short interest | September 15, 2026 settlement |
13F figures are as of June 30, 2026, the quarter-end. Funds have up to 45 days after quarter-end to file, so this is the most recent complete picture — and it is always a lagging one. 13F covers long positions of $100M+ managers only. United Rentals' Form 4 and SC 13D/G filings appear in our corpora under issuer CIK 1067701 ("UNITED RENTALS, INC."). The site's insider aggregate has no URI row, so the Form 4 numbers here come from the pipeline corpus rather than the site's insider aggregate. Trading costs and taxes are not reflected.
This article describes filings and market data for education. It is not investment advice. Past patterns are not a promise of future results. For education only — not investment advice.
Revision history: v1.0 — October 25, 2026. Initial publication. Signals and lens aggregates: uri_lens_data.csv. Short-interest series: uri_short_interest_series.csv.
Past patterns are not a promise of future results. For education only — not investment advice.