GetCoattail Research — Dell just reported the strongest quarter in its history — revenue up 58%, a $95 billion AI server backlog, and full-year guidance raised by $25 billion — and its stock has risen 346.9% this year in our price file. We ran it through every filing lens we maintain. The broad register piled in. The concentrated cohort almost entirely left, in the very quarter the price rose 162.9%.
Start with the narrative, because it is unusually concrete. Dell reported fiscal second-quarter 2027 results on September 1, 2026: revenue of $46.97 billion, up 58% year over year and ahead of a consensus of roughly $44.9 billion; non-GAAP EPS of $7.04 against expectations of about $4.91, up 203% year over year; $60.9 billion of AI server orders booked in the quarter, $16.4 billion of AI-optimised server revenue, and a record $95 billion AI backlog. Management raised full-year revenue guidance by $25 billion to $192 billion and AI server revenue guidance to $74 billion, from $60 billion. The stock rose 15.8% the day after the print and another 4.8% the day after that. Dell was the eighth most-searched ticker on Benzinga Pro for September — its first appearance in that top twelve in 2026 — and consensus price targets average roughly $560 to $571. Forbes had the shares up about 345% in 2026 by late September.
Now the filings. GetCoattail tracks the portfolios, trades and disclosures of the investors best placed to know any given company: superinvestors, institutions as a whole, insiders, members of Congress, and 5% holders. For Dell — the eleventh Filing Tape audit, after IREN, CoreWeave, Micron, NVIDIA, Tesla, AMD, Apple, Amazon, Meta and Oracle — the story the broad market is telling and the story the concentrated filings tell are not the same story.
Lens 1: the superinvestors — three holders, down 82.8% in the best quarter
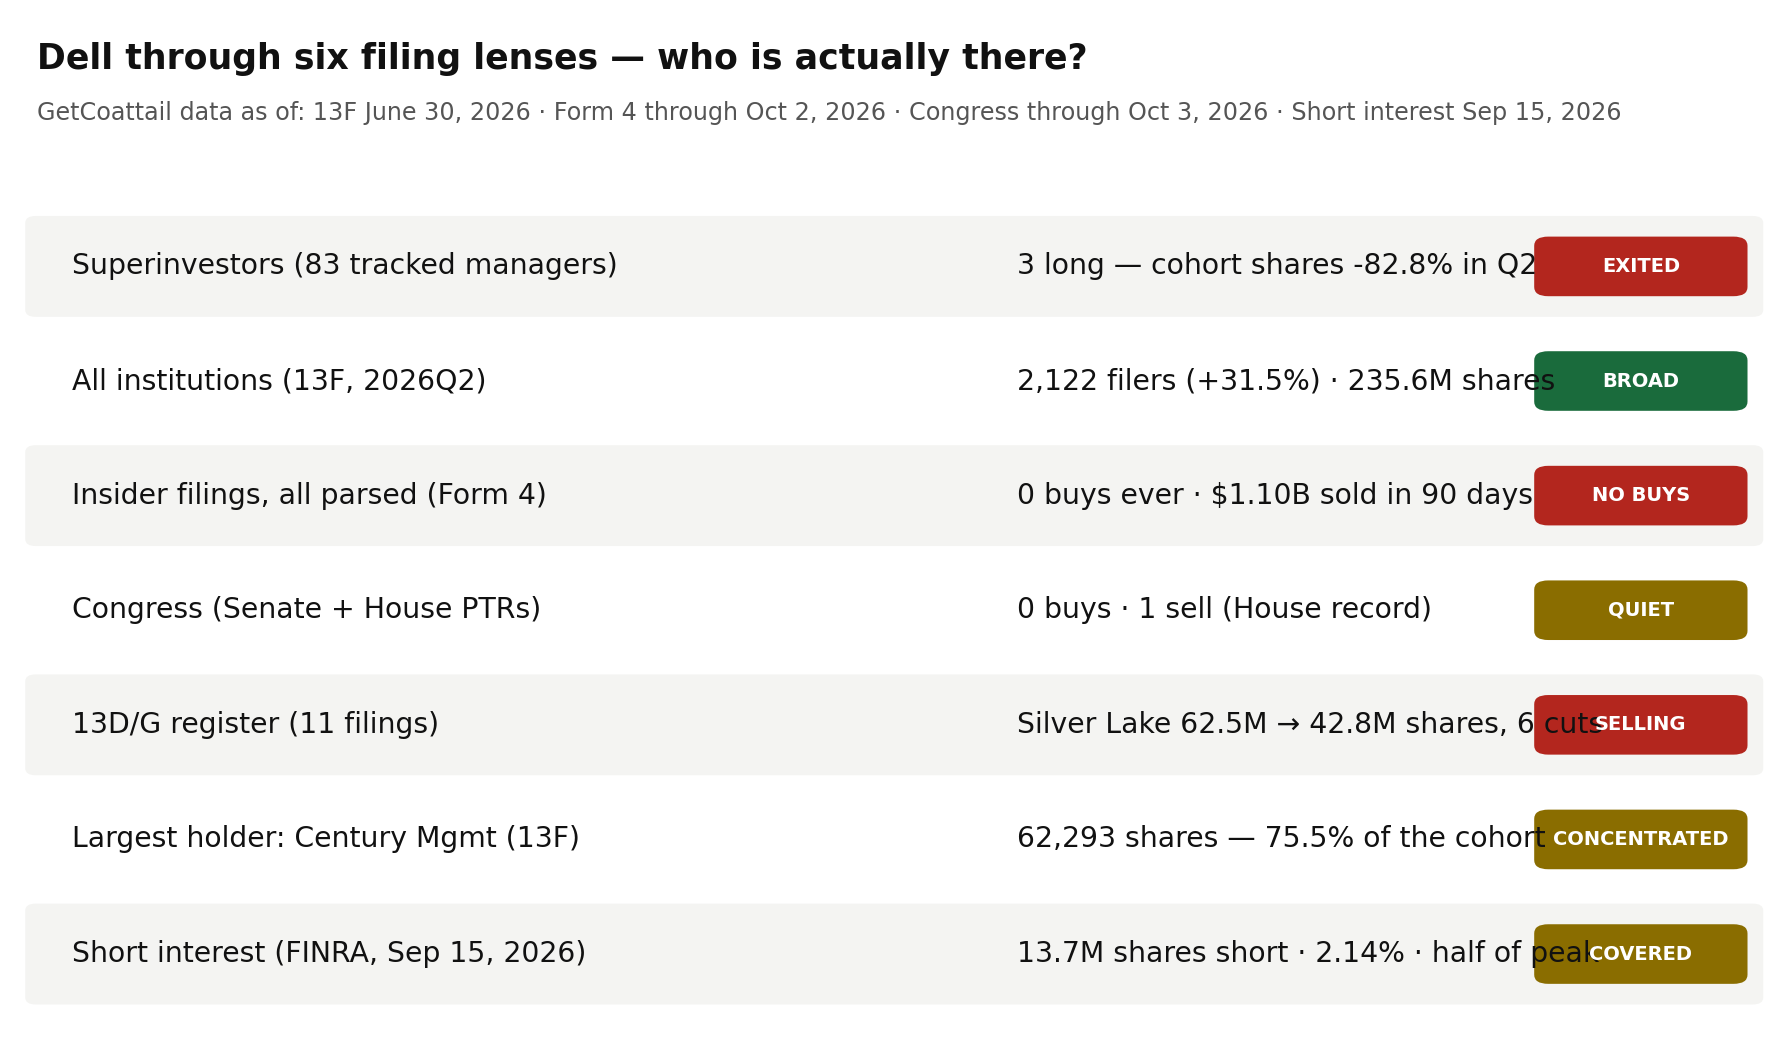
We track 83 large, mostly long-only managers whose 13F portfolios we collect directly from SEC EDGAR. As of June 30, 2026, three held Dell in long common-stock positions — every one of the three reported rows is a long position, with no option rows in the count. On a like-for-like pipeline basis the cohort's combined position fell from 480,167 shares at March 31 to 82,478 shares at June 30 — down 82.8% — in a quarter when the share price did the opposite, closing at $164.13 on March 31 and $431.46 on June 30 in our price file (+162.9%). The pipeline and EDGAR-collection second-quarter totals agree exactly, at 82,478 shares, worth $35,585,958.
The composition matters more than the count: the row count did not change — three rows in March, three in June — while the holders did. The March register's largest position, First Pacific Advisors with 382,985 shares, was 79.8% of the entire first-quarter cohort, and it has no Dell row at all in the second-quarter collection: a complete exit. The one new name, Maverick Capital, opened a position of 2,935 shares. What remains is 82,478 shares: Century Management with 62,293 shares — 75.5% of what is left — cut 20.4% in the quarter, and Dodge & Cox with 17,250 shares cut 8.7%. Of the three second-quarter holders, two decreased and one was new; none increased. This is not a cohort that rotated. It is a cohort whose largest member left during a 162.9% quarter, leaving a residual position smaller than the rounding on the story outside.
Lens 2: institutions — 2,122 filers, up 31.5%
Zoom out to the whole 13F market and the register points the other way, as it did for Oracle. At June 30, 2026, 2,122 institutions reported positions in Dell, up from 1,614 at March 31 — a 31.5% rise — and 2,111 of them reported long positions. Reported share counts rose 9.23%, from 215,733,793 to 235,648,323 shares, with 1,705 filers entering and 1,197 exiting during the quarter. The dataset's reported aggregate value rose 189.6% to $117,886,783,158, a rise mostly explained by the quarter's 162.9% price increase; the aggregate includes option rows, so we treat filer and share counts as the reliable series and the dollar figure as reported (see methodology). The contrast inside one quarter is the fact: breadth expanded by almost a third and the full register added shares, while the concentrated cohort cut 82.8% of its position.
Lens 3: the 5% register — a sponsor leaving in instalments, a founder trimming
Dell's 5% register contains the two holders who know the company best, and both series point down. Eleven SC 13D/G filings cover Dell in our full-parse aggregation — six 13D filings and five 13G filings, from 15 reporters, the most recent filed September 11, 2026. The 13D chain belongs to Silver Lake, the private-equity sponsor of the 2013 buyout. In the group row of its own amendments, Silver Lake Group reported 62,513,399 shares (14.8%) as of January 8, 2025, then 58,887,472 (14.7%) in July 2025, 54,300,981 (13.8%) in October 2025, 50,240,830 (13.6%) in March 2026, 46,485,717 (12.5%) in June 2026, and 42,809,317 shares (11.9%) as of September 9, 2026 — a decline at every one of the six parsed filings, and 31.5% below the first. The founder's own register moved the same direction, more slowly: Michael S. Dell's amended 13G reported 283,169,860 shares (46.8%, as reported in the filing) as of March 31, 2025, and 265,674,689 shares (45.7%) as of December 31, 2025, a reduction of 17,495,171 shares (−6.2%). The passive register is present — Vanguard entities report 29,121,530 shares (8.57%) and 22,512,097 shares (7.07%) — but no new 13D, the filing an investor uses when it wants something from management, has appeared.
Lens 4: insiders — zero purchases, in every window
The insider lens is the starkest in this audit. Across the entire parsed Form 4 record for Dell (311 filings through October 2, 2026), there is not one open-market purchase transaction — zero in the last 90 days, zero in the last year, and zero across the full parsed record, by officers or by any other insider. The selling side is heavy and continuous. In the 90 days through October 2, 2026, insiders filed 89 reports covering 1,102 sale transactions totalling 2,148,372 shares and $1,103,128,611.20, by twelve sellers; counts here are transaction rows, and a single filing can carry many. Over the full year, sales total 2,777 transactions and $5,083,421,660.74 by 22 sellers. Across the entire parsed record, sales total 3,178 transactions and $8,059,444,861.56 by 25 sellers. Some selling is mechanical — vesting, tax withholding and pre-arranged plans generate filings regardless of anyone's view — and we assign no motives. What the record establishes is narrower: in a year when the stock rose 346.9% in our price file, no insider at any point recorded a purchase at market price.
Lens 5: Congress — one sale, no buys
Across the Senate and House transaction record we maintain (as of October 3, 2026), Dell shows one sale transaction and zero purchases. The single sale sits in the House aggregate; the Senate aggregate carries no Dell record at all. Congressional disclosures report value ranges rather than exact amounts, so we record direction only.
Lens 6: short interest — half the February peak, at 2.14% of the share count
As of September 15, 2026 — the most recent FINRA settlement date — 13,693,224 Dell shares were sold short, down 5.20% from 14,444,059 at the August 31 settlement. That is 2.14% of the 640,000,000 shares outstanding in our fundamentals file (a share count as of July 31, 2026), with days-to-cover of 1.00.
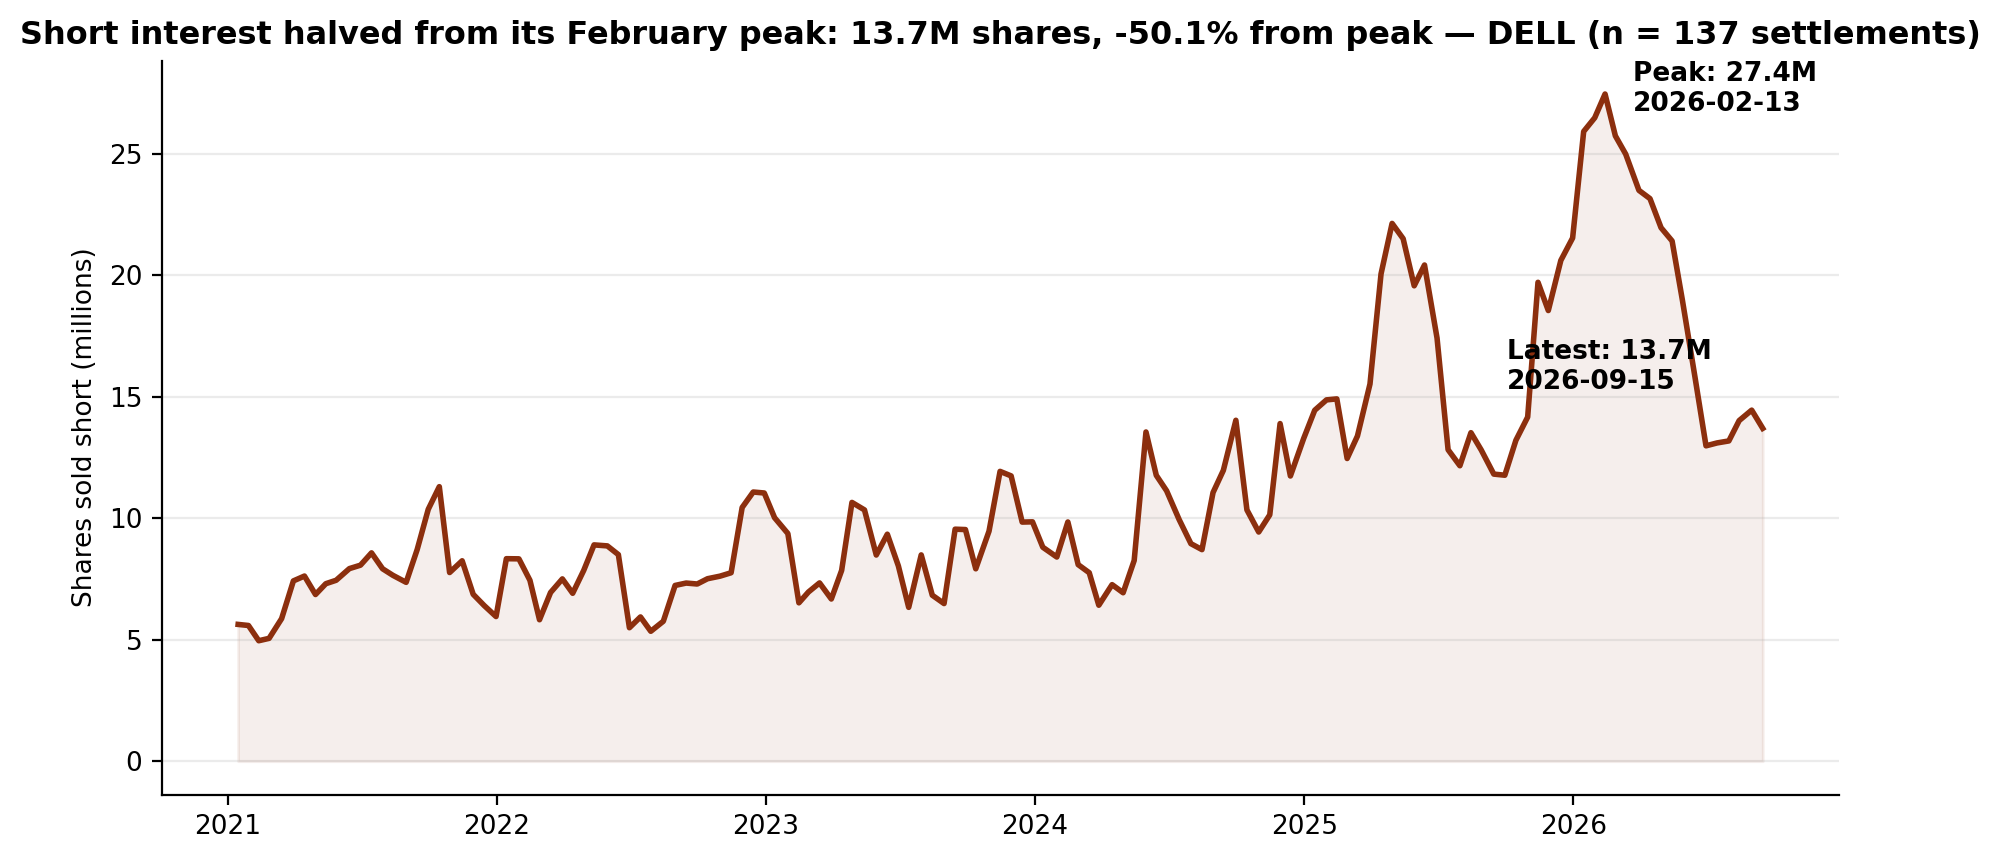
Short interest peaked at 27,449,476 shares on February 13, 2026 — before the second-quarter explosion — and the latest reading is 50.1% below that peak: the borrow halved while the price roughly quadrupled from its January levels. Over the last five settlements the series has been roughly flat, between 13,094,061 and 14,444,059 shares.
The gap, stated plainly
Dell's filing record splits by register size. The broad register accumulated: 2,122 filers, up 31.5% in a quarter, reported shares up 9.23%. The concentrated registers did the opposite. The superinvestor cohort fell from 480,167 shares to 82,478 — down 82.8% in a quarter when the price rose 162.9% — because its largest holder, at 79.8% of the cohort, exited completely, and neither of the two remaining holders added a share. The sponsor that took Dell private has reduced its reported stake at six consecutive filings, from 62,513,399 shares to 42,809,317. The founder's reported stake fell 6.2% across 2025. Insiders have sold $8,059,444,861.56 across the parsed record and recorded zero purchases in it. Congress has sold once and never bought, and the short borrow has halved from its February peak. One plausible reading is that the record describes a stock carried upward by breadth, index machinery and a genuine operating print, while nearly every register that requires a named, concentrated decision has been reducing. The record supports each clause separately; it does not say which register is right.
What would change the picture
Nothing above is a recommendation. It is a record. These are the filings that would change the description:
- 1. The 2026Q3 13Fs (filing window closing mid-November 2026). Whether any tracked manager rebuilds a Dell position after the September print, and whether Century's 62,293 shares survive a second quarter, is the cleanest test of whether the second-quarter exit was profit-taking or a verdict.
- 2. The Silver Lake 13D chain. The sponsor's group stake has fallen at six consecutive filings, most recently to 42,809,317 shares (11.9%) on September 9, 2026. A filing that holds or raises the stake breaks a two-year pattern; another reduction extends it.
- 3. A first insider purchase — any purchase. The parsed Form 4 record contains zero open-market purchases. A single purchase transaction, from any insider at any size, changes this lens from blank to present; continued silence through the next quarter keeps it at zero.
- 4. The short-interest series from half its peak. The borrow halved from 27,449,476 shares (February 13, 2026) to 13,693,224. Whether it rebuilds toward the peak or fades below 13 million is the fastest-updating series in this audit: FINRA publishes it every two weeks.
- 5. Fiscal third-quarter results, expected around December 2026. The next print tests the narrative the filings are arguing over — a $95 billion AI backlog against the guidance of $192 billion of revenue for the year.
Until one of those prints, the filing record describes a stock the broad register accumulated and the concentrated money left, whose sponsor has been selling in instalments for almost two years, and whose insiders have never recorded a purchase.
Related reading: Fourteen of 83: One Holder Is 62.6% of the Superinvestors' Oracle Stake. Short Interest Just Hit a Record. — Filing Tape #10; Zero of 83: The Superinvestors Aren't in IREN — Filing Tape #1; 80% Overlap, No Copycat Signal: Congress vs. the Superinvestors. Dell's own page: Dell Technologies (DELL) on GetCoattail.
Methodology and data notes
- Superinvestor lens: 83 managers collected directly from SEC EDGAR Form 13F (managers_13f collection), positions as of June 30, 2026; Dell identified by CUSIP 24703L202. Three distinct managers hold long positions totalling 82,478 shares; all three reported rows are long (no put or call rows). Quarter-to-quarter cohort totals (480,167 shares across 3 pipeline rows at March 31; 82,478 across 3 pipeline rows at June 30) are from the site pipeline's holdings files on the same CUSIP basis in both quarters; the change is −82.8% ((82,478 / 480,167) − 1), and the pipeline's second-quarter total agrees exactly with the EDGAR collection's long total (difference: 0 shares). The March register's largest row (382,985 shares) is attributed to First Pacific Advisors by matching the filing's accession CIK (0001377581) to our manager registry; that manager has no Dell row in the second-quarter collection. Century Management's share of the remaining cohort is 62,293 / 82,478 = 75.5%. Direction counts across the three long holders: 2 decreased, 1 new, 0 increased, 0 unchanged.
- Full-market lens: SEC Form 13F Data Sets full-market aggregation (the fixtures underlying our 2026Q1–Q2 market tables). Holders = distinct filers reporting the CUSIP; 2,111 of the 2,122 reported long positions. Reported-value caution: the aggregate value ($117,886,783,158 over 235,648,323 shares) implies ≈$500.27 per share against a June 30, 2026 close of $431.46 in our price file. The aggregate sums the VALUE of every information-table row — including put and call option rows — while the share count covers long common-stock rows only, so we headline filer and share counts and label dollar values "reported."
- Insider lens: full-parse Form 4 aggregation (agg_by_ticker), record as of October 2, 2026 (311 filings). Sale and purchase counts are transaction-code counts (S and P) in non-derivative rows; grants and exercises are not counted as purchases, and one filing can contain many transaction rows. Officer purchases (officerBuyTx) are zero in the 90-day, one-year and full-record windows; officer sale transactions are 7 in 90 days, 17 in one year and 27 across the record. The site's 90-day insider aggregate (compiled as of October 8, 2026) agrees on the direction — zero purchases and the same twelve sellers — but its 90-day sale totals (1,037 transactions, $1,031,288,342.64) differ from the full-parse figures (1,102 transactions, $1,103,128,611.20) because its window ends six days later; we use the full-parse figures throughout.
- 13D/G lens: full-parse SC 13D/G aggregation and parsed filings (11 filings matching CUSIP 24703L202, 15 reporters), filings through September 11, 2026. The Silver Lake figures are the "Silver Lake Group, L.L.C." group row of each successive SC 13D/A; group rows aggregate the listed Silver Lake entities and are not summed with the individual entity rows. Michael S. Dell's percentages (46.8% and 45.7%) are quoted exactly as reported in the respective 13G/A filings; the filings' share-class bases can differ, so we do not recompute them against the share count. One Vanguard Group 13G/A (filed March 26, 2026) carries zero shares in the parse and is not used for any figure here. The aggregation's totalSharesReported field sums overlapping reporters and successive amendments and is not used.
- Congress lens: Senate PTR archive and House PTR archive as maintained on this site, combined record as of October 3, 2026. Counts are transaction counts in the aggregated member record; congressional disclosures report value ranges, so no dollar figures are used for this lens. The combined record shows zero buys and one sell; the sell is in the House aggregate (as of October 3, 2026), whose member-count field for Dell reads zero — a quirk of that aggregate — so we report transaction counts only. The Senate aggregate carries no Dell record.
- Short interest lens: FINRA Equity Short Interest files (biweekly settlement dates), collected directly from FINRA's public distribution; the Dell series covers 137 settlements from January 15, 2021 to September 15, 2026, and the February 13, 2026 peak was verified across all 137 rows. FINRA publishes each settlement about two weeks after the fact. The share-count ratio uses the fundamentals file's share count of 640,000,000 — a us-gaap shares-outstanding count as of July 31, 2026.
- Fundamentals note: our fundamentals collection carries Dell's fiscal-2026 figures — revenue $113,538,000,000, net income $5,936,000,000, assets $101,286,000,000 — for the fiscal year ended in January 2026. The fiscal second-quarter 2027 figures in the introduction are from the company's September 1, 2026 results as reported by multiple outlets (see market context sources), not from our fundamentals file. The market value of about $367.4 billion uses that file's October 6, 2026 price ($574.00) and reported share count.
- Prices: our own daily-close file for Dell through October 2, 2026 ($562.52 close, +346.9% year to date on that file; 252-session closing high $588.40 on September 17, 2026; closing low $111.07 on January 20, 2026; closes of $164.13 at March 31, 2026 and $431.46 at June 30, 2026, a second-quarter change of +162.9%). The drawdown from the 252-session closing high is −4.4% ((562.52 / 588.40) − 1). The 52-week intraday high of $595.51 (September 18, 2026) reported by outside providers is a different basis from our closing-price file, and the two are not mixed.
- Market context sources: fiscal second-quarter 2027 results (revenue $46.97 billion, +58% year over year, against a consensus of roughly $44.9 billion; non-GAAP EPS $7.04 against about $4.91 expected, +203% year over year; GAAP diluted EPS $6.34, +273%; Infrastructure Solutions Group revenue $31.8 billion, +89%; AI server orders $60.9 billion; AI-optimised server revenue $16.4 billion; AI backlog $95 billion; fiscal 2027 guidance raised to $192 billion of revenue, $25.50 of non-GAAP EPS and $74 billion of AI server revenue) — company results as reported by StockMoguls, Last10K via ad-hoc-news and MarketBeat, checked October 9, 2026; next-session gains of 15.8% and 4.8% — StockMoguls; most-searched ranking (eighth, Benzinga Pro September, first top-twelve entry in 2026) and consensus average price targets (about $560.24 in a September compilation and about $571.12 in an October 6 compilation) — Benzinga via Longbridge and MarketBeat; year-to-date gain of about 345% and the founder's one-day fortune increase — Forbes via europesays. Figures we could not confirm against two sources were left out.
- Dell is in the GetCoattail stock-page universe: Dell Technologies (DELL) stock page. Series data: dell_lens_data.csv · dell_short_interest_series.csv. Earlier audits: Oracle · Meta · IREN.
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history
- v1.0 — October 9, 2026: first publication.