GetCoattail Research — The Filing Tape #197. Knight-Swift Transportation Holdings through six filing lenses, as of the latest filings. Past patterns are not a promise of future results. For education only — not investment advice.
The Hype
Knight-Swift Transportation Holdings Inc. (KNX) sits on TipRanks' "Trending Stocks by Analyst" list, ranked by recent analyst activity, with page values dated October 23, 2026. The names ranked ahead of it on that page — Meta Platforms, Lam Research, Waste Connections, Spotify, United Rentals, Western Digital, Thermo Fisher, Procter & Gamble, Abbott Laboratories, and Tesla — have all been covered in this series already, which makes Knight-Swift the first uncovered name on the list. The page lists 8 Buy, 1 Hold, and 0 Sell ratings for it (row values dated October 22, 2026). This package cites no other news event for Knight-Swift: the attention claim rests on that trending listing plus the measured price tape, and nothing else.
The price tape behind the attention is a rise and a give-back, not a steady climb. KNX closed 2025 at $52.28, stood at $57.58 by March 31, 2026, then rose 35.2% in Q2 to $77.87 by June 30, fell to $63.59 by September 30, and closed the price file on October 2 at $66.76 — 14.3% below its June 30 close but 27.7% above its 2025 year-end close. The daily refresh (cross-source) puts the October 23 close at $61.21 — 8.3% below the October 2 close, 21.4% below June 30, and 17.1% above the 2025 year-end close. The question the filings let us ask: while the price did that, what did the tracked holders, the broad market, the company's own insiders, and the passive register actually do?
The Tape
| Lens | As of | What the filings show | Direction vs prior period |
|---|---|---|---|
| Superinvestors (13F) | Jun 30, 2026 | 2 of 147 tracked managers hold; 3,470,406 shares ($270.24M reported). Slate Path is 98.3%. | Verified cohort shares −41.0%; 0 new holders, 2 exits |
| All institutions (13F) | Jun 30, 2026 | 631 filers hold 162,627,812 shares ($12.81B reported). | Shares +12.13%; filers +129; reported value +54.02% |
| Insiders (Form 4) | Oct 2, 2026 | 0 buys, 5 sells in 90 days ($16.18M sold); 1 buy ever across the whole corpus. | No buys in 90 days or in the year; sells in every window |
| Congress | Oct 3, 2026 | No trades in the combined file; no House row, no Senate row. | None (empty lens, not missing data) |
| 13D/G | Aug 6, 2026 | All passive: 4 SC 13G + 15 SC 13G/A; FMR LLC at 10.0% max. | No activist filing in the parsed set |
| Short interest | Sep 15, 2026 | 13,060,742 shares short, 8.03% of shares outstanding; 3.96 days to cover. | Series peak; +18.48% from prior settlement; +52.0% vs June; +98.0% year over year |
Chart: Knight-Swift through six filing lenses — who is actually there?
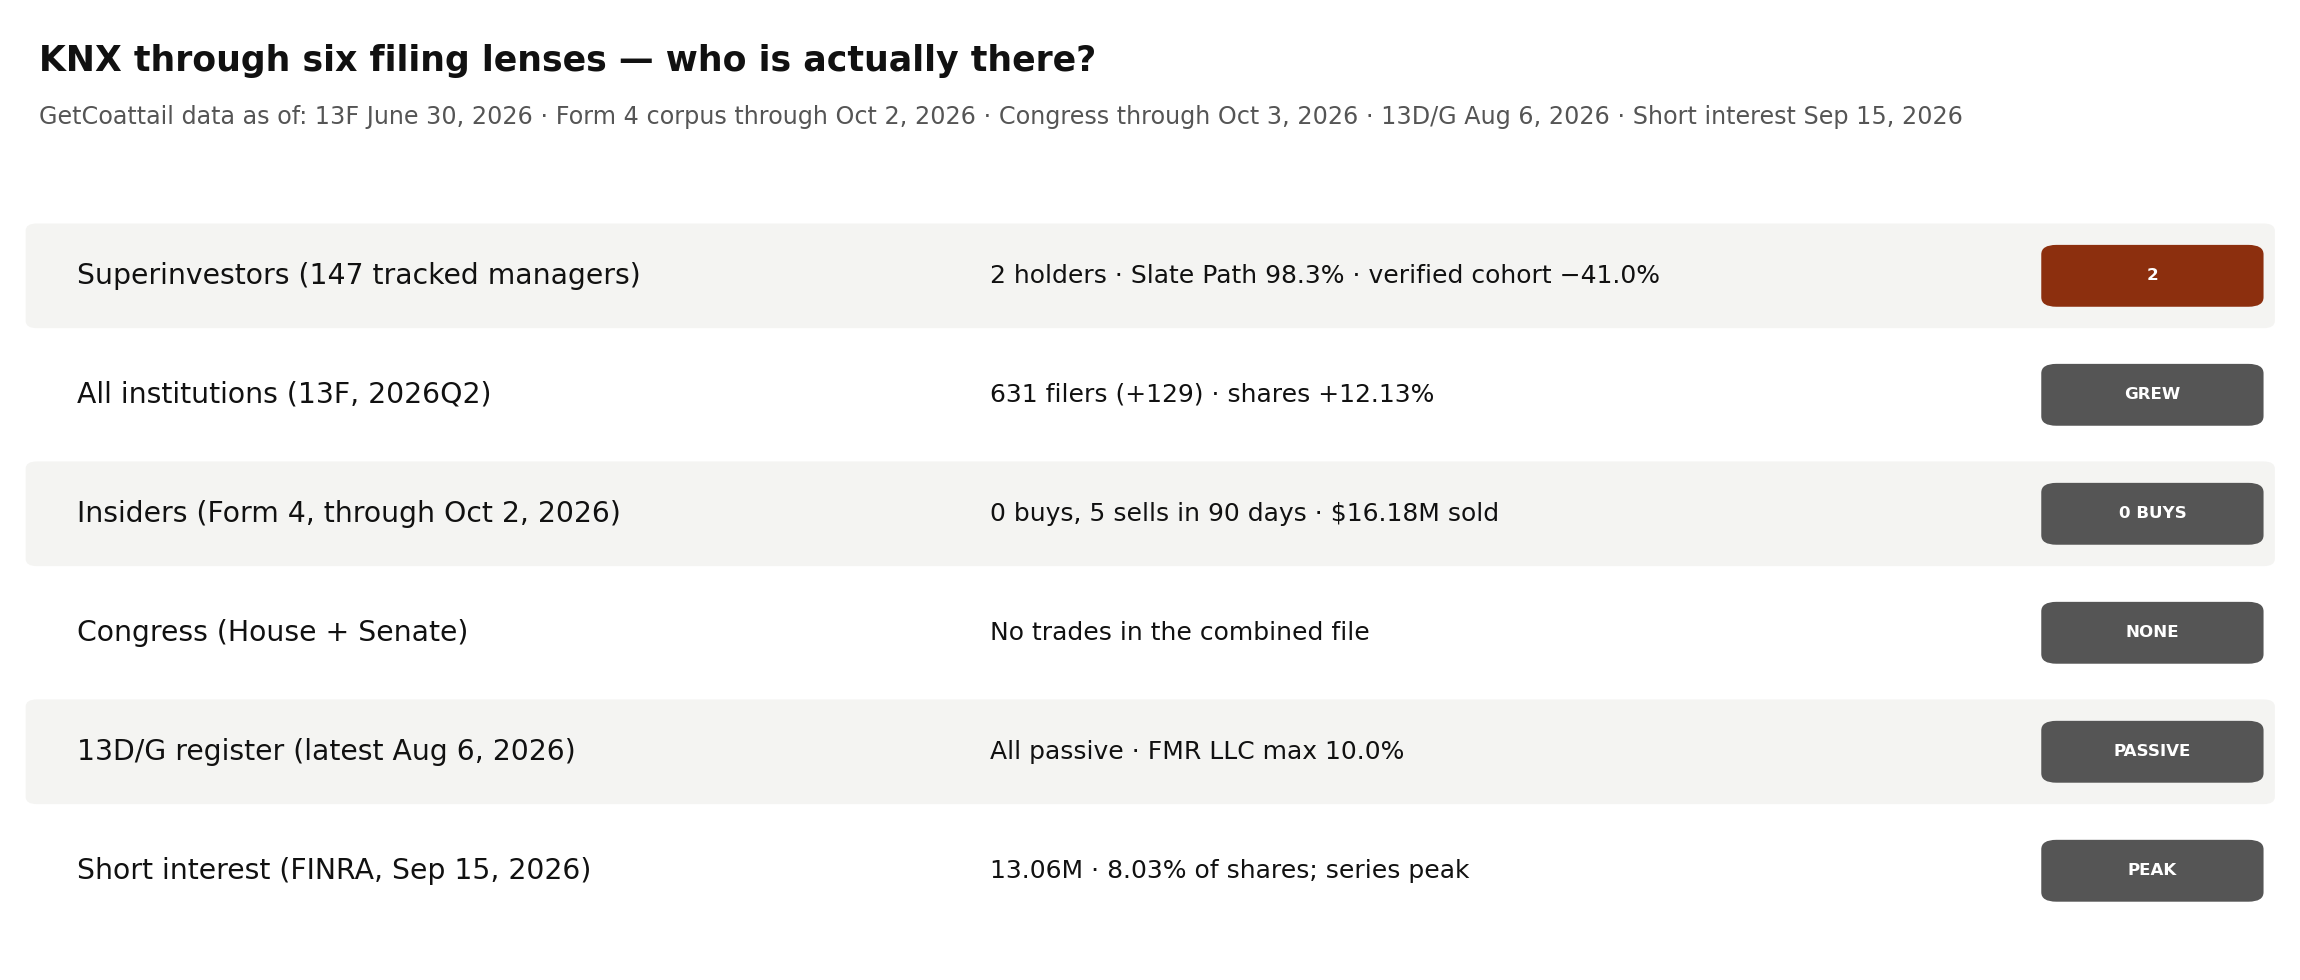
Superinvestors. The tracked register for Knight-Swift is small — two holders, both cutting, and one of them is nearly the whole register. Two of 147 tracked managers hold 3,470,406 common shares — $270,240,515 reported — and the largest holder is 98.3% of it. Slate Path Capital holds 3,411,000 shares at 3.68% of its portfolio, labelled DECREASED in Q2. The label recomputes exactly against a verified Q1 pair of 4,618,200 shares, so the −26.1% figure is real. Richard Pzena's Pzena Investment Management holds 59,406 shares at 0.01% of its portfolio, labelled DECREASED in Q2. That label also recomputes exactly, against a verified Q1 pair of 1,259,811 shares — so the −95.3% figure is a near-exit from a large Q1 base, not a rounding effect. There are no new holders. Two managers exited: D1 Capital Partners (5,491,563 shares, previous reported value $316,204,198) and Lee Ainslie's Maverick Capital (10,609 shares, previous reported value $610,866), together 5,502,172 shares. Note the scale: D1's exited position alone is 1.58 times the entire June cohort. No September early filer holds KNX, so the June cohort is the whole tracked story. The verified continuing change reconciles under both pairing methods: the 2 continuing holders held 5,878,011 shares in Q1, so the cohort fell 2,407,605 shares, or 41.0%, in Q2. Both pipeline registers reconcile exactly, residual zero in each quarter (Q1: 11,380,183 shares; Q2: 3,470,406 shares). The cohort's implied price matches the June 30 close exactly ($77.87). The cohort is 2.13% of the full market's reported Knight-Swift shares and 2.13% of shares outstanding — a small footprint that shrank fast, led by a near-exit and a large exit.
All institutions. The broad market disagrees with the tracked cohort, and it disagrees on a much larger scale. Filers rose by 129 to 631, of which 629 are long, while reported shares rose 12.13% (+17,593,071 shares to 162,627,812). Reported value rose 54.02% to $12.81 billion — shares up and value up together, and value up much more, because the June 30 close ($77.87) sits well above the March 31 close ($57.58). Underneath, 588 filers entered and 459 exited, net +129. Excluding the tracked cohort, other institutions hold 159,157,406 shares — so the broad market's Q2 share growth (+17.59 million shares) dwarfs the tracked cohort's verified decline (−2.41 million shares), and the two moved in opposite directions.
Insiders. This lens needs careful wording, because the all-time record and the recent windows say different things. In the 90 days to October 2, 2026, insiders bought nothing and sold $16,183,489.69 worth of stock: 5 filings, 0 buy transactions, 5 sell transactions, 224,954 shares sold, by 3 sellers, 3 of them officer sells. In the year to October 2, 2026: 52 filings, 0 buys, 17 sells, 390,376 shares sold for $25,694,626.43, by 9 sellers, 15 of them officer sells. Across the whole corpus, there is exactly 1 buy transaction totalling 5,000 shares ($226,830.00), by a single buyer, Douglas L. Col — a purchase of 5,000 shares at $45.366 on March 13, 2025, recorded as a non-officer transaction in the parsed record — and 19 sells totalling 394,996 shares for $25,895,939.70. The scan for issuer CIK 1492691 (95 files, all KNX, January 8, 2025 to September 2, 2026) matches the aggregate exactly, and the site insider aggregate matches the 90-day window exactly. The article therefore never says insiders "never bought": zero buys in the 90 days and in the year, exactly 1 buy across the whole corpus. One seller dominates the recent window: Dove Reid accounts for 219,154 of the 224,954 shares sold in the 90 days (50,000 shares on July 31, 2026, and 42,290 plus 126,864 shares in filings dated August 14, 2026). Implied sell prices sit inside the price-file range in every window ($71.94 in the 90 days against a $63.55–$77.32 range; $65.82 in the year against a $41.41–$82.45 range).
Congress. This lens is empty, and the emptiness is itself the finding. There is no KNX row in the combined aggregate, no House row, and no Senate row, and the member file holds 0 KNX rows (all as of October 3, 2026). That is a "no reported trades" lens, not a missing-data lens: all three aggregates were checked and return no row. No amounts are summed, because there is no member trade to sum. Congress findings are member-disclosure aggregates, not Form 4 insider transactions, and are never added to insider totals.
13D/G. The control register is entirely passive — and it has never held an activist filing in the parsed set. It holds 19 filings: 4 Schedule 13G and 15 Schedule 13G/A amendments, with no Schedule 13D form at all. The largest reported percentage is 10.0% for FMR LLC (16,304,678.25 shares, event October 31, 2025, filed November 7, 2025). The latest filing, August 6, 2026, is FMR LLC and Abigail P. Johnson at 5.0% (8,061,152.80 shares, event June 30, 2026). The aggregate matches the parsed set exactly. Filing percentages are as reported; denominators differ by filing date, and jointly-reported positions are counted once per reporting entity, so no cross-date total is quoted as a holding.
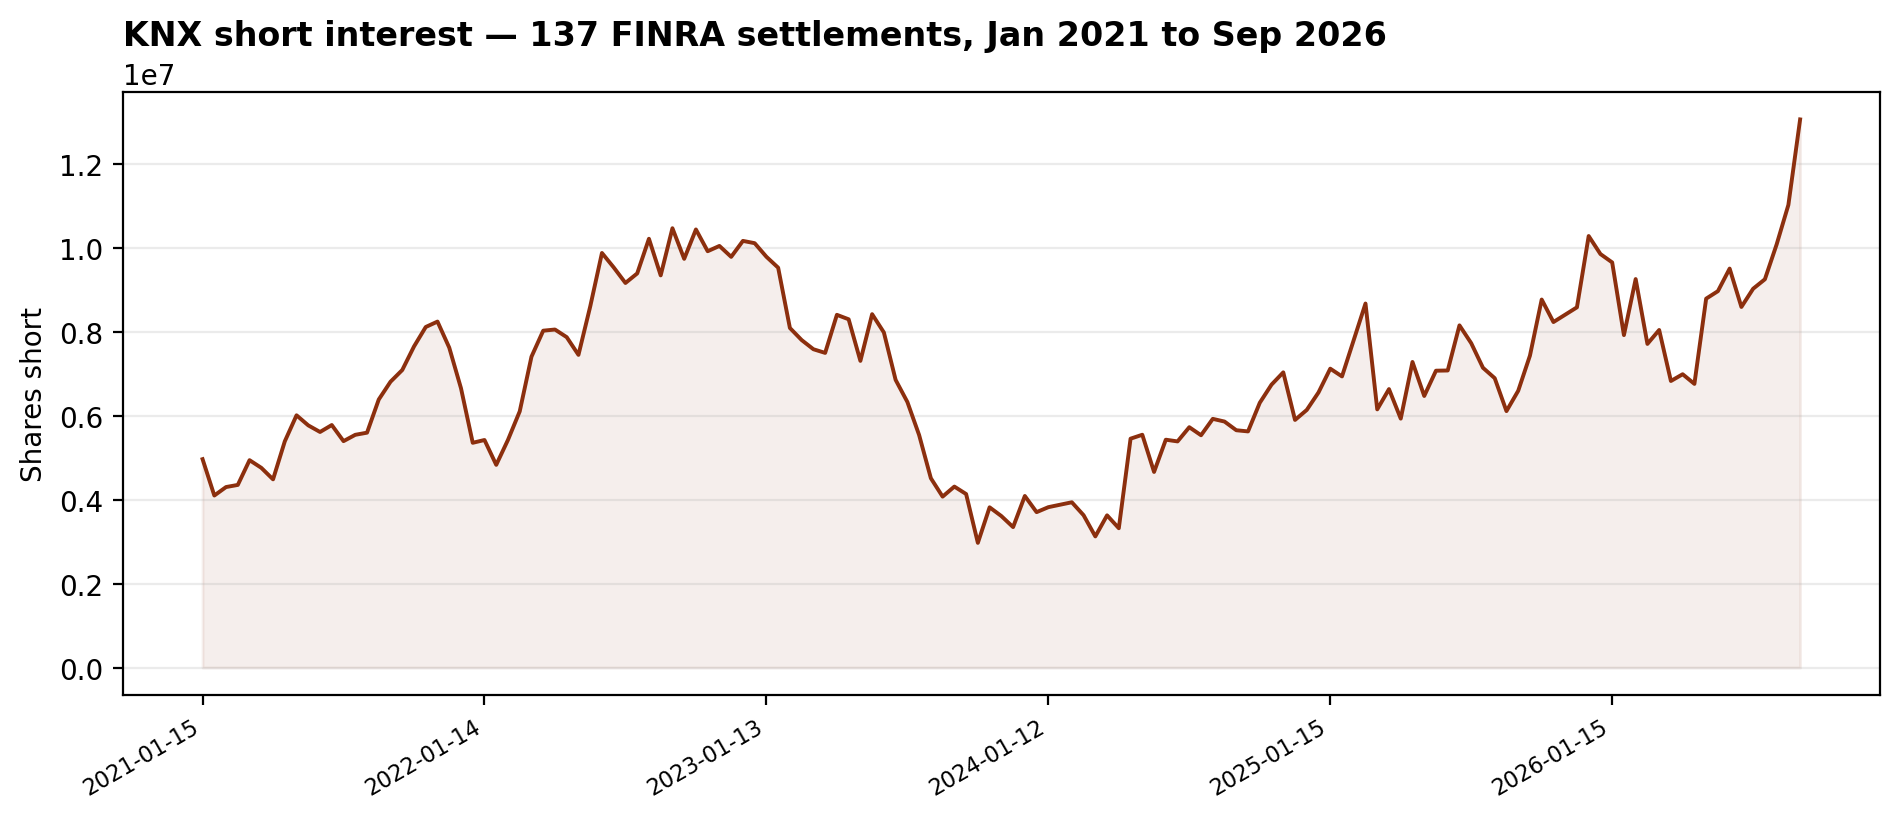
Short interest. The bear trade is building, and it just set the series high. FINRA short interest stood at 13,060,742 shares at September 15, 2026, with 3.96 days to cover and 8.03% of the 162,611,000 shares outstanding (a 2025 weighted-average count — the ratio inherits that basis). That latest settlement is the series peak across all 137 settlements: it is 18.48% above the prior settlement (11,023,614 at August 31), 52.0% above June 30 (8,592,850), and 98.0% above the year-ago figure (6,595,285 at September 15, 2025). The last six settlements rise every step after June: 8,592,850 (June 30), 9,026,915 (July 15), 9,251,992 (July 31), 10,082,190 (August 14), 11,023,614 (August 31), 13,060,742 (September 15). The series low is 2,971,973 (October 13, 2023). No step over 2× and no step under 0.5× appears across 137 settlements. Two rows carry a revision flag; no row carries a stock-split flag.
Chart: KNX short interest — 137 FINRA settlements, January 2021 to September 2026.
Fundamentals context. Shares outstanding are 162,611,000 on a 2025 weighted-average basis (the record's own fallback where a point-in-time series was missing), revenue is $7,469,689,000 and net income is $65,946,000, both for FY2025, and assets are $11,955,436,000 for FY2025. The recorded market capitalisation is $10,509,548,483, on the record's own price_close ($64.63 as of October 6, 2026), not the October 23 close. The company's SIC classification is trucking.
The Gap
The attention and the filing tape point in different directions, and the tape itself is split. A trending listing with 8 Buy ratings puts Knight-Swift in front of readers while the price has fallen 21.4% from its June 30 close to the October 23 fresh close — and the filings show the tracked cohort cutting 41.0% in Q2 while the broad market added 12.13% in shares. The gap is inside the tape: the two tracked holders both cut, one nearly exited, and a third large holder (D1) left entirely, yet 588 new filers entered the broad register; the company's own insiders sold $16.18 million in 90 days without buying a share, and have bought exactly once in the parsed history; Congress shows nothing at all; the control register holds no activist filing; and short interest has risen every settlement since June to a series peak. In short: tracked money left while the broad market arrived, insiders sold, nobody in Congress traded, and the bear position is building, not easing.
What Would Change the Picture
Nothing above is a recommendation. It is a record. What would change it:
- 1. Q3 13F season (filings due by November 16, 2026). Watch whether Slate Path holds, adds to, or trims its 3,411,000-share position after a 26.1% cut, whether Pzena's remaining 59,406 shares survive or exit after a 95.3% cut, whether D1 returns after exiting 5,491,563 shares, and whether the verified cohort's 41.0% Q2 decline extends, holds, or reverses.
- 2. A first insider buy in the Form 4 corpus after October 2, 2026 — any buy transaction, and especially an officer buy — would break a run of zero buys in the 90 days and in the year; continued selling at the 90-day pace ($16.18 million) would extend it.
- 3. A first congressional trade row for KNX — any attributed member purchase or sale, in either chamber — would replace a lens that currently holds no row at all.
- 4. A first Schedule 13D filing, a new passive reporter above 5%, or a new Schedule 13G/A moving FMR above or below 5.0% would change a control register that currently holds only passive filings and no activist filing.
- 5. Short-interest direction. A fall back toward the June 30 level of 8,592,850 — or a further rise above the September 15 peak of 13,060,742 — would each tell a different story about the bear position that has risen every settlement since June.
As-of & Limits
| Lens | As of | Limit or note |
|---|---|---|
| Superinvestors (13F) | Jun 30, 2026 | 13F figures are as of June 30, 2026, the quarter-end. Funds have up to 45 days after quarter-end to file, so this is the most recent complete picture — and it is always a lagging one. Common stock only (CUSIP 499049104); no option rows, no second class in the tracked file. Both Q1→Q2 changes verify exactly under both pairing methods. Both pipeline registers reconcile with residual zero. Pzena's −95.3% is a verified near-exit from a 1,259,811-share Q1 base. D1's exited 5,491,563 shares exceed the entire June cohort. No September early filer holds KNX. |
| All institutions (13F) | Jun 30, 2026 | Reported value includes option rows by definition; implied price ($78.79) is not a price check. Value rose much more than shares because the June close sits well above the March close. |
| Insiders (Form 4) | Oct 2, 2026 | Zero buys in the 90 days and in the year to October 2, 2026; exactly 1 buy totalling 5,000 shares across the whole corpus (Douglas L. Col, March 13, 2025, non-officer in the parsed record). Officer buy transactions are 0 in every window. The scan (95 files, issuer CIK 1492691) matches the aggregate exactly. |
| Congress | Oct 3, 2026 | Empty-lens finding: no row in the combined, House, or Senate aggregates and 0 member-file rows. The Senate file itself is as of October 1, 2026; the combined and House files are as of October 3, 2026. This is "no reported trades in the file", not "Congress never traded KNX" and not missing data. Congress findings are member-disclosure aggregates, not Form 4 insider transactions, and are never added to insider totals. |
| 13D/G | Aug 6, 2026 | All-passive register: 4 SC 13G + 15 SC 13G/A, 0 SC 13D. Filing percentages are as reported in each filing; denominators differ by filing date and are not recomputed. Jointly-reported positions are counted once per reporting entity in parsed totals, so no cross-date total is quoted as a holding. |
| Short interest | Sep 15, 2026 | Shares-outstanding count is a 2025 weighted-average fallback (the record's own substitute for a missing point-in-time series); the 8.03% ratio inherits that basis. The series has no step over 2× and no step under 0.5× — read the level and the drift, not a single step. |
| Prices | Oct 23, 2026 (fresh close) | Price file ends Oct 2, 2026; the Oct 23 close ($61.21) and moves derived from it are cross-source (chart_stats) and labelled as such. The price file's splits field is empty and no split adjustment is applied. The chart_stats 52-week-high field ($82.86) is a different window from the price file's 252-day high ($82.45) and is quoted as its own field. |
| Fundamentals | FY2025 | Recorded market capitalisation uses the record's own price_close ($64.63 as of Oct 6, 2026), not the Oct 23 close, and is quoted only as the record's figure. Shares outstanding are a 2025 weighted-average fallback. |
| Hype source | Oct 26, 2026 (TipRanks trending list) | Listing only (trending by analyst activity, page values dated October 23, 2026; KNX row values dated October 22, 2026); no other news event is cited for Knight-Swift in this article. Price moves are measured from the price file and chart_stats. |
Methodology & disclaimer: 13F holdings are long common shares unless stated; reported values include option rows for the all-institutions lens by definition. Short interest is FINRA twice-monthly settlements. Trading costs and taxes are not reflected in any figure. Past patterns are not a promise of future results. For education only — not investment advice.
This article describes filings and market data for education. It is not investment advice. Data: SEC EDGAR 13F (as of June 30, 2026, filed within 45 days), Form 4 corpus checked through October 2, 2026 (95 parsed files for issuer CIK 1492691), House/Senate disclosures through October 3, 2026, SC 13D/G parsed register through August 6, 2026, FINRA short interest at September 15, 2026 settlement. 13F covers long positions of $100M+ managers only and is always a lagging picture. Trading costs and taxes are not reflected.
Related research: Twenty-Two of 147: Dodge & Cox Raised Its Thermo Fisher Stake 11,767.4% in Q2 — While Insiders Sold $61.6 Million in 90 Days · One of 147: The Only Superinvestor in J.B. Hunt Holds Just 4,032 Shares. Its Insiders Filed Nothing in 90 Days. · Track the tape on Knight-Swift's stock page and the 13F filing season hub.
Revision history: v1.0 — October 26, 2026. Initial publication. Signals and lens aggregates: knx_lens_data.csv. Short-interest series: knx_short_interest_series.csv.
Past patterns are not a promise of future results. For education only — not investment advice.