GetCoattail Research — The Filing Tape #169. Nutanix is on Zacks' most-searched list after beating earnings and EPS estimates three quarters running, with the stock up 34.1% in Q2 and 39.9% year to date. The filings show four tracked holders of 147 — two of them own 93.5% of the tracked stake, the cohort added a verified 7.4% into the rally, the broad market reported 25.66% more shares, short interest unwound 56.6% from its July peak, and in the full Form 4 record not one insider has ever bought a share.
① The Hype
Nutanix (NTNX) made Zacks.com's list of the most searched stocks on October 22, 2026. The attention is easy to understand. The enterprise cloud platform company just posted a quarter with revenue of $757.08 million, up 15.9% year over year and 2.6% above the Zacks consensus, and EPS of $0.60 versus $0.37 a year earlier — a 25% surprise. It has beaten consensus EPS three of the last four quarters. Consensus now expects $761.76 million in sales (+13.6%) and $0.60 in EPS (+46.3%) for the current quarter, $3.21 billion (+12.4%) for the current fiscal year, and $2.64 in EPS (+14.2%) the year after — and Zacks rates the stock #2 (Buy).
The price has followed the beats. Nutanix rose 34.1% in the second quarter of 2026 ($38.01 to $50.96) and is up 39.9% year to date through October 2, 2026, closing at $72.29 — 6.0% below its 52-week high of $76.92. Over the past month the stock is up just 0.6%, about flat against the Zacks S&P 500 composite — so the search traffic is about the earnings story, not a fresh price spike. One caution from the same source: Zacks' Value Style Score gives NTNX a D, meaning it trades at a premium to its peers.
That is the story the market is reading. The filings tell their own version.
② The Tape
| Lens | As of | What the filings show | Direction vs prior period |
|---|---|---|---|
| Superinvestors (13F) | Jun 30, 2026 | 4 of 147 tracked funds hold 13,235,281 shares, $674.5M reported; Generation 50.7%, Jericho 42.8% | Verified continuing cohort +7.4% |
| All institutions (13F) | Jun 30, 2026 | 570 filers, 262,102,864 shares | +42 filers; shares +25.66% |
| Insiders (Form 4) | Through Oct 2, 2026 | 0 buys in the full parsed record; 2 officer sells in 90 days ($7.43M) | Sells only — no buying window |
| Congress | Through Oct 3, 2026 | No transactions in either chamber | — |
| 13D / 13G | Through Jul 31, 2026 | BlackRock 10.4% passive (Oct 2025); latest Vanguard Portfolio Mgmt 4.97% | Latest print is passive |
| Short interest (FINRA) | Sep 15, 2026 | 11,355,595 shares; 4.2% of shares outstanding | −56.6% from Jul 15 peak |
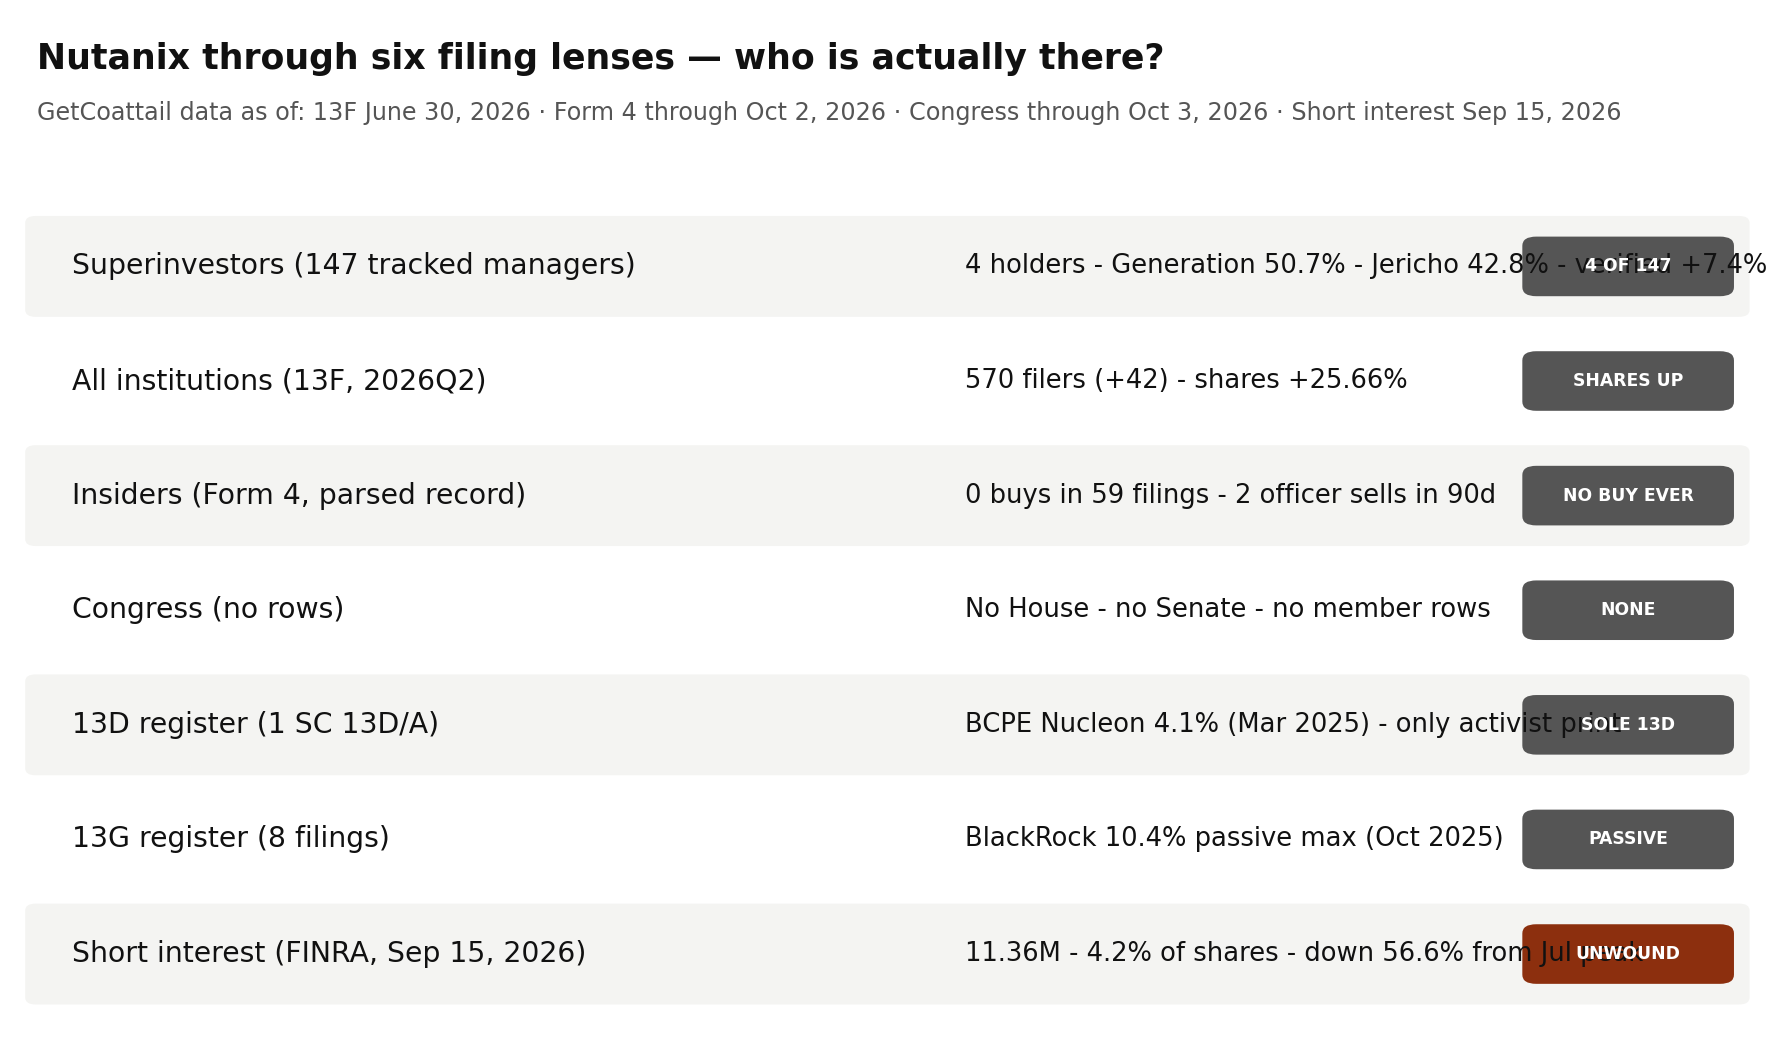
Superinvestors. Four of 147 tracked funds held Nutanix common stock at June 30, 2026: 13,235,281 shares, $674.5 million reported, equal to 5.05% of all 13F-reported Nutanix shares. The register is a two-name show. Generation Investment Management holds 6,709,160 shares (50.7% of the cohort, a 3.32% portfolio weight) and cut 794,661 shares (−10.6%) in Q2. Jericho Capital Asset Management holds 5,668,014 shares (42.8% of the cohort, a 2.39% weight) and added 1,747,518 shares (+44.6%). The remaining two — Terry Smith's Fundsmith (538,281 shares, −39,111, −6.8%) and Aequim Alternative Investments (319,826 shares, unchanged) — are rounding error beside them: the top two names are 93.5% of the tracked register.
Every one of the four held the stock in Q1 too: no exits, no new holders, no option rows. The verified continuing cohort grew 7.4% (12,321,535 to 13,235,281 shares — a net add of 913,746), confirmed by two independent pairing methods with a register that reconciles to zero residual in both quarters. So the cohort's net add is one holder's story: Jericho's +1.75 million against Generation's −0.79 million and Fundsmith's −0.04 million. Howard Marks's Oaktree shows a 2.2-million-share convertible-bond row — debt, not common stock, and excluded from this cohort. The cohort's implied price, $50.96, matches the June 30 close exactly. With the price up 34.1% in the quarter, the cohort added shares into strength — but really only one name did.
All institutions. The broad 13F market was far more enthusiastic. Filers rose to 570 (+42, +7.95%) and reported shares jumped 25.66% to 262,102,864 — a net add of 53.53 million shares; reported value rose 64.96% to $13.16 billion (value includes option rows, so shares are the cleaner signal). The single-CUSIP fixture check matches exactly. Put differently: the superinvestor cohort is 5.05% of reported 13F shares, and the other 94.95% grew more than three times faster than the cohort in the same quarter.
Insiders. Across the entire parsed Form 4 record — 59 filings from January 15, 2025 to September 25, 2026 — there is not one buy transaction. Zero buys in every window: 90 days, one year, all. Against that: 25 sell transactions from 9 sellers totaling 17,007,971 shares and $1.28 billion. In the last 90 days, 2 officer sells totaling 107,917 shares and $7.43 million; in the last year, 6 officer sells totaling 301,883 shares and $21.16 million. The parsed scan matches the merged aggregate exactly, and our site's insider row matches the 90-day window to the dollar.
Congress. No rows in the combined, House, Senate, or member files. No member of Congress has disclosed a Nutanix trade in the window.
13D / 13G. Nine filings, all passive except one. BlackRock's 10.4% (27,876,671 shares, filed October 2, 2025) is the register maximum — a passive print, not a campaign. The only activist-style print ever is BCPE Nucleon's 4.1% SC 13D/A from March 2025 (10,960,935 shares). The latest filing is Vanguard Portfolio Management at 4.97% (13,440,444 shares, filed July 31, 2026), a step down from its 5.3% print in April; AQR's 5.71% (15,155,213 shares, filed May 15, 2026) is the largest passive print of 2026. The aggregate file matches the parsed filings exactly.
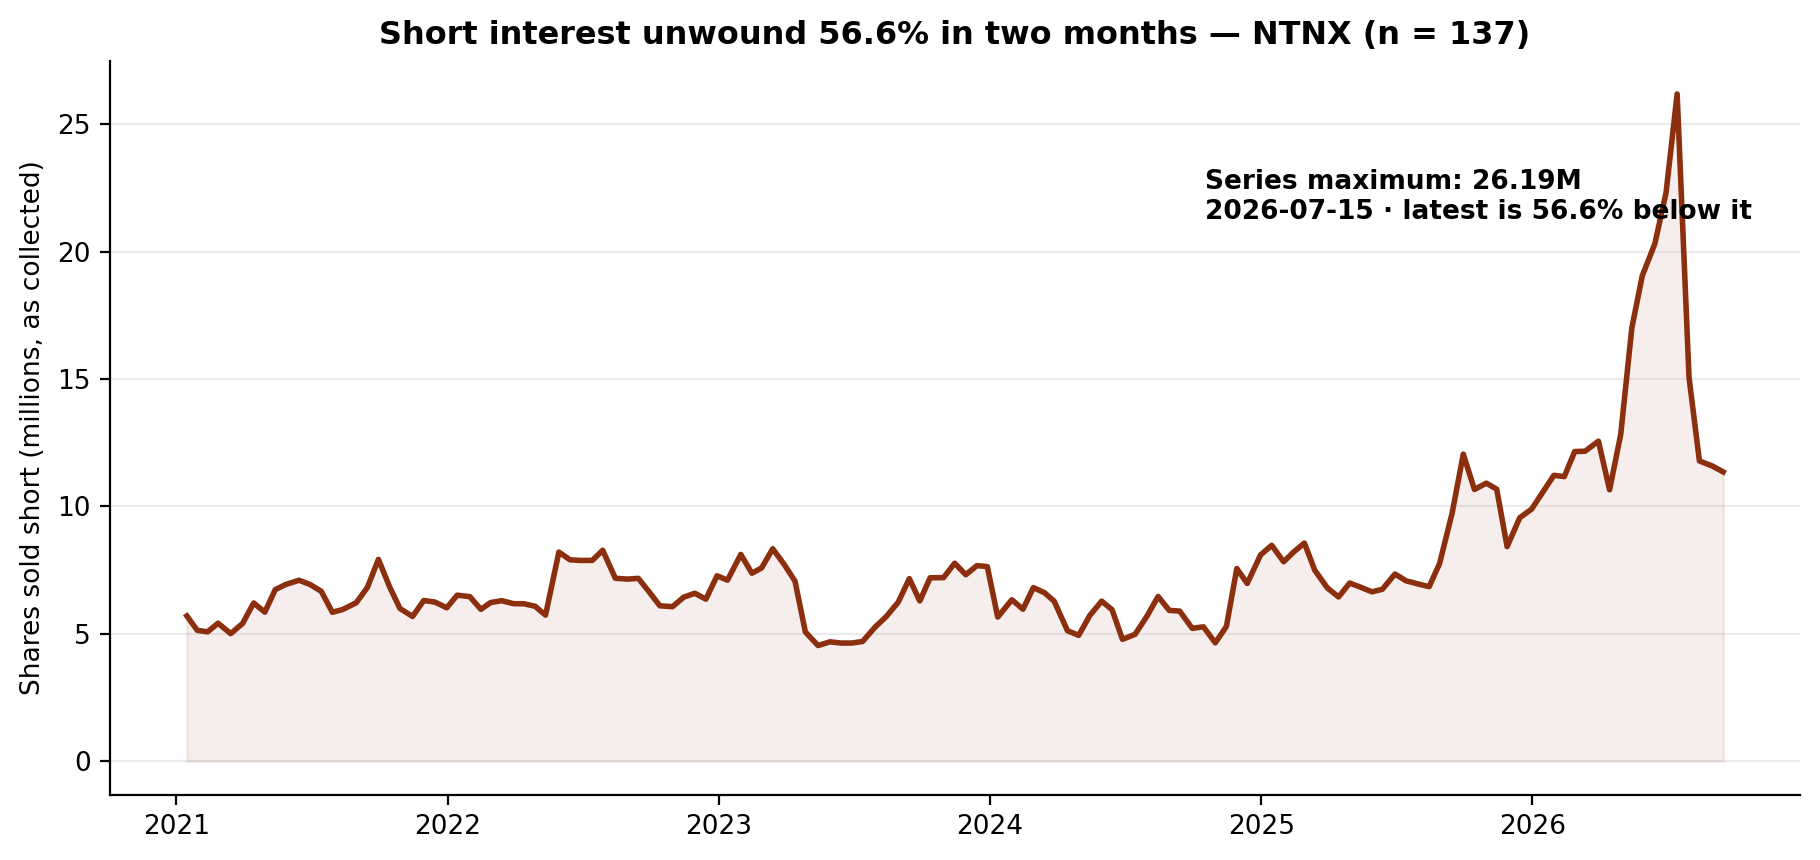
Short interest. This is where the tape gets dramatic. Short interest peaked at 26,187,342 shares on July 15, 2026, then collapsed: 22,301,162 (Jun 30) → 26,187,342 (Jul 15, the maximum) → 15,061,103 (Jul 31) → 11,784,644 (Aug 14) → 11,590,255 (Aug 31) → 11,355,595 (Sep 15). That is a 56.6% unwind in two months, to 4.2% of shares outstanding. Versus the June 30 settlement it is down 49.1%; versus a year ago it is still up 16.6%. Days to cover stand at 5.98.
③ The Gap
The market story is earnings beats and a Zacks #2 rating. The filings say: institutions piled in (+25.66% of reported shares in Q2), shorts covered en masse (−56.6% from the July peak), and two superinvestors own 93.5% of the tracked register — while the people who run the company have never bought a share in the record we hold.
Note the sequencing. The Q2 price rally (+34.1%) coincided with the superinvestor cohort adding 7.4% and the full market adding 25.66% — but the heaviest short covering came after quarter-end, in July and August, as the stock pushed toward its 52-week high. We don't know who covered; the FINRA file records shares, not names. What we can say is that the record shows the bear case unwinding fast while insider conviction, measured in open-market buys, is literally zero.
One plausible reading is that this is simply how software-company insider tables look: compensation-driven selling with no open-market buying, against institutions that buy the earnings story. The tape doesn't say that's wrong. It does say the buying enthusiasm is entirely external — and that the superinvestor "consensus" is really one fund adding while the largest holder trims. Zacks' own Value grade of D (premium to peers) sits oddly next to the #2 Buy rating; the filings side with the cautious half of that pair: the price is 6.0% off its 52-week high, the shorts just covered, and nobody on the inside has put their own money in.
④ What Would Change the Picture
Nothing above is a recommendation. It is a record. The next filing cycles will rewrite that record one row at a time — here is what would change the picture, all checkable in future filings:
- 1. The Q3 13F season (deadline November 16, 2026). Does Jericho keep adding after its 44.6% raise? Does Generation keep trimming? Does a fifth tracked fund appear — or does the register shrink back to three?
- 2. A first insider buy. Any open-market purchase in a future Form 4 would break a zero that has held across 59 filings. The sellers are officers; watch whether a buyer ever appears.
- 3. Short interest turning. The unwind stopped at 11.36 million shares. A renewed build — especially back toward the 26.2 million July peak — would signal the bear case is rearming.
- 4. A new 13D. Only one activist-style print exists (BCPE Nucleon, 4.1%, March 2025). A fresh SC 13D would change the character of the register.
- 5. Congressional trades. There are none now; any disclosed trade by a member would be the first data point in an empty lens.
⑤ As-of & Limits
| Lens | As of |
|---|---|
| Superinvestors (13F) | Jun 30, 2026 (13F figures are as of the quarter-end; funds have up to 45 days after quarter-end to file, so this is the most recent complete picture — and it is always a lagging one) |
| All institutions (13F) | Jun 30, 2026 (same lag) |
| Insiders (Form 4) | Filings through Oct 2, 2026 (parsed record from Jan 15, 2025) |
| Congress | Through Oct 1–3, 2026 |
| 13D / 13G | Filings through Jul 31, 2026 |
| Short interest (FINRA) | Settlements through Sep 15, 2026 |
| Prices | Through Oct 2, 2026 (our file) |
No lens is blank for NTNX. The 13F lenses lag by design; the insider zero is a property of the parsed record (59 filings), not of all time. Reported 13F values are as filed and include option rows in the full-market total; share counts are the primary signal.
Methodology and data notes
- As-of & limits: The lenses rest on different clocks, none live: 13F is a June 30, 2026 snapshot published up to 45 days later; Form 4 windows run through October 2, 2026; Congress aggregates run through October 3, 2026 (Senate through October 1, 2026); 13D/G through July 31, 2026; short interest through September 15, 2026; the price file ends October 2, 2026. Limits specific to this audit. First, the tracked cohort is four managers, with 93.5% of its shares in two names — so the verified +7.4% is Jericho's +1,747,518 shares against Generation's −794,661 and Fundsmith's −39,111, not a broad cohort move. Second, Nutanix common stock carries a single CUSIP (67059N108), and the full-market by-CUSIP row matches the by-ticker aggregate on every field — holders, long holders, shares, reported value, prior holders and prior reported value — so no CUSIP blending question arises. Third, the tracked change labels are verified, not taken on trust: all four continuing positions were verified by two methods that agree — a total-value prefix pass and accession identity plus CUSIP-overlap pairing — with each label recomputing exactly from share counts; there were no NEW labels to audit and no exits. No September early filer holds this name. The registers reconcile with no remainder: the March 31 register equals the verified continuing holders' 12,321,535 shares (no exits); the June 30 register equals the June cohort's 13,235,281 shares exactly (all common stock, no option rows). The Oaktree row sits on a convertible-bond CUSIP (67059NAH1) and is excluded from the common-stock register. Fourth, the June cohort's implied price is $50.96 against the June 30 close of $50.96 (0.00%). Fifth, the full-market aggregate implies $50.21 against the $50.96 close (−1.46%): the aggregate is a reported sum that includes option rows, so its implied price need not equal the close; this audit uses filer counts and share counts as this lens's primary measures and reports the value as reported only. Sixth, the insider lens rests on a single aggregate bucket — this issuer's filings sit under one symbol spelling, "NTNX", with no case split — cross-checked against a row-level scan of all 59 parsed filings for the issuer (CIK 1618732): filing counts, transaction counts, share counts, officer-row counts and values reproduce exactly in every window, and no accession appears under more than one symbol spelling. Every insider implied-price check that applies passes: the 90-day implied sale price of $68.86, the one-year implied sale price of $70.08 and the full-record implied sale price of $75.17 each sit inside their filing-window close ranges; there are no purchases to imply a buy price from. Form 4 windows in this audit are filing-date windows. Seventh, the congressional lens is reported across four files: the combined aggregate, the House aggregate, the Senate aggregate and the member files — all carry no row for this ticker, and that absence is reported, not interpreted. Eighth, the 5% register's maximum print needs its date in full: BlackRock's SC 13G/A (filed October 2, 2025) prints 27,876,671 shares at 10.4% as of September 30, 2025 — passive paper, a year old. The parsed totals match the aggregates exactly, and each print is reported individually in the text. Ninth, the short-interest series holds 137 settlements beginning January 15, 2021, so its maximum and minimum describe that span only. Within it, no settlement steps to 2x or more of the prior settlement and none steps to one-half or less, so the series carries no discontinuity on this measure. No row carries a split flag; one row (June 15, 2021, 7,102,782 shares) carries a FINRA revision flag. The issuer-name field reads "Nutanix, Inc. Class A Common S" at all 137 settlements, on a single market class (NNM) throughout. The share count behind the 4.2% figure is 270,570,179 shares in our fundamentals file (a measured period-end count), not a float estimate. Our price file records no split factor for this name. The Zacks figures in The Hype — the most-searched listing, the +0.6% past-month return, the industry and style scores, the Rank #2, the reported and consensus earnings figures — are that outlet's published figures, cited as such, not blended into file-based calculations.
- Market context sources: Zacks.com, October 22, 2026 ("Here is What to Know Beyond Why Nutanix (NTNX) is a Trending Stock": most-searched list; +0.6% past-month return vs Zacks S&P 500 composite "no change"; Computers - IT Services industry +8%; Zacks Rank #2 (Buy); Value Style Score D (premium to peers); last reported quarter revenue $757.08M (+15.9% y/y, +2.6% surprise), EPS $0.60 vs $0.37 (+25% surprise); beat consensus EPS 3 of last 4 quarters; consensus current quarter sales $761.76M (+13.6%), EPS $0.60 (+46.3% y/y), current FY $3.21B (+12.4%), next FY EPS $2.64 (+14.2%)).
- Nutanix is in the GetCoattail stock-page universe: Nutanix (NTNX) stock page. Series data: ntnx_lens_data.csv · ntnx_short_interest_series.csv. Earlier audits: JetBlue · GE Vernova.
Past patterns are not a promise of future results. For education only — not investment advice.
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history: v1.0 — October 23, 2026: first publication.