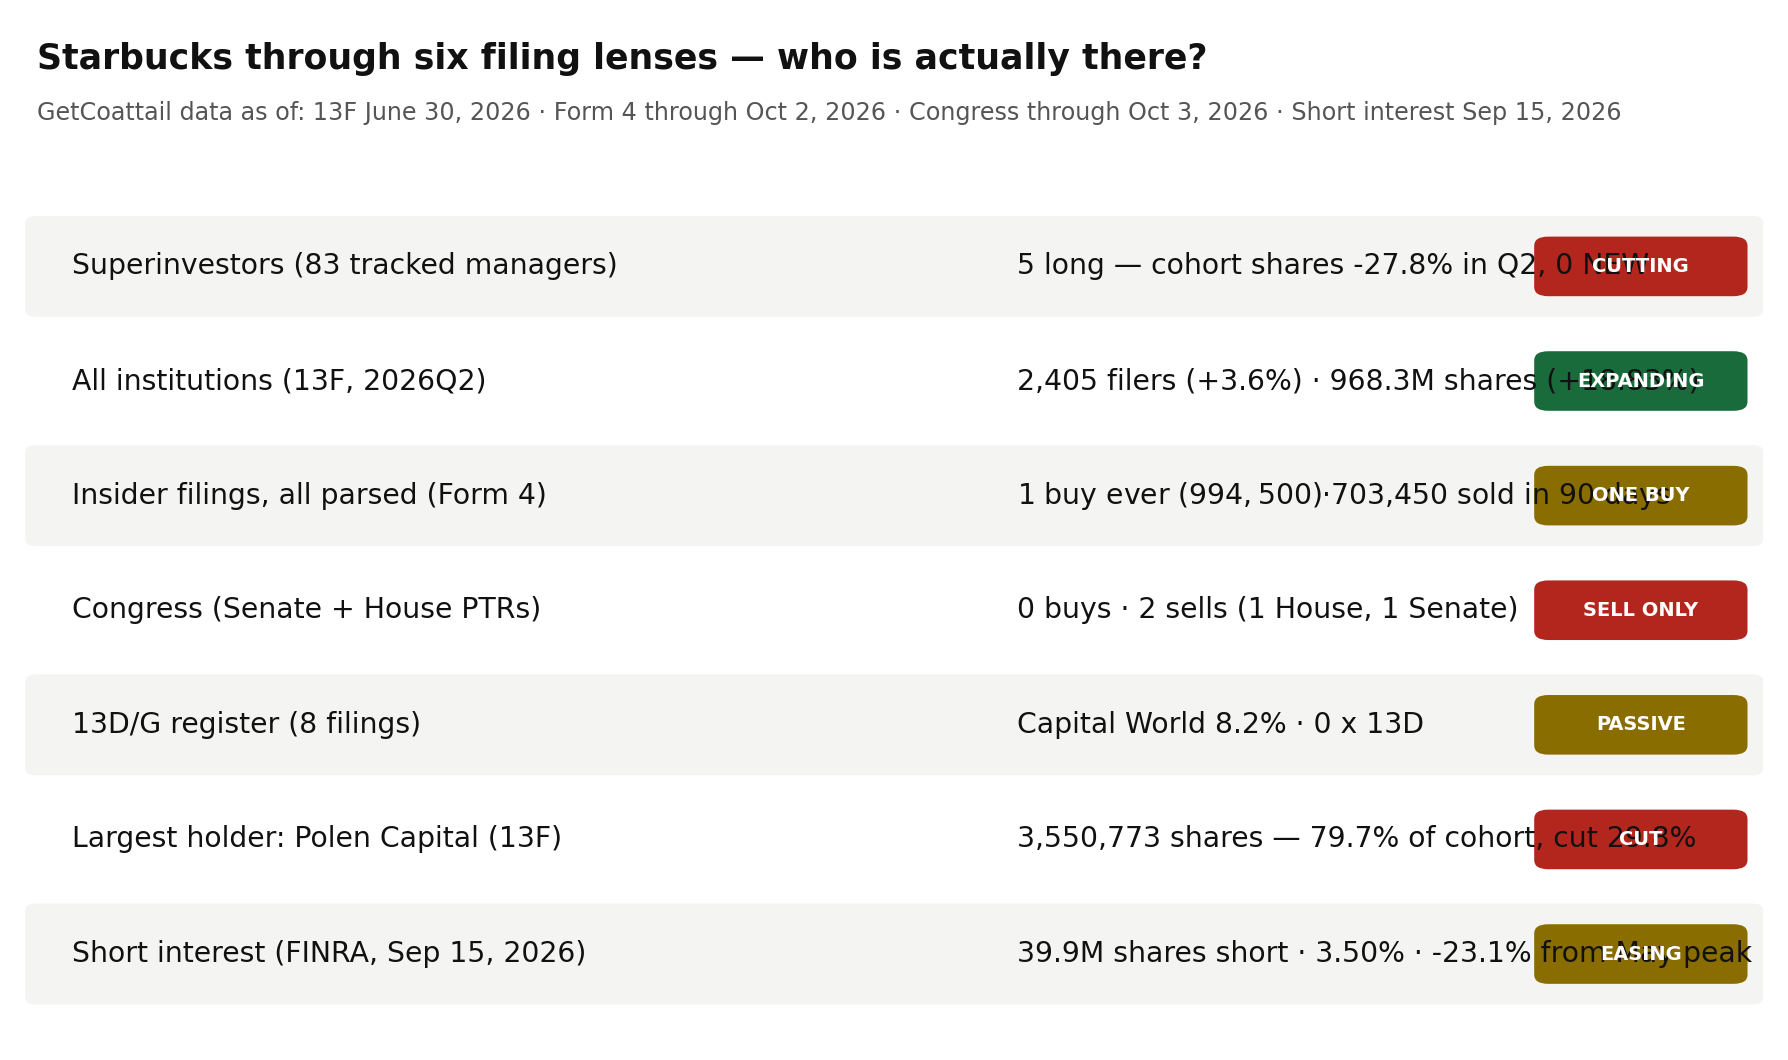
GetCoattail Research — Starbucks heads into fiscal-year results on October 28 with its turnaround under examination: comparable sales are rising, reported revenue is falling, and analysts' targets sit well above the price. We ran it through every filing lens we maintain. In the second quarter — while the price rose 14.1% — the tracked superinvestors cut their share count 27.8%, and not one of them was new.
Start with the narrative, because at the moment it is a turnaround being graded in public. Starbucks reported fiscal third-quarter 2026 results for the period ended June 28, 2026: consolidated revenue of $9.32 billion, down 1.4% year over year — a decline shaped by the shift of its China business toward a licensed joint-venture model — while global comparable-store sales rose 7.9% and North America comparable sales rose 8.1%. GAAP earnings per share rose 85.7% to $0.91, non-GAAP earnings per share rose 70% to $0.85, and non-GAAP operating margin expanded 430 basis points to 14.4%. Management raised full-year guidance to non-GAAP earnings per share of $2.55 to $2.65. Analysts are spread above the price: Bank of America kept a Buy rating and a $143 target on October 1, RBC Capital kept a Hold and a $115 target on October 5, JPMorgan cut its target from $112 to $105 on October 2, and MarketBeat's consensus target stands at $110.48. The stock closed at $94.71 on October 2 in our price file, down about 10.5% over the preceding month in quote-provider figures, inside a 52-week range of $77.99 to $110.51. Fiscal-year results arrive October 28.
Now the filings. GetCoattail tracks the investors best placed to know any company: superinvestors, institutions, insiders, Congress, and 5% holders. For Starbucks — the fifteenth Filing Tape audit, after IREN, CoreWeave, Micron, NVIDIA, Tesla, AMD, Apple, Amazon, Meta, Oracle, Dell, Bloom Energy, Palantir and Netflix — the narrow register and the broad register moved in opposite directions, and that split is the finding.
Lens 1: the superinvestors — five holders, and the cohort shrank
We track 83 large, mostly long-only managers whose 13F portfolios we collect directly from SEC EDGAR. As of June 30, 2026, five held Starbucks in long common-stock positions — every reported row is a long position, with no option rows in the count. Their combined position is 4,457,745 shares worth $455,536,971. On a like-for-like pipeline basis the cohort shrank in the second quarter, falling from 6,177,688 shares across six holders at March 31 to 4,457,745 shares across five at June 30 — down 27.8% — in a quarter when the share price rose from $89.59 to $102.19 in our price file, up 14.1%. The pipeline and EDGAR-collection second-quarter totals agree exactly, at 4,457,745 shares.
Of the five holders, none was new, one increased, one was unchanged and three decreased. The largest holder dominates the lens: Polen Capital reported 3,550,773 shares worth $362,853,519, a 3.13% portfolio weight — 79.7% of the entire cohort — and decreased its position 29.8% in the quarter. The deepest cut came from Semper Augustus, down 81.8% to 45,761 shares. Matrix Asset Advisors decreased 1.0% to 220,391 shares. Markel Group was unchanged at 623,818 shares, and the cohort's only increase was its smallest position: First Eagle rose 3.8% to 17,002 shares. The top two holders together are 93.6% of the cohort. This is a small, concentrated register that got smaller into a rising price.
Lens 2: institutions — more filers, 18.83% more shares
Zoom out to the whole 13F market and the register moved the other way. At June 30, 2026, 2,405 institutions reported positions in Starbucks, up from 2,322 at March 31 — a 3.6% rise — and 2,386 of them reported long positions. Reported share counts rose 18.83%, from 814,858,252 to 968,311,094 shares, with 1,757 filers entering and 1,674 exiting. The dataset's reported aggregate value rose 36.4% to $101,789,842,688; the aggregate includes option rows, so we treat filer and share counts as the reliable series and the dollar figure as reported (see methodology). The broad market added shares in the same quarter in which the tracked cohort removed more than a quarter of its position.
Lens 3: the 5% register — eight filings, all passive, two Capital arms above 8%
Eight SC 13D/G filings cover Starbucks — zero 13D filings and eight 13G filings, from four reporting names, the most recent filed August 12, 2026. The largest current rows belong to two Capital Group reporting arms, which we report separately and do not sum. Capital World Investors reported 104,838,568 shares (9.2%) as of March 31, 2026, then 92,900,338 shares (8.2%) as of June 30, 2026 — the freshest 5% row in the register, and a reduction during the quarter this audit covers. Capital Research Global Investors reported 102,403,410 shares (9.0%) as of March 31, 2026. The Vanguard Group reported 0 shares (0.0%) as of March 13, 2026, after reporting 113,888,463 shares (10.01%) as of October 31, 2025, while Vanguard Capital Management filed a new 13G reporting 85,640,059 shares (7.51%) as of March 31, 2026 — the same reporting-name sequence that appeared in our Palantir and Netflix audits; we report the rows as filed, without summing them or calling the zero an exit. No 13D — the filing an investor uses when it wants something from management — has appeared at all.
Lens 4: insiders — one purchase in the entire parsed record
The insider lens is thin in both directions. Across the entire parsed Form 4 record for Starbucks (60 filings through October 2, 2026), there is exactly one open-market purchase transaction — 11,700 shares for $994,500, by one buyer. Officer purchases are zero in every window: the single purchase was not recorded as an officer transaction. In the 90 days through October 2, 2026, insiders filed five reports covering three sale transactions totalling 6,687 shares and $703,450.11, by one seller — all three recorded as officer sales. Over the full parsed record, sales total 12 transactions and $2,028,131.05 by two sellers, and every parsed purchase and sale falls within the most recent one-year window. One disclosure about our own data: our site's insider aggregate, compiled as of October 9, 2026, shows two sales and $471,634.11 for the 90-day window, which does not match the full-parse figures; the full-parse record is primary here, and we report both rather than silently choosing one. Some selling is mechanical — vesting, tax withholding and pre-arranged plans generate filings regardless of anyone's view — and we assign no motives. What the record establishes is narrower: in the entire parsed history, Starbucks insiders bought at market price once.
Lens 5: Congress — zero buys, two sells
Across the Senate and House transaction record we maintain (as of October 3, 2026), Starbucks shows zero purchase transactions and two sale transactions. The House aggregate carries one sale and the Senate aggregate carries one sale; neither records a purchase, and the combined record lists no most-recent purchase date. Its member and party fields are recorded as empty for this ticker, so we report the chamber split exactly as recorded and do not attribute the sales further. Congressional disclosures report value ranges rather than exact amounts, so we record direction only. The lens is two transactions — small, and entirely on one side.
Lens 6: short interest — 3.50% of the share count, 23.1% below its May peak
As of September 15, 2026 — the most recent FINRA settlement date — 39,883,349 Starbucks shares were sold short, with days-to-cover of 7.19. That is 3.50% of the 1,140,000,000 shares outstanding in our fundamentals file (a share count as of July 23, 2026).
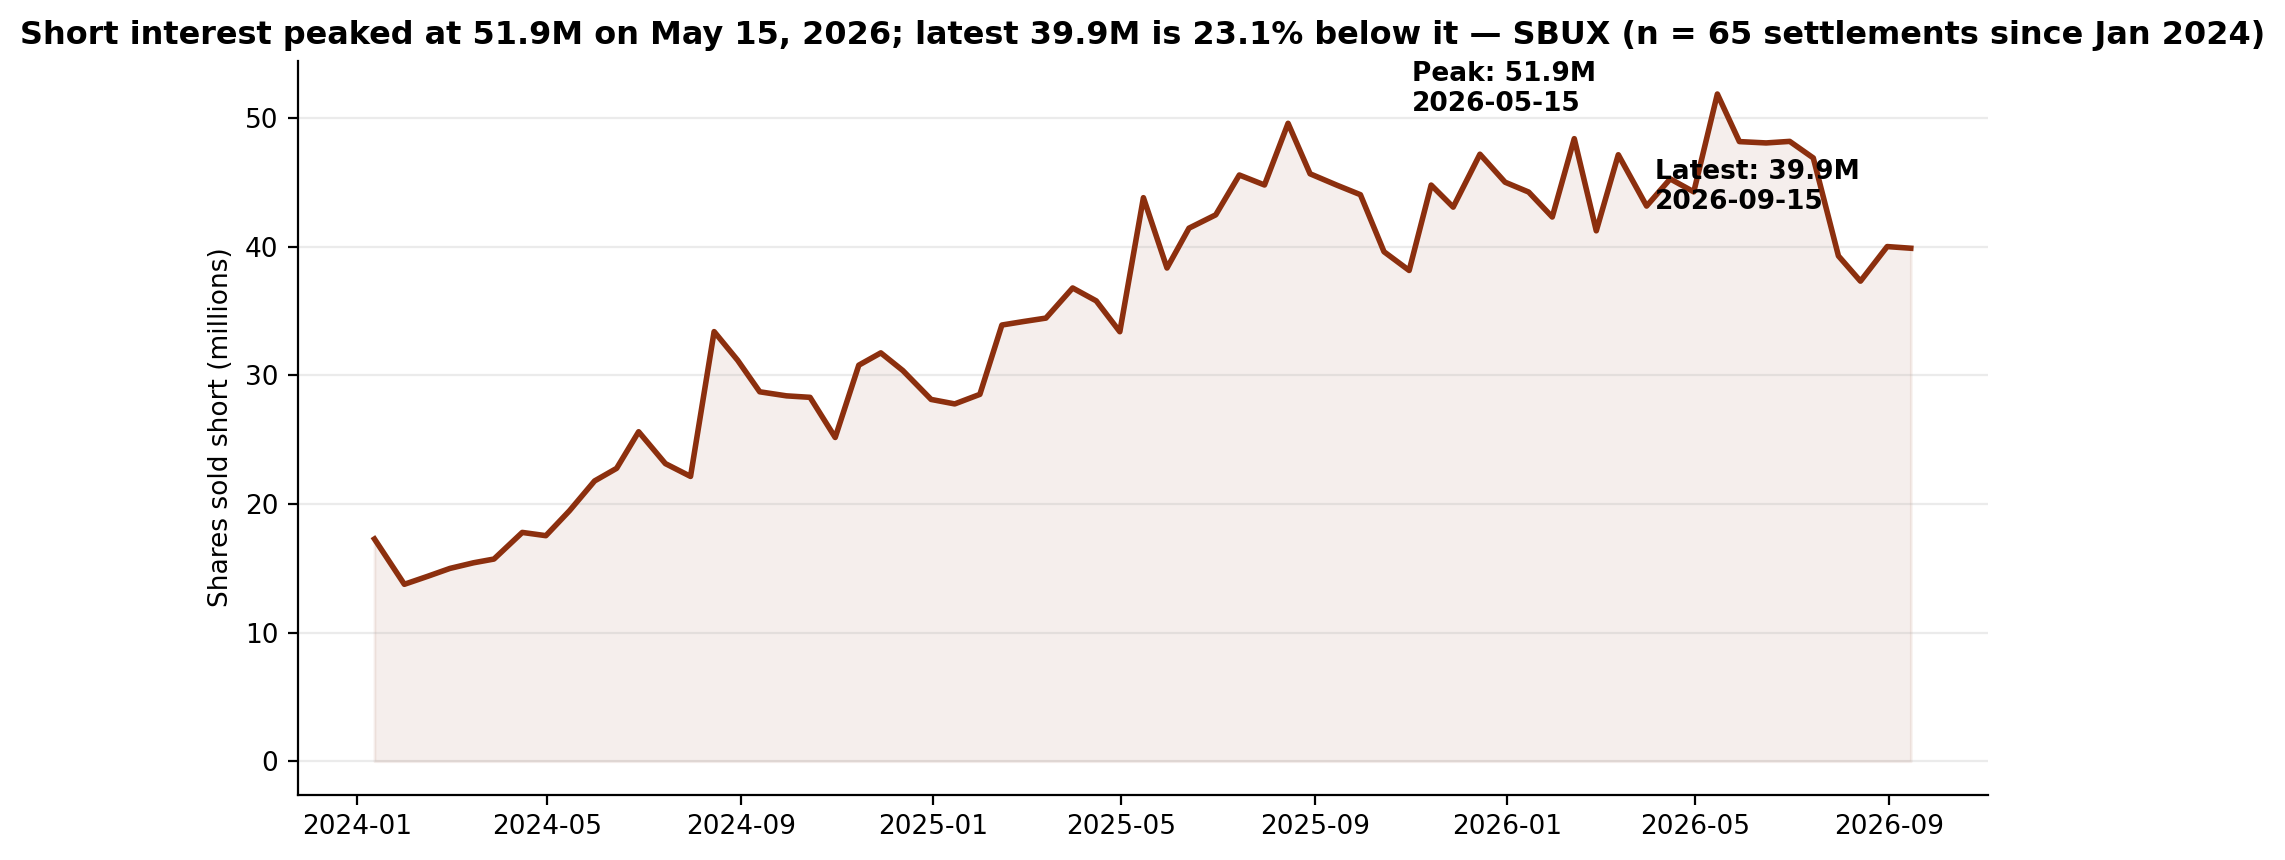
The recent settlements run 46,903,610 on July 15, then 39,283,410, 37,322,857, 40,013,836 and 39,883,349. The borrow peaked before the second-quarter filing season opened and has since eased by 23.1%. On this lens, at least, the pressure has been receding since May.
The gap, stated plainly
Starbucks' filing record splits between a broad register that added shares and every narrower register that did not. The full market expanded in the second quarter: 2,405 filers, up 3.6%, holding 968,311,094 shares, up 18.83%. Against that, the tracked superinvestors cut 27.8% of their shares in a quarter when the price rose 14.1%, with three of five holders decreasing, none new, and the largest holder — 79.7% of the cohort — cutting 29.8%. The freshest 5% row points the same way: Capital World Investors reduced from 9.2% at March 31 to 8.2% at June 30. Insiders recorded one purchase in the entire parsed record, for $994,500, against $2,028,131.05 of sales. Congress recorded no purchases and two sales. Short interest, at 3.50% of the share count, sits 23.1% below its May 15 peak — the one lens moving toward the bullish narrative, and it measures bears retreating rather than bulls arriving. One plausible reading is that the second-quarter price rise was carried by the broad register while the concentrated, named registers stood aside or stepped back. The record supports each clause separately; it does not say which register is right.
What would change the picture
Nothing above is a recommendation. It is a record. These are the filings that would change the description:
- 1. The 2026Q3 13Fs (filing window closing mid-November 2026). Whether Polen Capital's 3,550,773 shares — 79.7% of the superinvestor cohort after a 29.8% cut — survive a quarter in which the price fell 7.3% from June 30 to October 2 is the cleanest test of whether the second-quarter reduction was trimming or an exit in progress.
- 2. A second insider purchase. The parsed record holds exactly one, for $994,500, and no officer purchases at all. A second purchase transaction, at any size, changes this lens from a standing near-zero to a pattern; continued silence extends a record of 12 sales against a single buy.
- 3. Fiscal-year results on October 28, 2026. The print tests the narrative the filings are arguing over: a raised full-year guide of $2.55 to $2.65 of non-GAAP earnings per share, comparable sales rising 7.9% globally against reported revenue down 1.4%, and a consensus target of $110.48 sitting above a $94.71 close.
- 4. The congressional record after two sales. Zero purchases and two sales is a small sample entirely on one side. The next transaction either extends that lean or becomes the register's first purchase in our record.
- 5. The short-interest series from its May 15 peak. The borrow peaked at 51,873,965 shares on May 15, 2026 and has since eased 23.1% to 39,883,349. Whether it rebuilds through the October 28 results or keeps easing is the fastest-updating series in this audit: FINRA publishes it every two weeks.
Until one of those prints, the filing record describes a stock whose broad register added 18.83% more shares in the second quarter while its tracked superinvestors cut 27.8% of theirs into a 14.1% price rise — five holders, none new, one of them holding 79.7% of the cohort — whose insiders have bought once in the parsed record, and whose short borrow has been receding since May.
Related reading: Eleven of 83: The Superinvestors Doubled Their Netflix Shares While the Price Fell 25.7% — Filing Tape #14; Zero of 83: The Superinvestors Aren't in IREN — Filing Tape #1; 80% Overlap, No Copycat Signal: Congress vs. the Superinvestors. Starbucks' own page: Starbucks (SBUX) on GetCoattail.
Methodology and data notes
- Superinvestor lens: 83 managers collected directly from SEC EDGAR Form 13F (managers_13f collection), positions as of June 30, 2026; Starbucks identified by CUSIP 855244109. Five distinct managers hold long positions totalling 4,457,745 shares; all five reported rows are long (no put or call rows). Quarter-to-quarter cohort totals (6,177,688 shares across 6 pipeline rows at March 31; 4,457,745 across 5 pipeline rows at June 30) are from the site pipeline's holdings files on the same CUSIP basis in both quarters; the change is −27.8% ((4,457,745 / 6,177,688) − 1), and the pipeline's second-quarter total agrees exactly with the EDGAR collection's long total (difference: 0 shares). Polen Capital's share of the cohort is 3,550,773 / 4,457,745 = 79.7%; the top two holders total 93.6%. Direction counts across the five long holders: 0 new, 1 increased, 1 unchanged, 3 decreased.
- Full-market lens: SEC Form 13F Data Sets full-market aggregation (the fixtures underlying our 2026Q1–Q2 market tables). Holders = distinct filers reporting the CUSIP; 2,386 of the 2,405 reported long positions. Reported-value caution: the aggregate value ($101,789,842,688 over 968,311,094 shares) implies ≈$105.12 per share against a June 30, 2026 close of $102.19 in our price file. The aggregate sums the VALUE of every information-table row — including put and call option rows — while the share count covers long common-stock rows only, so we headline filer and share counts and label dollar values "reported."
- Insider lens: full-parse Form 4 aggregation (agg_by_ticker), record as of October 2, 2026 (60 filings). Sale and purchase counts are transaction-code counts (S and P) in non-derivative rows; grants and exercises are not counted as purchases, and one filing can contain many transaction rows. Purchase transactions total one across the full record (11,700 shares, $994,500, one buyer); officer purchases are zero in every window; officer sale transactions are 3 in 90 days and 12 across the record. The site's insider aggregate (compiled as of October 9, 2026) shows a different 90-day window — 0 purchases, 2 sales, $471,634.11, one seller — against the full-parse 90-day figures of 0 purchases, 3 sales and $703,450.11; both are reported in the article, and the full-parse record is treated as primary.
- 13D/G lens: full-parse SC 13D/G aggregation and parsed filings (8 filings matching CUSIP 855244109, 4 reporting names), filings through August 12, 2026. Capital World Investors and Capital Research Global Investors are separate reporting persons and their rows are not summed; The Vanguard Group's 0-share row (event date March 13, 2026) and Vanguard Capital Management's 85,640,059-share row (event date March 31, 2026) are likewise reported as separate rows from separate reporting persons and are not summed; the aggregation's totalSharesReported field sums overlapping reporters and successive amendments and is not used. Percentages are quoted exactly as reported in the respective filings.
- Congress lens: Senate PTR archive and House PTR archive as maintained on this site, combined record as of October 3, 2026. Counts are transaction counts in the aggregated member record; congressional disclosures report value ranges, so no dollar figures are used for this lens. The combined record shows zero buys and two sells, with member and party fields recorded as empty; the House aggregate (as of October 3, 2026) shows zero buys and one sell, and the Senate aggregate (as of October 1, 2026) shows zero buys and one sell.
- Short interest lens: FINRA Equity Short Interest files (biweekly settlement dates), collected directly from FINRA's public distribution; the Starbucks series covers 137 settlements from January 15, 2021 to September 15, 2026. The peak of 51,873,965 shares on May 15, 2026 is the peak of the full collected series. FINRA publishes each settlement about two weeks after the fact. The share-count ratio uses the fundamentals file's share count of 1,140,000,000 — a shares-outstanding count as of July 23, 2026.
- Fundamentals note: our fundamentals collection carries Starbucks' fiscal-2025 figures — revenue $37,184,400,000, net income $1,856,400,000 and assets $32,019,700,000 — for the fiscal year ended September 2025. The fiscal third-quarter 2026 figures in the introduction are from the company's 2026 results as reported by multiple outlets (see market context sources), not from our fundamentals file. The market value of about $109.6 billion uses that file's October 6, 2026 price ($96.11) and reported share count.
- Prices: our own daily-close file for Starbucks through October 2, 2026 ($94.71 close, +12.5% year to date on that file; 252-session closing high $108.55 on August 13, 2026; 252-session closing low $78.46 on October 10, 2025; closes of $89.59 at March 31, 2026 and $102.19 at June 30, 2026, a second-quarter change of +14.1%; change from June 30 to October 2 of −7.3% ((94.71 / 102.19) − 1)). The drawdown from the 252-session closing high is −12.7% ((94.71 / 108.55) − 1).
- Market context sources: fiscal third-quarter 2026 results (revenue $9.32 billion, down 1.4% year over year; GAAP EPS $0.91, up 85.7%; non-GAAP EPS $0.85, up 70%; global comparable-store sales up 7.9%; North America comparable sales up 8.1%; non-GAAP operating margin 14.4%; net profit about $1.05 billion) and raised full-year guidance (non-GAAP EPS $2.55–$2.65) — company results as reported by Yahoo Finance, Tickeron and ad-hoc-news coverage, checked October 9, 2026; fiscal-year results date of October 28, 2026 — as reported by Yahoo Finance and TheStreet, checked October 9, 2026; Bank of America's Buy rating and $143 target (October 1, 2026), RBC Capital's Hold rating and $115 target (October 5, 2026), JPMorgan's target cut to $105 (October 2, 2026) and MarketBeat's consensus target of $110.48 — as reported by Yahoo Finance, Markets Insider, Benzinga and MarketBeat coverage, checked October 9, 2026; quarterly dividend of $0.63 declared October 7, 2026 (payable November 27, record date November 13) — The Cerbat Gem / MarketBeat dividend coverage, checked October 9, 2026; one-month price decline of about 10.5% to the October 2 close and 52-week range of $77.99–$110.51 — TheStreet and quote-provider data, checked October 9, 2026; social-media attention ranking (Starbucks third among meme-stock mentions, 109 in 24 hours, updated October 8, 2026) — AltIndex, checked October 9, 2026. Figures we could not confirm against two sources were left out.
- Starbucks is in the GetCoattail stock-page universe: Starbucks (SBUX) stock page. Series data: sbux_lens_data.csv · sbux_short_interest_series.csv. Earlier audits: Netflix · Palantir · IREN.
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history
- v1.0 — October 9, 2026: first publication.