GetCoattail Research — The Filing Tape #60. Salesforce is the customer-relationship software maker whose shares rose 2.1% on October 12, 2026 after Bank of America upgraded them two notches in a single note, and whose fiscal second-quarter print paired an earnings beat with a raised full-year outlook. The filings describe a register that spent the second quarter adding shares into a falling price: the tracked superinvestor cohort grew its long position 7.6% and the full market added 50,476,799 reported shares, an insider record whose nine purchases were never once made by an officer, a congressional record of two buys and no sales from a single House member, and a borrow that has fallen 58.4% from its March peak while still standing 147.9% above a year ago.
Start with the narrative. On October 12, 2026, Bank of America upgraded Salesforce from underperform to buy — a two-notch move in one note — and raised its price target from $160 to $285, an implied 24.48% upside from the prior close of $229.13. The stock gapped up at the open, to $236.65 from that $229.13 close, and finished the day up 2.1%, on the Wall Street Journal's stocks-to-watch recap alongside Microsoft. The wider register is constructive: counts published the same day put the consensus at Moderate Buy with an average target of $278.12, from 3 strong buys, 31 buys, 14 holds and 2 sells. Underneath the upgrade sits a fiscal second-quarter print — revenue of $11.35 billion, up 11% year over year and above an $11.32 billion consensus, adjusted earnings of $5.90 a share against a $3.27 consensus, a full-year revenue outlook raised to between $46.1 billion and $46.4 billion, and a new AI partnership with Anthropic announced alongside. Our own price file, which ends October 2, closes CRM at $234.69 — up 56.3% from the 252-session closing low of $150.12 set on June 22, 2026, still 11.8% below the 252-session closing high of $266.23 from December 29, 2025, and down 11.4% year to date. The next scheduled test of the story is the third-quarter print; the next test of the registers below is the third-quarter 13F season closing in mid-November.
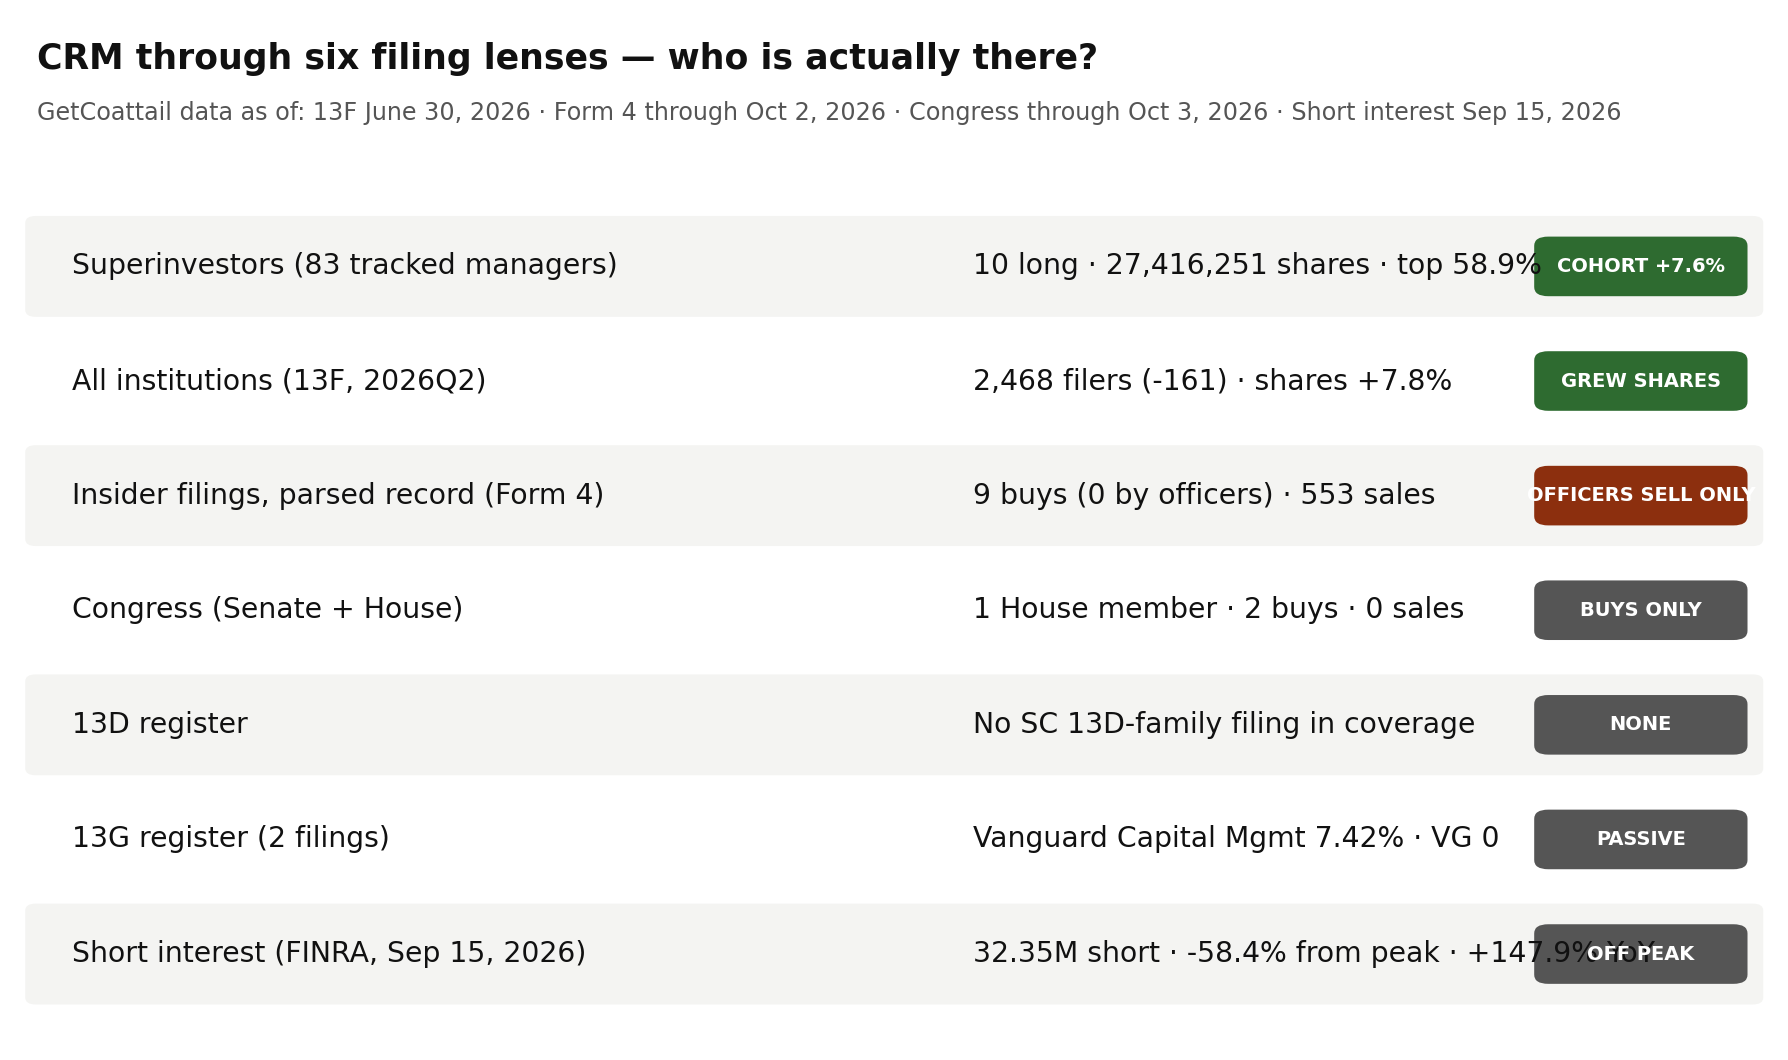
Now the filings. For CRM — the sixtieth Filing Tape audit — the tape shows a ten-name tracked cohort that added shares in a falling quarter under one dominant holder, a broad register that added 50.5 million shares while shedding 161 filers, a 5% register that is two Vanguard rows and nothing else, an insider record in which officers have sold 550 times and never bought, a one-member congressional record of buys only, and a borrow retreating from a March peak it has not come close to revisiting.
Lens 1: the superinvestors — ten holders, one of them 58.9%
We track 83 large, mostly long-only managers whose 13F portfolios we collect directly from SEC EDGAR. As of June 30, 2026, 10 held CRM long totalling 27,416,251 shares worth $4,295,029,873, plus one call-option row — Chuck Akre's 100,000 shares, reported at $15,666,000 — which this audit keeps out of the long totals. The direction count on the collection's own labels, across the long rows, is three increases, three unchanged, three decreases and one new position. The cohort exited list names two departures — AKO Capital, at 354,805 shares in the March file, and Polen Capital Management, at 1,215 shares — and here the labels and the filing continuity agree everywhere they can be checked: all nine continuing holders' percentage labels match their March-to-June share changes (see methodology). The cohort total moved from 25,473,651 long shares at March 31 to 27,416,251 at June 30, a change of +7.6% — a difference of +1,942,600 shares, accumulated in a quarter when the price fell from $186.67 to $156.66, a change of -16.1%.
The largest holder is Bill Nygren - Oakmark Funds, with 16,151,269 shares worth $2,530,257,772, a 3.35% portfolio weight — 58.9% of the tracked cohort's CRM shares — flagged increased by 8.3%, and the pipeline's March file carries the position at 14,917,993 shares, so the label and the continuity agree. First Eagle Investment Management is second, with 7,306,034 shares worth $1,144,563,308, up 19.1% from 6,132,564. Third is ValueAct Capital, with 2,994,509 shares worth $469,119,780 — the cohort's largest portfolio weight at 8.33% — unchanged at exactly its March share count. The rest of the register is small by comparison: Akre Capital Management holds 717,799 long shares, unchanged, alongside its call row; Vulcan Value Partners cut 16.7% to 164,013 shares; Wallace Weitz cut 39.5% to 49,300; Robert Vinall - RV Capital GmbH held 15,511 shares unchanged; Hillman Capital Management rose 24.7% to 13,658; Mairs & Power Funds cut 94.7% to 2,656; and Richard Pzena - Pzena Investment Management opened the register's one new position, 1,502 shares. The cohort's implied price, $156.66 per share, sits exactly on the June 30 close of $156.66. This register did not flee the second quarter's fall. It added to it — mostly through its two largest holders, who together account for 23,457,303 of the 27,416,251 shares.
Lens 2: institutions — 161 fewer filers, 50.5 million more shares
Zoom out to the whole 13F market and the register moved the same way as the tracked cohort on shares, and the opposite way on heads. At June 30, 2026, 2,468 institutions reported positions, down 161 from 2,629 at March 31 (-6.12%), and 2,453 of them reported long positions. Reported shares rose 7.82%, from 645,437,545 to 695,914,344 shares — 50,476,799 more shares than the prior quarter. Reported aggregate value fell 10.11% to $117,101,298,246; the aggregate includes option rows, so we headline filer and share counts and label dollars "reported" (see methodology). The implied value per share, $168.27, sits 7.4% above the June 30 close of $156.66 — a gap published as found, and one more reason to headline the share count rather than the dollars: the broad register, like the tracked cohort, ended a quarter of falling prices holding more shares spread across fewer filers.
Lens 3: the 5% register — two Vanguard rows, and nothing else
Our full parse holds exactly 2 SC 13D/G filings for CRM — one SC 13G and one SC 13G/A, and no SC 13D-family filing at all — two reporting persons, the most recent filed April 30, 2026. Both rows belong to the Vanguard complex, and both are re-papering prints rather than positions built in the open. In an SC 13G filed April 30, 2026, Vanguard Capital Management prints 68,562,595 shares (7.42%) as of March 31, 2026 — the register's maximum, and its only row carrying a stake. In an SC 13G/A filed March 27, 2026, The Vanguard Group prints 0 shares (0.0%) as of March 13, 2026. That is the whole 5% register in our parsed coverage: one passive complex moving its reported stake from one reporting entity to another, and no activist paper of any kind.
Lens 4: insiders — nine purchases, none of them by an officer
The parsed Form 4 record holds 291 filings through October 2, 2026. Across the whole record, open-market purchases total 9 transactions, totalling 116,230 shares and $29,880,252.93, by five buyers — and not one of the nine is recorded as an officer purchase. Sales total 553 transactions, totalling 464,119 shares and $119,234,053.15, by eleven sellers, and 550 of the 553 are recorded as officer sales. The last year holds 123 filings, 6 purchases totalling 107,253 shares and $27,516,297.46 by three buyers — again with zero officer purchases — against 155 sales totalling 192,677 shares and $46,052,347.94 by four sellers, 152 of them officer sales. The last 90 days hold 22 filings with 1 purchase of 4,176 shares for $999,450.85 and 2 sales of 4,500 shares for $1,172,746.10, one buyer and one seller, neither recorded as an officer; the most recent purchase in the site's aggregate is dated September 18, 2026. Our site's insider aggregate, compiled as of October 13, matches the full parse's 90-day window exactly. We assign no motives to any of it; the asymmetry itself — a purchase register that exists, but has never once carried an officer's name in our parsed record, against 550 officer sales — is the fact.
Lens 5: Congress — one House member, two purchases, no sales
The congressional record we maintain is small and one-directional for this name. The combined record (as of October 3, 2026) carries one member, 2 recorded purchases and 0 recorded sales, the most recent purchase dated June 2, 2026, the member recorded as Republican. The House aggregate (as of October 3, 2026) carries the same one member, the same 2 purchases and the same 0 sales — the combined record is the House record. The Senate aggregate (as of October 1, 2026) carries no CRM row at all. No recorded sale in either chamber's record as this site maintains them.
Lens 6: short interest — 32,348,247 shares, down 58.4% from the peak, up 147.9% in a year
FINRA's files carry the borrow across 137 settlements, from January 15, 2021. As of September 15, 2026 — the most recent settlement — 32,348,247 CRM shares were sold short, with days-to-cover of 2.47. That reading rose 10.74% from the prior settlement's 29,211,825 shares on August 31, 2026, completing two consecutive increases from 26,502,629 on August 14, after a sharp two-step fall from 46,465,690 on July 15. Against September 15, 2025 the latest reading is up 147.9% from 13,050,735 shares. Both of those statements are true alongside the larger one: the series maximum is 77,814,603 shares on March 31, 2026, a fact we verified by taking the maximum across the whole series rather than reading it off the latest row, and the latest reading sits 58.4% below that peak. Against the fundamentals file's 823,000,000 shares outstanding, the latest reading is 3.93% of the share count. The June 30, 2026 settlement — the date the 13F lenses snapshot — printed 50,636,166 shares; the latest reading sits 36.1% below it. The series minimum is 6,536,279 shares on October 13, 2023; the series' own first settlement, on January 15, 2021, printed 24,115,577 shares.
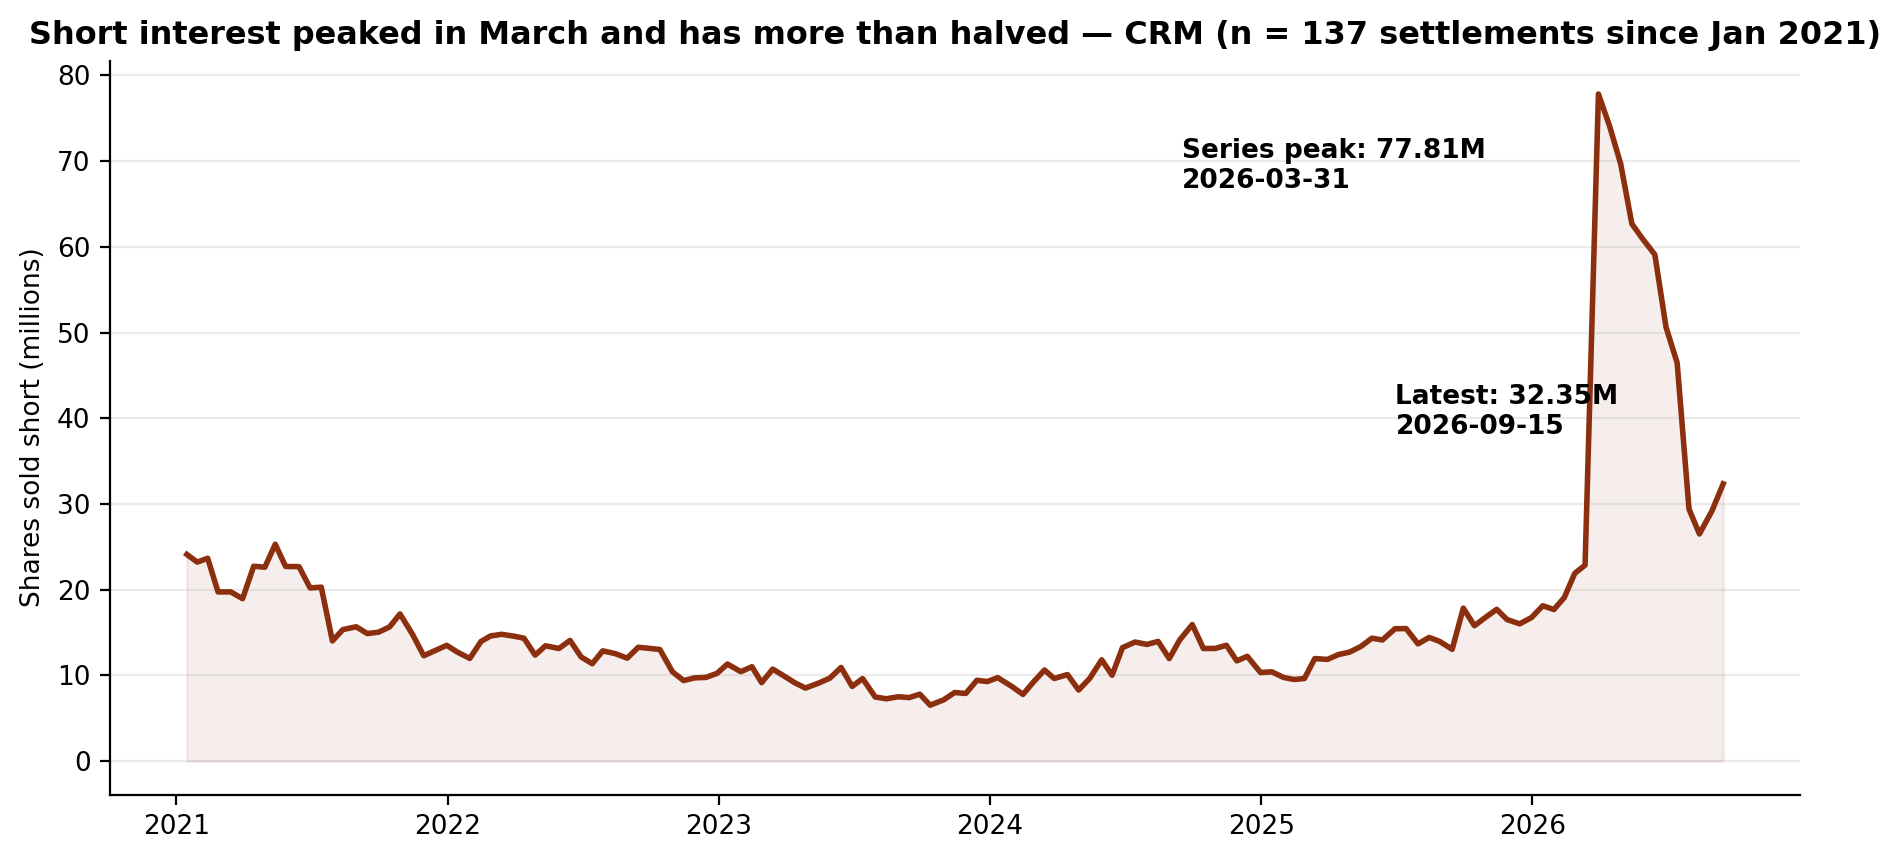
The borrow is neither at its peak nor back at its lows. It peaked in March, halved into August, and has risen twice since.
The gap, stated plainly
The narrative describes a software maker being re-rated in real time: a two-notch Bank of America upgrade with a $285 target against a $229.13 prior close, a Moderate Buy consensus averaging $278.12, a fiscal quarter that beat on earnings and raised its outlook, and a stock up 56.3% from its June closing low on our price file. The filings describe the positioning that preceded all of it. The tracked superinvestors held 27,416,251 shares at June 30 across ten holders, having added 7.6% in a quarter when the price fell 16.1% — with one holder, Oakmark, carrying 58.9% of the stake and the two largest holders carrying 23,457,303 shares between them. The full market moved the same way on shares: 695,914,344 reported shares, up 50,476,799, across 2,468 filers — 161 fewer than the prior quarter, so the average reported position grew even as the filer count shrank. The 5% register printed 2 filings, both Vanguard re-papering: a 7.42% stake under a new reporting entity, and a zero row under the old one. Insiders, across 291 parsed filings, recorded 9 purchases against 553 sales, with every purchase made by a non-officer and 550 of the sales made by officers. Congress records one House member with 2 purchases and no sales. And the borrow stands at 32,348,247 shares — up 147.9% in a year and rising for two settlements, yet 58.4% below the 77,814,603-share peak it printed on March 31, and 36.1% below where it stood on the June 30 snapshot date itself. One plausible reading is that the registers are describing a name the institutions accumulated through its drawdown and the shorts largely exited before the re-rating: the broad register and the tracked cohort both added shares into a -16.1% quarter, the borrow peaked at that quarter's start and then more than halved, the insider tape's buying exists but has never included an officer, and the congressional tape leans, trivially, to the buy side — all of the 13F part of it snapshot at June 30, before the fiscal second-quarter print and the October upgrade that power the current narrative existed as news. The record supports each clause separately; it does not say which register is right, and it cannot — the tracked cohort's whole position is a June 30 snapshot of 27,416,251 shares, taken weeks before that print.
What would change the picture
Nothing above is a recommendation. It is a record. These are the filings that would change the description:
- 1. The 2026Q3 13Fs (filing window closing mid-November 2026). The tracked cohort held 27,416,251 shares at June 30 across ten holders, after a +7.6% move in a falling quarter. Whether Oakmark's 16,151,269 shares grow for a second straight quarter, and whether any holder joins ValueAct above an 8% portfolio weight, are the first things the next register will answer.
- 2. Whether the borrow keeps retreating from its peak, or rebuilds. Short interest stands at 32,348,247 shares, 58.4% below the March 31 peak of 77,814,603 and up 147.9% in a year, having risen at each of the last two settlements. A reading back below the August 14 print of 26,502,629 would resume the unwind; a move back toward the June 30 settlement's 50,636,166 would rebuild it.
- 3. A first officer purchase, at any size. The parsed record holds 9 purchases and not one by an officer, against 550 officer sales. A single open-market officer purchase would end a streak that currently covers the entire parsed record.
- 4. A second congressional name, or a first recorded sale. The combined congressional record carries one House member with 2 purchases and 0 sales, and the Senate carries no row. Any new member, either chamber, either direction, would change this lens from a single-member register into a broader one.
- 5. A first SC 13D, or a new 5% name. The 5% register in our parsed coverage holds two Vanguard rows and no SC 13D-family filing. An original 13D from any filer, or a 13G from outside the Vanguard complex, would give this lens its first non-passive content.
Until one of those prints, the record describes a stock held by ten of our 83 tracked superinvestors — 27,416,251 shares, raised 7.6% in the quarter its price fell 16.1%, with one holder carrying 58.9% of the stake — whose full market added 50,476,799 reported shares while losing 161 filers, whose insiders have recorded 9 purchases and no officer purchase ever against 553 sales, whose congressional register is one member with two buys and no sales, and whose borrow has fallen 58.4% from its March peak while doubling and more against a year ago — all of it snapshot at June 30, before the earnings print and the upgrade the current story rests on.
Related reading: Three of 83: The Superinvestors Cut Lululemon 86.0% in Q2. Short Interest Just Hit a Record. — Filing Tape #59; Three of 83: One Holder Is 99.2% of the Superinvestors' Gilead Stake. Its Insiders Have Never Bought a Share. — Filing Tape #58; Zero of 83: The Superinvestors Aren't in IREN — Filing Tape #1. CRM's own page: Salesforce, Inc. (CRM) on GetCoattail.
Methodology and data notes
- Superinvestor lens: 83 managers collected directly from SEC EDGAR Form 13F (managers_13f collection), positions as of June 30, 2026; CRM identified by CUSIP 79466L302. Ten distinct managers hold long positions totalling 27,416,251 shares; one further reported row is a call-option position (Akre Capital Management, 100,000 shares, $15,666,000), excluded from the long totals throughout. The direction count on the collection's labels, across the long rows, is three increased, three unchanged, three decreased and one new; the collection's exit list contains two CRM rows (AKO Capital, 354,805 shares previously reported at $66,231,000; Polen Capital Management, 1,215 shares previously reported at $226,859). Quarter-to-quarter cohort totals (25,473,651 long shares at March 31; 27,416,251 long shares at June 30; change +7.6%) are from the site pipeline's holdings files on the same CUSIP basis in both quarters, and the pipeline's second-quarter long share total matches the EDGAR collection's long total exactly (difference of 0 shares); the pipeline's all-rows second-quarter value exceeds the collection's long value by exactly the $15,666,000 call row, which is the whole difference. Per-holder quarter changes are matched by filing continuity across the two pipeline files: for all nine continuing holders they agree with the EDGAR collection's own percentage labels (Oakmark Funds 14,917,993 → 16,151,269 = +8.3%; First Eagle 6,132,564 → 7,306,034 = +19.1%; the 10,956-share March row matched to Hillman Capital Management 10,956 → 13,658 = +24.7%; the 49,996-share March row matched to Mairs & Power Funds 49,996 → 2,656 = -94.7%; Vulcan Value Partners 196,803 → 164,013 = -16.7%; the 81,500-share March row matched to Weitz Investment Management 81,500 → 49,300 = -39.5%; Akre Capital Management 717,799 → 717,799 = 0.0%; ValueAct Capital 2,994,509 → 2,994,509 = 0.0%; RV Capital GmbH 15,511 → 15,511 = 0.0%), and the 1,502-share Pzena row has no first-quarter counterpart, agreeing with its NEW label. The unnamed March rows are matched on share counts and accession numbers against the EDGAR collection. Oakmark's share of the cohort is 58.9% = 16,151,269 / 27,416,251, and the two largest holders' combined share count is 23,457,303 = 16,151,269 + 7,306,034.
- Full-market lens: SEC Form 13F Data Sets full-market aggregation. The primary table is the full13f collection's by-ticker file (holders = distinct filers reporting the CUSIP; 2,453 reported long positions out of 2,468 filers). CRM reports under a single CUSIP spelling, 79466L302, and the backfill fixtures' by-CUSIP file carries the same row — the cross-check matches on every field (holders, shares, reported value, prior holders and prior reported value). The by-ticker file's entered/exited fields (1,688 and 1,849, a net of -161 that matches the change in holder count) are gross flows, so this audit headlines the net change. Reported-value caution: the aggregate value ($117,101,298,246 over 695,914,344 shares) implies $168.27 per share against a June 30, 2026 close of $156.66 in our price file, a gap of +7.4% — printed here as found. The aggregate sums the VALUE of every information-table row — including put and call option rows — while the share count covers long common-stock rows only, so we headline filer and share counts and label dollar values "reported."
- Insider lens: full-parse Form 4 aggregation (agg_by_ticker), record as of October 2, 2026 (291 filings). Sale and purchase counts are transaction-code counts (S and P) in non-derivative rows; grants and exercises are not counted as purchases, and one filing can contain many transaction rows. Purchase transactions total 9 across the parsed record (116,230 shares, $29,880,252.93, five buyers, zero of them recorded as officer purchases in any window — the all-period, last-year and 90-day officer-purchase counts are each 0); the last year holds 6 (107,253 shares, $27,516,297.46, three buyers) and the 90-day window holds 1 (4,176 shares, $999,450.85, one buyer). Sale transactions total 553 across the record (464,119 shares, $119,234,053.15, eleven sellers, 550 of them recorded as officer sales); the last year holds 155 (192,677 shares, $46,052,347.94, four sellers, 152 officer sales) and the 90-day window holds 2 (4,500 shares, $1,172,746.10, one seller, no officer sales). The site's insider aggregate (compiled as of October 13, 2026) matches the full parse's 90-day window exactly (1 purchase, 1 buyer, $999,450.85; 2 sales, 1 seller, $1,172,746.10; most recent purchase September 18, 2026), so this audit prints one 90-day count rather than two.
- 13D/G lens: full-parse SC 13D/G parsed filings (2 filings matching issuer CIK 1108524 on CUSIP 79466L302, 2 reporting-person rows across 2 names: one SC 13G filing and one SC 13G/A amendment, no SC 13D-family filings), filings through April 30, 2026. The site aggregation's by-ticker file carries the same totals (2 filings, 2 reporters, latest filing April 30, 2026, maximum 7.42%, total reported 68,562,595 shares), so the aggregate and the parse agree here; the aggregation's total sums reporting-person rows, and here the two rows are different entities reporting at different dates, so that total is the sum of one 68,562,595-share row and one 0-share row and is not used as a stake figure in the article. Vanguard Capital Management's row (68,562,595 shares at 7.42% as of March 31, 2026, filed April 30, 2026, SC 13G) and The Vanguard Group's row (0 shares at 0.0% as of March 13, 2026, filed March 27, 2026, SC 13G/A) are reported as filed, under the reporting-person names exactly as they appear. No reason for any change is asserted — the filings themselves are the record. The parsed coverage for this issuer holds these 2 filings; a 5% holder that has not filed in the covered window would not appear here.
- Congress lens: Senate PTR archive and House PTR archive as maintained on this site. The combined record (as of October 3, 2026) carries one member with 2 recorded purchases and 0 recorded sales, most recent purchase June 2, 2026, party recorded as R; the House aggregate (as of October 3, 2026) carries the identical row, so the chamber sum checks: House (1 member, 2 purchases, 0 sales) + Senate (no row) = combined. The Senate aggregate (as of October 1, 2026) carries no CRM row at all.
- Short interest lens: FINRA Equity Short Interest files (biweekly settlement dates), collected directly from FINRA's public distribution. The published series covers 137 settlements from January 15, 2021 (24,115,577 shares) to September 15, 2026. The latest reading is 32,348,247 shares on September 15, 2026, up 10.74% from the prior settlement (29,211,825 on August 31, 2026) and the second consecutive increase after 26,502,629 on August 14, 2026, which followed a fall from 46,465,690 on July 15 through 29,406,370 on July 31. The series maximum is 77,814,603 shares on March 31, 2026 (verified by a maximum query over the series, not read off the latest row), so the latest reading sits 58.4% below the peak; against September 15, 2025 (13,050,735 shares) it is up 147.9%. The series minimum is 6,536,279 shares on October 13, 2023. The June 30, 2026 settlement printed 50,636,166 shares, so the latest reading sits 36.1% below the 13F snapshot date's borrow. FINRA publishes each settlement about two weeks after the fact, so the fiscal third-quarter earnings period expected later in 2026 is not yet in this series. The share-count ratio (3.93%) uses the fundamentals file's shares-outstanding figure below.
- Fundamentals note: our fundamentals collection carries CRM's revenue of $41,525,000,000 labelled fiscal 2026, its net income of $7,457,000,000 labelled fiscal 2026, and its assets of $112,305,000,000 labelled fiscal 2026. The file is marked ok for this name, with no missing fields: shares outstanding of 823,000,000 (as of August 20, 2026 in the file, sourced in the file to the issuer's reported shares-outstanding figure) and a file-computed market value of $185,166,774,520.87. The file's price for the name is $224.99 as of October 6, 2026; our daily-close file ends October 2, 2026 at $234.69, and we keep the two files' figures separate rather than blending them.
- Prices: our own daily-close file for CRM through October 2, 2026 ($234.69 close, -11.4% year to date on that file; 252-session closing high $266.23 on December 29, 2025; 252-session closing low $150.12 on June 22, 2026; closes of $186.67 at March 31, 2026 and $156.66 at June 30, 2026, a second-quarter change of -16.1%; change from June 30 to October 2 of +49.8% ((234.69 / 156.66) − 1); change from the 252-session low of +56.3% ((234.69 / 150.12) − 1), and the drawdown from the 252-session closing high is -11.8%. The series in our price file begins June 1, 2021 at $236.20.
- Market context sources: Wall Street Journal, Stocks to Watch Recap (October 12, 2026; Salesforce shares rose 2.1% after Bank of America's upgrade to buy — checked October 13, 2026); the Bank of America upgrade (October 12, 2026; underperform to buy, target raised from $160 to $285 against a $229.13 prior close for a 24.48% implied upside, and a gap-up open at $236.65 — as reported by American Banking News and MarketBeat, October 12, 2026, both citing the BofA note via Benzinga); the analyst register (consensus Moderate Buy with an average target of $278.12, from 3 strong buys, 31 buys, 14 holds and 2 sells — MarketBeat counts as cited by American Banking News, October 12, 2026); the fiscal second-quarter 2027 print (revenue $11.35 billion, up 11% year over year, against an $11.32 billion consensus; adjusted earnings of $5.90 a share against a $3.27 consensus; full-year revenue outlook raised to $46.1–$46.4 billion; a new AI partnership with Anthropic — as reported in Benzinga's investors'-radar roundup via TradingView, checked October 13, 2026). Figures we could not confirm against two sources were left out.
- CRM is in the GetCoattail stock-page universe: Salesforce, Inc. (CRM) stock page. Series data: crm_lens_data.csv · crm_short_interest_series.csv. Earlier audits: Lululemon · Gilead Sciences · IREN.
Past patterns are not a promise of future results. For education only — not investment advice.
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history
- v1.0 — October 13, 2026: first publication.