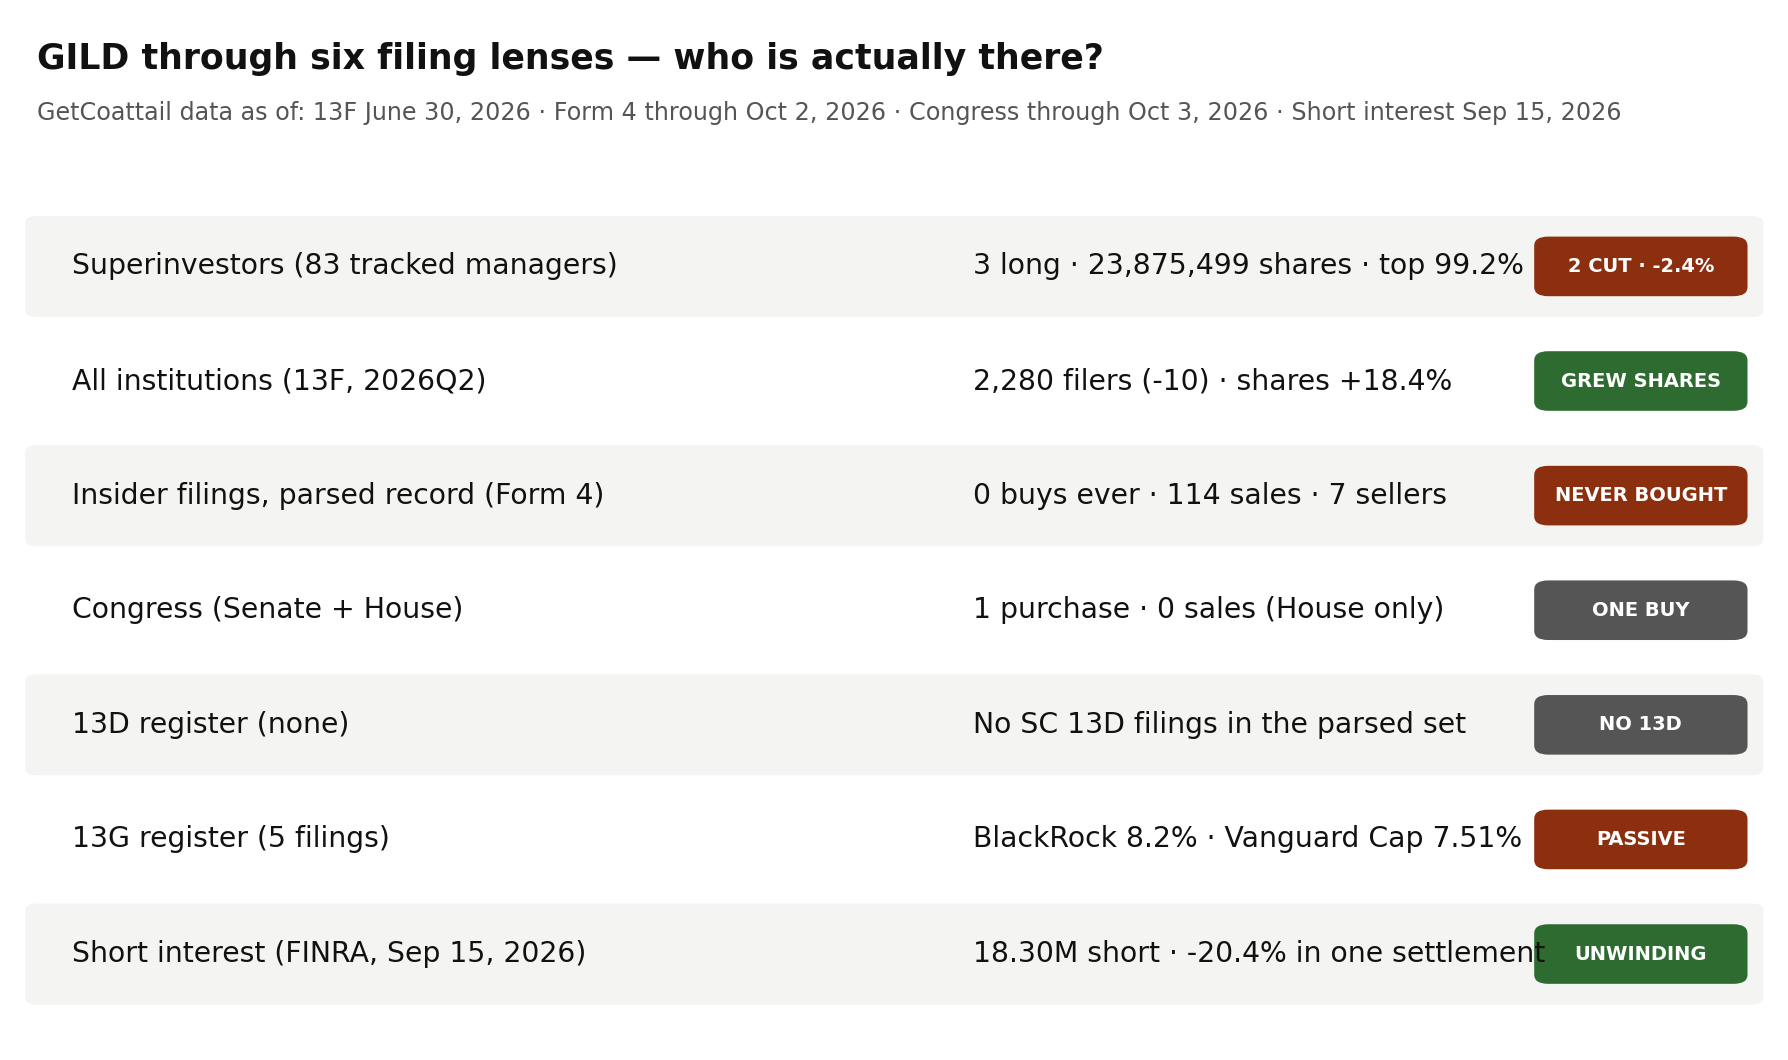
GetCoattail Research — Gilead Sciences is the HIV and antiviral drugmaker whose second quarter, reported August 3, 2026, paired 10.6% revenue growth and raised full-year guidance with a headline earnings loss driven by acquisition-related costs. The filings describe a far thinner register than the growth story suggests: three tracked superinvestors hold it, one of them is 99.2% of the cohort, insiders have recorded no open-market purchase anywhere in the parsed record against 114 sales, Congress records a single House purchase, and the borrow has fallen for five settlements in a row.
Start with the narrative. Gilead reported second-quarter 2026 results on August 3: revenue of $7.80 billion, up 10.6% year over year and ahead of a $7.40 billion consensus, with a diluted loss of $6.75 a share that was narrower than the $7.25 loss consensus expected and that coverage attributed to acquisition-related costs. The operating engine was HIV: HIV product sales rose 12% to $5.7 billion, Biktarvy sales reached $3.8 billion, and management raised full-year 2026 total product sales guidance to between $30.10 billion and $30.40 billion while lifting its HIV growth outlook to 9% to 10%. The analyst register is constructive but no longer unanimous: MarketBeat's count lists 23 Buy ratings and six Hold ratings among 29 analysts, a Moderate Buy consensus with an average target of $158.78, and on October 1 Zacks Research cut its rating from Strong Buy to Hold. The stock itself, on our own price file — which ends October 2 — closes GILD at $144.74, down 7.1% from its 252-session closing high of $155.80 set on February 11, 2026, up 17.9% year to date, and up 30.9% from its 252-session closing low of $110.56 set on October 2, 2025. MarketBeat's October 12 list of biotech stocks to watch — ranked on recent dollar trading volume — placed Gilead third among five names. The next scheduled test of the story is the third-quarter print expected later in October; the next test of the registers below is the third-quarter 13F season closing in mid-November.
Now the filings. For GILD — the fifty-eighth Filing Tape audit — the tape shows a three-name tracked cohort that is effectively a single position, a broad register that added 171,182,967 reported shares while losing ten filers, a 5% register of five passive-complex filings, an insider record with no purchases at all in the parsed coverage, a congressional record consisting of one House purchase, and a borrow that has fallen in each of the last five settlements.
Lens 1: the superinvestors — three holders, and one of them is the register
We track 83 large, mostly long-only managers whose 13F portfolios we collect directly from SEC EDGAR. As of June 30, 2026, 3 held GILD long — no option rows — totalling 23,875,499 shares worth $3,016,430,544. The direction count, on the collection's own labels, is two decreases and one unchanged — and the collection's exit list holds no GILD rows at all. The cohort total moved from 24,455,372 shares at March 31, across 3 filing rows, to 23,875,499 at June 30, across the same 3 rows, a change of -2.37%, a difference of -579,873 shares.
The register's centre of gravity is not just one holder; it is nearly the whole register. Dodge & Cox Funds holds 23,677,567 shares worth $2,991,423,815, a 1.57% portfolio weight — 99.2% of the tracked cohort's GILD shares — flagged decreased by 2.4%, and here the label and the filing continuity agree: the pipeline's March 31 file already carries the position at 24,250,826 shares, so the position shrank in the quarter rather than appearing in it. In fact every one of the three continuing holders' labels agrees with its continuity change this quarter (see methodology). Strip Dodge & Cox out and the rest of the cohort fell from 204,546 shares to 197,932 — -3.2% — in the quarter the price fell 9.3%. The second holder, John Rogers - Ariel Investments, holds 195,657 shares worth $24,719,305, decreased 3.3%. The third, Mairs & Power Funds, holds 2,275 shares worth $287,424, unchanged. That is the entire tracked register: three names, no new positions, no exits, and two of the three trimming. The cohort's implied price, $126.34 per share, sits exactly on the June 30 close of $126.34. The price fell from $139.37 at March 31 to $126.34 at June 30, a change of -9.3% — this register held 2.37% fewer shares at the end of that fall than at the start of it.
Lens 2: institutions — ten fewer filers, 171.2 million more shares
Zoom out to the whole 13F market and the register moved in opposite directions on its two counts. At June 30, 2026, 2,280 institutions reported positions, down 10 from 2,290 at March 31 (-0.44%), and 2,273 of them reported long positions. Reported shares rose 18.42%, from 929,355,428 to 1,100,538,395 shares — 171,182,967 more shares than the prior quarter. Reported aggregate value rose 8.61% to $134,797,831,479; the aggregate includes option rows, so we headline filer and share counts and label dollars "reported" (see methodology). Here the implied value per share, $122.48, sits 3.1% below the June 30 close of $126.34 — a gap, printed as found, and one more reason to headline the share count rather than the dollars: the share count rose 18.42% while the filer count fell by ten, in the same quarter in which the tracked cohort cut 2.37% and the price fell 9.3%.
Lens 3: the 5% register — five filings, all passive-complex paper
Our full parse holds five SC 13D/G filings for GILD — two SC 13G filings and three SC 13G/A amendments, and no SC 13D of any kind in the parsed set, six reporting-person rows across six names, the most recent filed April 29, 2026. The register's maximum is an older row: in an SC 13G/A filed April 24, 2025, BlackRock, Inc. prints 101,739,273 shares (8.2%) as of March 31, 2025. In an SC 13G/A filed May 13, 2025, Capital World Investors prints 53,834,873 shares (4.3%) as of March 31, 2025. In an SC 13G filed February 5, 2026, FMR LLC prints 65,539,476.75 shares (5.3%) as of December 31, 2025, and Abigail P. Johnson prints the same 65,539,476.75 shares (5.3%) in the same filing — a joint reporting row for the same stake, not a second stake. The Vanguard complex then re-papered, as this series keeps meeting: in an SC 13G/A filed March 26, 2026, The Vanguard Group prints 0 shares (0.0%) as of March 13, 2026, and in an SC 13G filed April 29, 2026, Vanguard Capital Management prints 93,327,127 shares (7.51%) as of March 31, 2026. That is the whole 5% register in our parsed coverage: five filings, all index-complex paper, and no activist paper at all. Read as filed — the rows are reported exactly as filed, never summed — the register describes passive complexes holding and re-papering large stakes, and nothing else.
Lens 4: insiders — no purchases in the parsed record, 114 sales
The parsed Form 4 record holds 138 filings through October 2, 2026. Across the whole record, open-market purchases total 0 transactions — while sales total 114 transactions, totalling 1,079,822 shares and $133,500,519.20, by seven sellers, 100 of the transactions recorded as officer sales. The last year holds 82 filings and no purchases at all, against 79 sales totalling 639,537 shares and $87,588,707.94 by seven sellers. The last 90 days hold 18 filings, no purchases, and 26 sales totalling 111,000 shares and $15,720,129.25 by five sellers. Our site's insider aggregate, compiled as of October 13 over its own later 90-day window, prints 24 sales totalling $13,501,621.75 by five sellers — a different count from the full parse's 26 over its window ending October 2, printed here as found rather than reconciled away; the two collections agree on the point that matters to this lens, which is that purchases are zero in both. We assign no motives to any of it; a tape with sales on one side and nothing on the other, across the entire parsed record, is the fact.
Lens 5: Congress — one purchase, and it is the whole record
The congressional record we maintain is as thin as the superinvestor register, and points the other way. The combined record (as of October 3, 2026) carries a GILD row printing 1 purchase and 0 sales, across one member, with the most recent purchase dated May 6, 2026. The House aggregate (as of October 3, 2026) prints the same 1 purchase and 0 sales for one member, dated May 6, 2026, and the Senate aggregate (as of October 1, 2026) carries no GILD row at all — so the combined line is the House line alone. One recorded purchase, no recorded sales, in either chamber's record as this site maintains them.
Lens 6: short interest — 18,304,875 shares, falling for five settlements
FINRA's files carry the borrow across 137 settlements, from January 15, 2021. As of September 15, 2026 — the most recent settlement — 18,304,875 GILD shares were sold short, with days-to-cover of 3.65. The latest step was the largest of the recent run: the reading fell 20.44% from the prior settlement's 23,007,029 shares on August 31, 2026, completing five consecutive declines — 25,261,911 on July 15, then 24,385,621, 23,183,970, 23,007,029 and 18,304,875. The top of this series is old: the peak is 28,642,716 shares on April 30, 2021, a fact we verified by taking the maximum across the whole series, and the latest reading sits 36.1% below it. Against September 15, 2025 the latest reading is up 0.3% from 18,249,455 shares — essentially flat over a year, despite the recent five-step fall. Against the fundamentals file's 1,239,955,155 shares outstanding, that is 1.48% of the share count. The June 30, 2026 settlement — the date the 13F lenses snapshot — printed 25,484,358 shares; the latest reading sits 28.2% below it. The series minimum is 14,155,841 shares on July 29, 2022; the series' own first settlement, on January 15, 2021, printed 22,373,677 shares — above the latest reading.
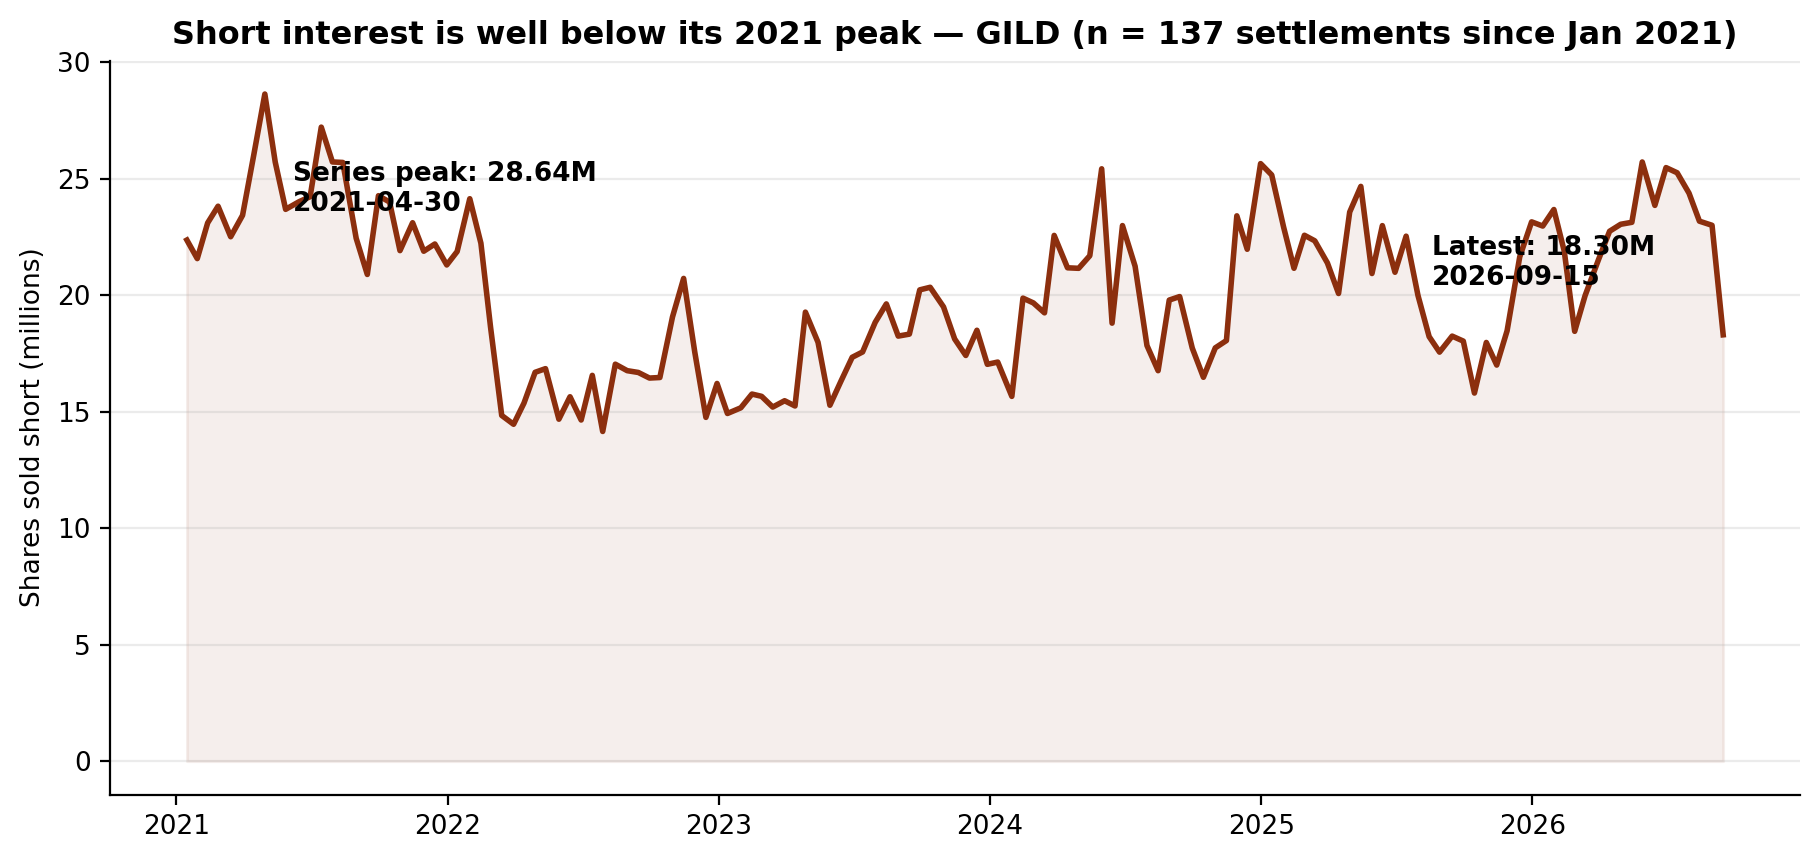
The borrow peaked in April 2021, before every other lens in this audit existed in its current form — and its last five settlements have all fallen.
The gap, stated plainly
The narrative describes a drugmaker whose core franchise is still growing: second-quarter revenue of $7.80 billion up 10.6%, HIV sales of $5.7 billion up 12%, full-year product sales guidance raised to between $30.10 billion and $30.40 billion, a Moderate Buy consensus averaging $158.78 — and a stock up 17.9% year to date on our price file, with one Hold downgrade in October as the only visible crack. The tracked superinvestors held 23,875,499 shares at June 30 across three holders, having cut 2.37% in a quarter when the price fell 9.3%, with two decreases, one unchanged, no new positions and no exits — and Dodge & Cox Funds at 99.2% of the cohort. The full market moved differently again: 1,100,538,395 reported shares, up 171,182,967, across 2,280 filers — ten fewer than the prior quarter, so the average reported position grew even as the filer count shrank. The 5% register printed five filings, all passive-complex paper: BlackRock at 8.2% on a March 2025 date, FMR LLC and Abigail P. Johnson at 5.3% each on the same joint December register, The Vanguard Group at zero on a March 2026 date, and Vanguard Capital Management at 7.51% on the March register. Insiders, across 138 parsed filings, recorded no purchases at all — against 114 sales totalling $133,500,519.20, 79 of them in the last year. Congress records one House purchase and no sales. And the borrow stands at 18,304,875 shares — flat over a year at +0.3%, down 36.1% from the series record it set in April 2021, at 3.65 days to cover and 1.48% of the share count, after five straight settlement declines. One plausible reading is that the registers are describing different GILD stories on different clocks: the broad register spent the second quarter concentrating — fewer filers holding more shares into a falling price — the tracked cohort is a single holder's position with two small satellites, the insider tape has only ever printed sales in this parsed record, the congressional tape's only print is a purchase, and short sellers spent the summer unwinding a borrow that is nevertheless exactly where it stood a year ago — all of it snapshot at June 30 or earlier, before the August earnings print that powered the current narrative existed as news. The record supports each clause separately; it does not say which register is right, and it cannot — the tracked cohort's whole position is a June 30 snapshot of 23,875,499 shares, taken a month before that print.
What would change the picture
Nothing above is a recommendation. It is a record. These are the filings that would change the description:
- 1. The 2026Q3 13Fs (filing window closing mid-November 2026). The tracked cohort held 23,875,499 shares at June 30 across three holders, after a -2.37% move with no new positions and no exits. Whether Dodge & Cox Funds' 23,677,567 shares — 99.2% of the cohort — shrink for a second straight quarter, and whether any fourth tracked manager appears, are the first things the next register will answer.
- 2. A first insider purchase in the parsed record. The parsed record holds 0 purchase transactions against 114 sales. A single new open-market purchase would be the first on this tape; another quarter of sales-only filings would extend a record that currently has no other side.
- 3. A second congressional print, in either direction. The combined congressional record prints 1 purchase and 0 sales (House 1 purchase, Senate no row), with the latest purchase on May 6, 2026. A first recorded sale, or a Senate print of any kind, would change a lens that currently consists of one House purchase.
- 4. An original SC 13D, or a 13G from outside the passive complexes. The 5% register in our parsed coverage holds five filings, all of them BlackRock, Capital World, FMR or Vanguard-complex paper. A first 13D in the parsed set — any filer declaring an active stake — would change this lens from passive holdings into something else.
- 5. Whether the borrow's five-settlement fall continues. Short interest stands at 18,304,875 shares, up 0.3% in a year and 36.1% below the April 30, 2021 series record of 28,642,716. The settlements that will print the third-quarter earnings week have not been published yet: a reading back above the June 30 settlement's 25,484,358 would restart the build, and a sixth straight decline would extend the unwind.
Until one of those prints, the record describes a stock held by three of our 83 tracked superinvestors — 23,875,499 shares, cut 2.37% in the quarter its price fell 9.3%, with one holder at 99.2% of the cohort — whose full market added 171,182,967 reported shares while losing ten filers, whose insiders have recorded no purchase anywhere in the parsed record against 114 sales, whose congressional register records a single House purchase and no sales, and whose borrow has fallen for five settlements while standing almost exactly where it stood a year ago — all of it snapshot at June 30, before the earnings print the growth story rests on.
Related reading: Seventeen of 83: One Holder Is 69.0% of the Superinvestors' UnitedHealth Stake. The Cohort Cut 11.8% as the Price Rose 53.6%. — Filing Tape #57; Fifteen of 83: Ten Superinvestors Cut JPMorgan in Q2. Its Insiders Have Never Bought a Share. — Filing Tape #56; Zero of 83: The Superinvestors Aren't in IREN — Filing Tape #1. GILD's own page: Gilead Sciences, Inc. (GILD) on GetCoattail.
Methodology and data notes
- Superinvestor lens: 83 managers collected directly from SEC EDGAR Form 13F (managers_13f collection), positions as of June 30, 2026; GILD identified by CUSIP 375558103. Three distinct managers hold long positions totalling 23,875,499 shares; all three reported rows are long (no put or call rows); the direction count on the collection's labels is two decreased and one unchanged, and the collection's exit list contains no GILD rows. Quarter-to-quarter cohort totals (24,455,372 shares at March 31 across 3 filing rows; 23,875,499 shares at June 30 across 3 filing rows; change -2.37%) are from the site pipeline's holdings files on the same CUSIP basis in both quarters, and the pipeline's second-quarter share and value totals match the EDGAR collection's long totals exactly (differences of 0 shares and $0). Per-holder quarter changes are matched by filing continuity across the two pipeline files: for all three continuing holders they agree with the EDGAR collection's own percentage labels (Dodge & Cox Funds 24,250,826 → 23,677,567 = -2.4%; John Rogers - Ariel Investments 202,271 → 195,657 = -3.3%; Mairs & Power Funds 2,275 → 2,275 = 0.0%). Two of the pipeline rows carry no manager name in the file's CIK map, so continuity for those rows is matched on share counts and accession numbers rather than names. This audit computes the cohort's ex-largest-holder change on the continuity basis (204,546 shares at March 31 — the cohort total less the 24,250,826-share row — to 197,932 at June 30, -3.2%). Dodge & Cox Funds' share of the cohort is 99.2% = 23,677,567 / 23,875,499.
- Full-market lens: SEC Form 13F Data Sets full-market aggregation. The primary table is the full13f collection's by-ticker file (holders = distinct filers reporting the CUSIP; 2,273 reported long positions out of 2,280 filers). GILD reports under a single CUSIP spelling, 375558103, and the backfill fixtures' by-CUSIP file carries the same row — the cross-check matches on every field (holders, shares, reported value, prior holders and prior reported value). The by-ticker file's entered/exited fields (1,640 and 1,650, a net of -10 that matches the change in holder count) are gross flows, so this audit headlines the net change. Reported-value caution: the aggregate value ($134,797,831,479 over 1,100,538,395 shares) implies $122.48 per share against a June 30, 2026 close of $126.34 in our price file, a gap of -3.1% — printed here as found. The aggregate sums the VALUE of every information-table row — including put and call option rows — while the share count covers long common-stock rows only, so we headline filer and share counts and label dollar values "reported."
- Insider lens: full-parse Form 4 aggregation (agg_by_ticker), record as of October 2, 2026 (138 filings). Sale and purchase counts are transaction-code counts (S and P) in non-derivative rows; grants and exercises are not counted as purchases, and one filing can contain many transaction rows. Purchase transactions total 0 across the parsed record — and zero in the last year (82 filings) and in the 90-day window (18 filings). Sale transactions total 114 across the record (1,079,822 shares, $133,500,519.20, seven sellers, 100 of them recorded as officer sales); the last year holds 79 (639,537 shares, $87,588,707.94, seven sellers) and the 90-day window holds 26 (111,000 shares, $15,720,129.25, five sellers). The site's insider aggregate (compiled as of October 13, 2026, over a 90-day window ending on its own compile date) prints 24 sales totalling $13,501,621.75 by five sellers — a different 90-day count from the full parse, because the two windows end on different dates; both collections print zero purchases. "Never bought" in this audit is scoped to this parsed record, whose 138 filings are the coverage stated here.
- 13D/G lens: full-parse SC 13D/G parsed filings (5 filings matching issuer CIK 882095 on CUSIP 375558103, 6 reporting-person rows across 6 names: two SC 13G filings and three SC 13G/A amendments, no SC 13D filings), filings through April 29, 2026. The site aggregation's by-ticker file carries the same totals (5 filings, 6 reporters, latest filing April 29, 2026, maximum 8.2%, total reported 379,980,226.5 shares), so the aggregate and the parse agree here — with one caveat: the aggregation's total sums reporting-person rows, and the FMR LLC and Abigail P. Johnson rows in the February 5, 2026 SC 13G report the same 65,539,476.75-share stake, so that total double-counts one stake and is not used in the article. BlackRock, Inc.'s row (101,739,273 shares at 8.2% as of March 31, 2025, filed April 24, 2025, SC 13G/A), Capital World Investors' row (53,834,873 shares at 4.3% as of March 31, 2025, filed May 13, 2025, SC 13G/A), the FMR LLC / Abigail P. Johnson rows (65,539,476.75 shares at 5.3% each as of December 31, 2025, filed February 5, 2026, SC 13G), The Vanguard Group's row (0 shares at 0.0% as of March 13, 2026, filed March 26, 2026, SC 13G/A) and Vanguard Capital Management's row (93,327,127 shares at 7.51% as of March 31, 2026, filed April 29, 2026, SC 13G) are reported as filed, under the reporting-person names exactly as they appear. No rows are summed in the article, because aggregation totals across these rows would add different dates — and, here, one duplicated stake — together. No reason for any change is asserted — the filings themselves are the record. The parsed coverage for this issuer holds these five filings; a 5% holder that has not filed in the covered window would not appear here.
- Congress lens: Senate PTR archive and House PTR archive as maintained on this site. The combined record (as of October 3, 2026) prints 1 purchase and 0 sales for GILD, across one member, with the most recent purchase on May 6, 2026; the House aggregate (as of October 3, 2026) prints the same 1 purchase and 0 sales across one member, most recent purchase May 6, 2026; and the Senate aggregate (as of October 1, 2026) carries no GILD row at all — the combined line is the House line alone, and there is no chamber sum to check beyond that identity.
- Short interest lens: FINRA Equity Short Interest files (biweekly settlement dates), collected directly from FINRA's public distribution. The published series covers 137 settlements from January 15, 2021 (22,373,677 shares) to September 15, 2026. The latest reading is 18,304,875 shares on September 15, 2026, which sits 36.1% below the series maximum of 28,642,716 shares on April 30, 2021 (verified by a maximum query over the series, not read off the latest row), up 0.3% from the September 15, 2025 reading of 18,249,455 and down 20.44% from the prior settlement (23,007,029 on August 31, 2026). The last five settlements fall in a row (25,261,911; 24,385,621; 23,183,970; 23,007,029; 18,304,875). The series minimum is 14,155,841 shares on July 29, 2022. FINRA publishes each settlement about two weeks after the fact, so the third-quarter earnings print expected later in October 2026 is not yet in this series. The share-count ratio (1.48%) uses the fundamentals file's shares-outstanding figure below.
- Fundamentals note: our fundamentals collection carries GILD's revenue of $29,443,000,000 labelled fiscal 2025, its net income of $8,510,000,000 labelled fiscal 2025, and its assets of $59,023,000,000 labelled fiscal 2025. The file is marked ok for this name, with no missing fields: shares outstanding of 1,239,955,155 (as of July 31, 2026 in the file, sourced in the file to the issuer's reported shares-outstanding figure) and a file-computed market value of $178,838,726,707.99. The file's price for the name is $144.23 as of October 6, 2026; our daily-close file ends October 2, 2026 at $144.74, and we keep the two files' figures separate rather than blending them.
- Prices: our own daily-close file for GILD through October 2, 2026 ($144.74 close, +17.9% year to date on that file; 252-session closing high $155.80 on February 11, 2026; 252-session closing low $110.56 on October 2, 2025; closes of $139.37 at March 31, 2026 and $126.34 at June 30, 2026, a second-quarter change of -9.3%; change from June 30 to October 2 of +14.6% ((144.74 / 126.34) − 1)). The drawdown from the 252-session closing high is -7.1%, the gain from the 252-session closing low is +30.9%, and the series in our price file begins June 1, 2021.
- Market context sources: MarketBeat, Biotech Stocks To Consider — October 12th (October 12, 2026; five biotech names ranked on recent dollar trading volume — Moderna, AbbVie, Gilead Sciences, Danaher and First Tracks Biotherapeutics — checked October 13, 2026); the second-quarter results (reported August 3, 2026; revenue $7.80 billion, up 10.6% year over year, against a $7.40 billion consensus; diluted loss of $6.75 a share against a $7.25 consensus loss, with coverage attributing the loss to acquisition-related costs; HIV product sales $5.7 billion, up 12%; Biktarvy sales $3.8 billion; full-year 2026 total product sales guidance raised to $30.10–$30.40 billion and the HIV growth outlook raised to 9%–10% — as reported by multiple outlets in August–October 2026); the analyst consensus (Moderate Buy, 23 Buy and six Hold ratings among 29 analysts, average target $158.78 — MarketBeat data as reported October 2026); the Zacks Research downgrade (Strong Buy to Hold, reported October 1, 2026). Figures we could not confirm against two sources were left out; in particular, previews disagreed on the exact late-October date of the third-quarter report, so this audit says only that it is expected later in October.
- GILD is in the GetCoattail stock-page universe: Gilead Sciences, Inc. (GILD) stock page. Series data: gild_lens_data.csv · gild_short_interest_series.csv. Earlier audits: UnitedHealth Group · JPMorgan Chase · IREN.
Past patterns are not a promise of future results. For education only — not investment advice.
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history
- v1.0 — October 13, 2026: first publication.