GetCoattail Research — The Filing Tape #164. Owens Corning has been one of the most searched-for stocks on Zacks.com lately, where it carries a Rank #4 (Sell). The filings show 4 tracked holders of 147, a full market holding 18.35% more shares on 67 more filers, and an insider record with no open-market purchase at all.
The Hype
The attention is search traffic with a bearish label attached. Zacks reports that Owens Corning "has been one of the most searched-for stocks on Zacks.com lately," with shares down 8.7% over the past month against no change in the Zacks S&P 500 composite, while its Building Products - Miscellaneous industry lost 0.3%. Zacks, October 22, 2026 The same note shows why the searches may be argument rather than enthusiasm: the current-quarter consensus is $2.98 a share, down 18.8% year over year and revised down 26.2% in 30 days; the full-year estimate is $9.59, down 20.4%; the next-year estimate is $10.72, up 11.8%; and Zacks assigns Rank #4 (Sell) even as its Value Style Score is graded A. The last reported quarter printed revenue of $2.76 billion, up 0.3%, and EPS of $3.93 against $4.21 a year earlier — beating consensus by 3.16% and 28.43%. Our own price file, which ends October 2, shows the longer arc: the stock rose 46.9% in Q2 ($108.22 on March 31 to $158.96 on June 30), then fell 25.5% to $118.36 at October 2 — 25.5% below the 252-day high close of $158.96, which is the June 30 close itself, and 20.4% above the low close of $98.28 (November 20, 2025).
The Tape
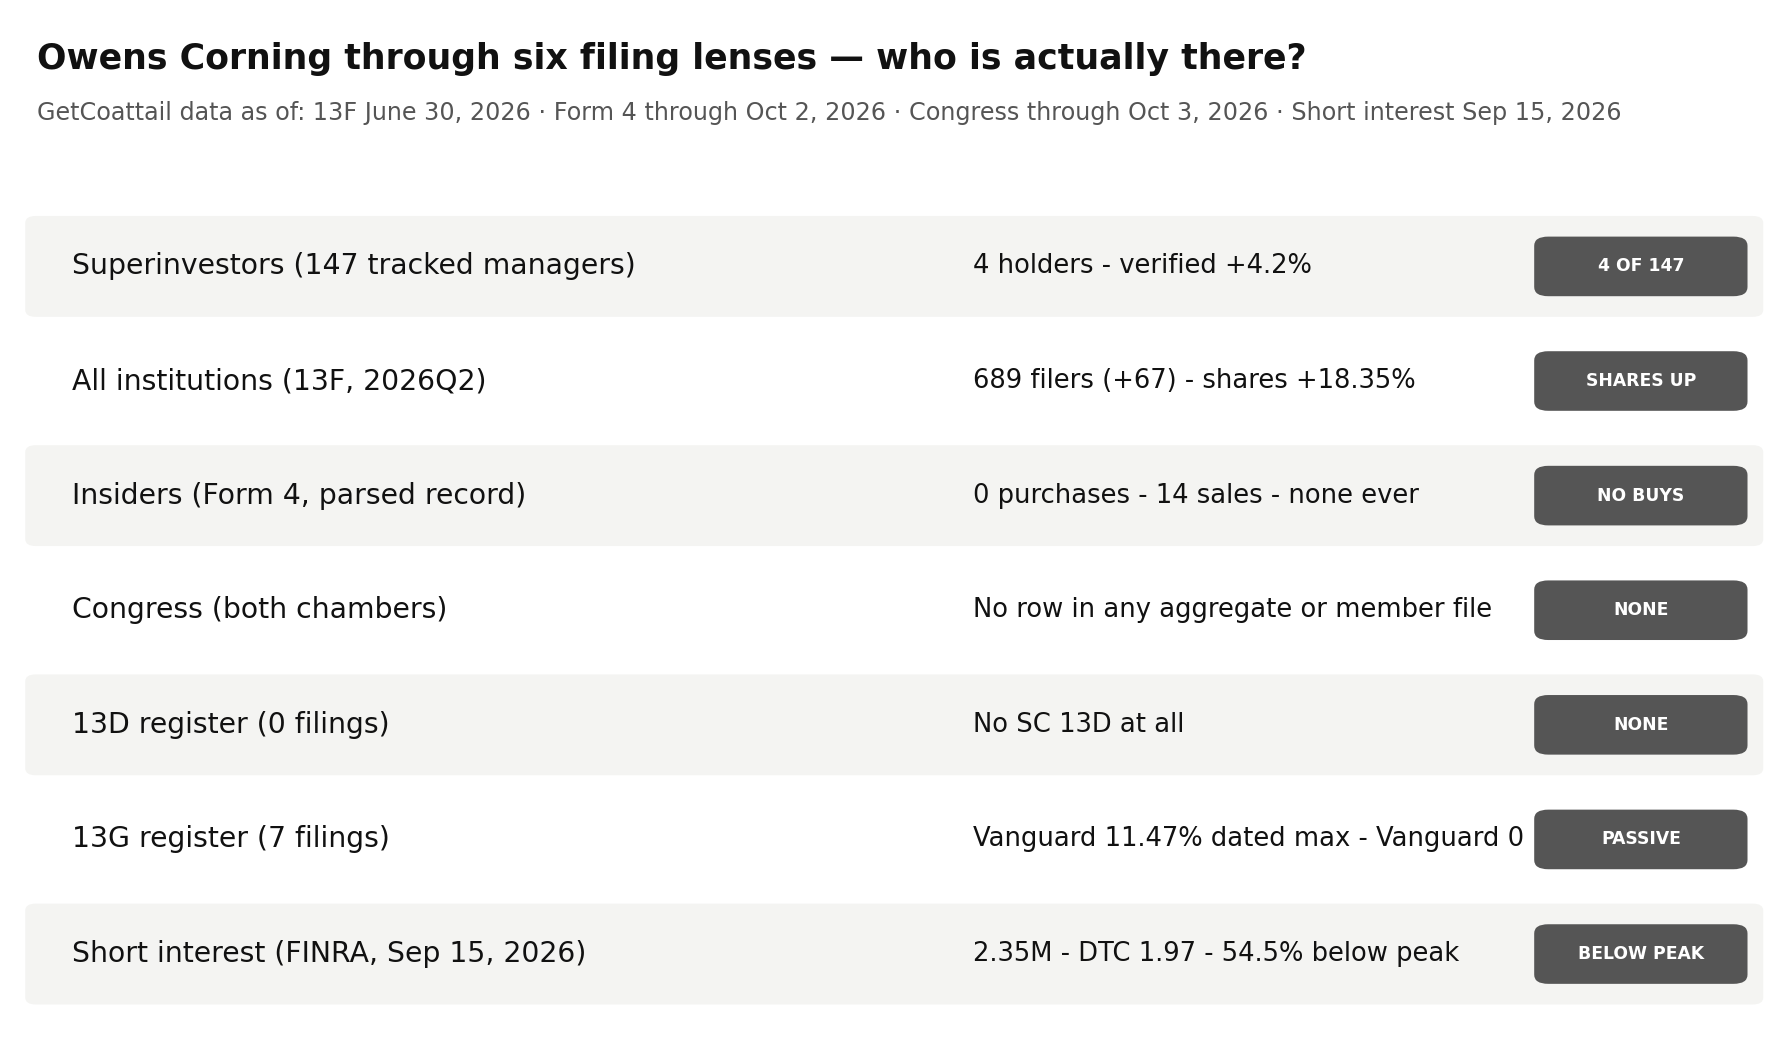
For Owens Corning, the one hundred and sixty-fourth Filing Tape audit, the tape shows 4 tracked managers whose verified continuing positions grew 4.2%, a full market that added 12,866,698 shares across 67 more filers, an insider record with zero purchases against 14 sales, no congressional row in either chamber, a 5% register that is entirely passive SC 13G paper, and a borrow of 2.98% of a measured share count that has fallen by more than half from its March peak.
| Lens | As of | What the filings show | Direction vs prior period |
|---|---|---|---|
| Superinvestors (13F) | Jun 30, 2026 | 4 holders of 147 tracked managers hold 3,826,373 shares; no NEW labels | Verified continuing holders +4.2% (3,672,270 → 3,826,373 shares); register total +4.2% |
| All institutions (13F) | Jun 30, 2026 | 689 filers; 82,999,508 shares; reported value $12,513,557,829 | Filers +67; shares +18.35%; reported value +74.84% |
| Insiders (Form 4) | Oct 2, 2026 | Last 90 days (by filing date): 0 purchases, 1 sale; parsed record: 0 purchases, 14 sales | No purchase appears in any window of the parsed record |
| Congress | Oct 3, 2026 | No row in the combined, House or Senate aggregates | No member-file row in either chamber |
| 13D/G | Jun 4, 2026 | 7 parsed filings, all in the SC 13G family; register maximum 11.47% as printed | Latest filing, Jun 4, 2026, prints BlackRock at 10.0% as of May 31, 2026 |
| Short interest (FINRA) | Sep 15, 2026 | 2,352,518 shares; 1.97 days to cover; 2.98% of the measured share count | Up 17.0% from a year ago; down 54.5% from the Mar 31, 2026 series maximum |
Lens 1 — the superinvestors: four holders, one of them 54.4% of the stake. The collection holds 147 managers (144 at June 30; 3 early filers at September 30). The June 30, 2026 register is 4 distinct managers holding 3,826,373 shares worth $608,124,863, long only, with no option rows. The largest is Christopher Davis - Davis Advisors, 2,081,213 shares, 54.4% of the cohort, at a 1.42% weight, labelled DECREASED at −0.9%. Behind it sit Bill Nygren - Oakmark Funds (1,095,517 shares, 28.6%, INCREASED +19.7%), Harry Burn - Sound Shore (584,629 shares, DECREASED −1.3%, at the cohort's highest weight, 2.86%) and Guinness Asset Management (65,014 shares, INCREASED +2.2%) — two decreases, two increases, no new position and no exit. Every label verifies under both pairing methods: the four held 3,672,270 shares at March 31 and 3,826,373 at June 30, a verified change of +4.2% (+154,103 shares), in a quarter when the price rose 46.9%. The growth is one holder's: Oakmark added 19.7% while Davis and Sound Shore trimmed about 1% each. No September early filer holds the name. The June cohort's implied price is $158.93, against the $158.96 close (−0.02%): three holders imply $158.96 exactly, and Davis implies $158.90. At 4.61% of reported institutional shares the cohort is a small sample of this register. 13F figures are as of June 30, 2026, published up to 45 days later.
Lens 2 — institutions: 67 more filers, 12.9 million more shares. At June 30, 2026, 689 institutions reported positions on the name's single CUSIP, up 67 from 622 at March 31 (+10.77%); 685 are long. Reported shares rose 18.35% to 82,999,508 (+12,866,698 shares), while reported value rose 74.84% to $12,513,557,829, labelled "reported" because the aggregate includes option rows (methodology). The aggregate implies $150.77 against the $158.96 close (−5.15%) — a gap too large to smooth over, reported rather than hidden. The share count is the cleaner measure: nearly a fifth more stock reported by a larger crowd, in the same quarter the tracked cohort grew 4.2% and the price rose 46.9%. The value jump is mostly the price: shares rose 18.35% while the quarter-end price rose 46.9%.
Lens 3 — insiders: no purchase on the whole record. The parsed Form 4 record holds 190 filings (January 22, 2025 – September 17, 2026), inside windows running through October 2, 2026. The last 90 days (a filing-date window, per the aggregate's own definition) hold 17 filings, no purchase-coded rows and one sale-coded row: Rachel Barthelemy Marcon, whose Form 4 title reads "President, Doors," sold 900 shares for $129,663.00 on August 28, 2026 at $144.07 a share, filed September 1, 2026 — an officer row. The last year holds the same pattern at slightly larger scale: 3 sale-coded rows across 3,526 shares worth $447,044.22, all officer rows by two sellers — Mari Doerfler, vice president and controller, sold 1,926 shares on May 8, 2026, and Marcon sold 700 shares on May 28, 2026 and the 900 above. The full parsed record holds exactly 14 sale-coded rows and no purchase-coded row in any window — 25,056 shares worth $4,239,035.03 across eight sellers, 13 of the 14 rows officer rows; 96 filings dated before October 3, 2025 hold the other 11 sales. Within this record, which begins in January 2025, the purchase column is empty, stated with that record's span.
Lens 4 — Congress: no row. The combined aggregate (as of October 3, 2026) carries no row for this ticker, and neither do the House aggregate, the Senate aggregate, the House member file or the Senate member file. There is nothing to split by party, chamber or direction: as collected, this lens is blank, reported as blank rather than estimated.
Lens 5 — the 5% register: entirely passive, and its maximum is dated March 2025. Our full parse holds 7 SC 13D/G filings: 2 SC 13G and 5 SC 13G/A amendments, and no SC 13D at all, carrying 7 reporter rows from 4 reporting entities. The register maximum as printed is The Vanguard Group, 9,815,685 shares and 11.47%, in an SC 13G/A filed April 30, 2025 as of March 31, 2025 — a share count that is 11.8% of the 82,999,508 shares the full 13F market reports for the same CUSIP, so the percentage and the count sit in the same range on this name, unlike the flagged mismatch in the prior audit. BlackRock, Inc. prints 9,200,211 shares and 10.8% as of March 31, 2025, then 7,872,227 shares and 9.6% as of December 31, 2025. The Vanguard Group prints 0 shares and 0.0% as of March 13, 2026, while two Vanguard entities print again at March 31, 2026 (Vanguard Capital Management, 4,243,450 shares and 5.27%; Vanguard Portfolio Management, 5,532,481 shares and 6.88%). The latest filing, June 4, 2026, prints BlackRock, Inc. at 8,069,391 shares and 10.0% as of May 31, 2026.
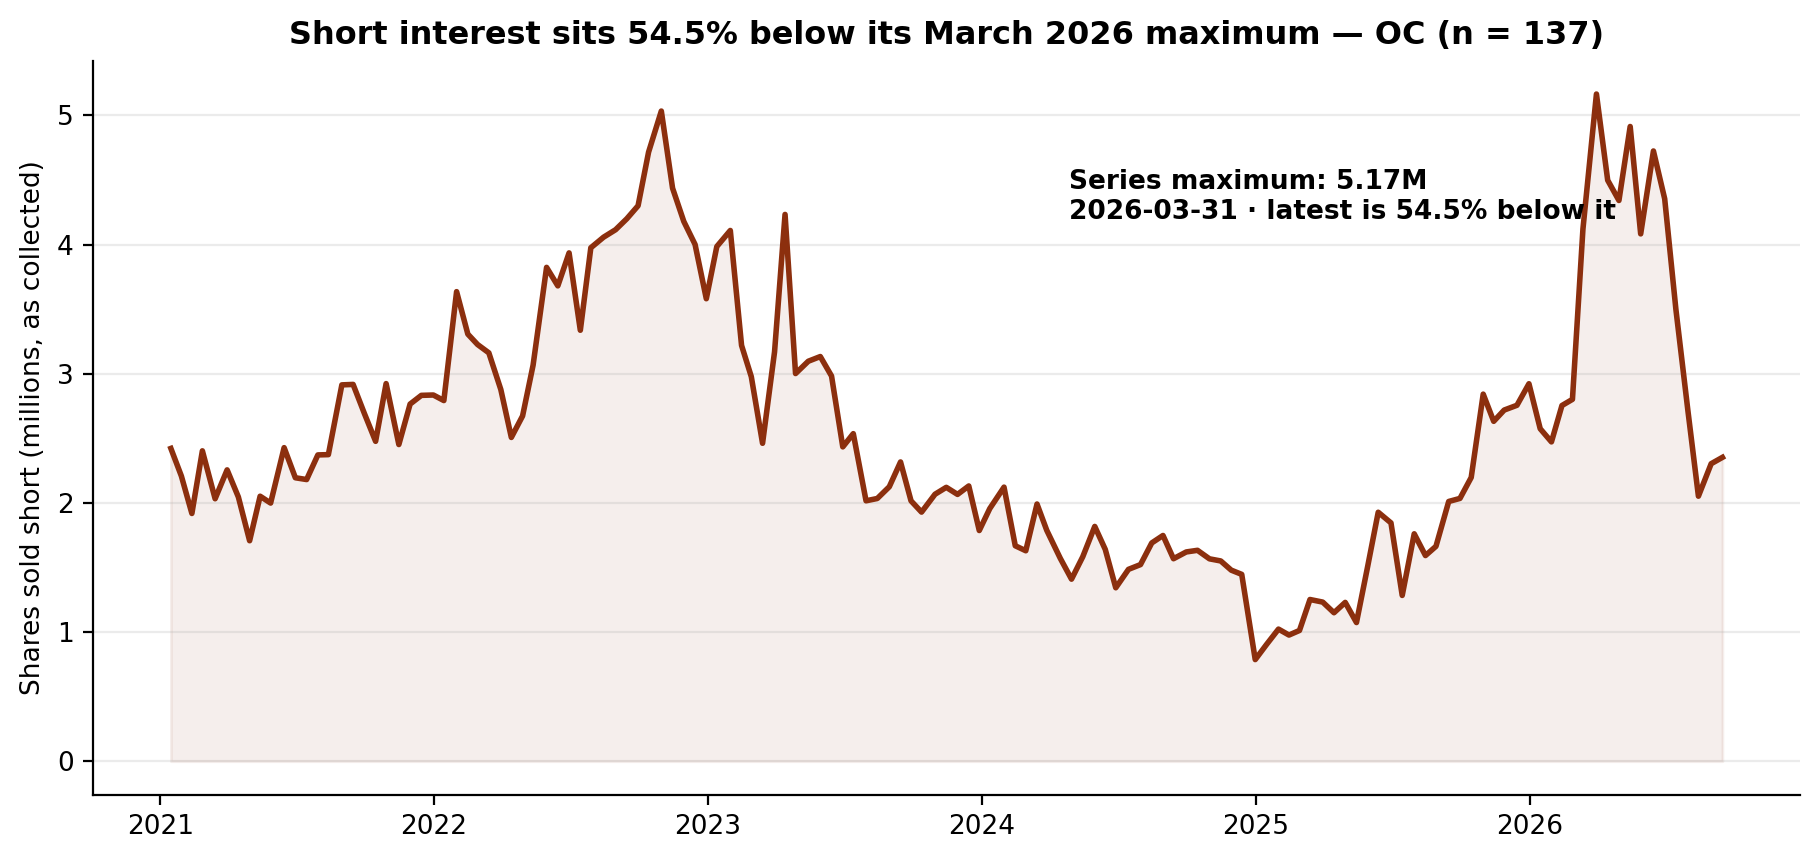
Lens 6 — short interest: 2.98% of a measured share count, halved from its March peak. The latest FINRA settlement, September 15, 2026, records 2,352,518 shares sold short at 1.97 days to cover, 2.98% of the share count in our fundamentals file (a measured period-end count, methodology). The borrow rose 2.13% from the prior settlement, sits 46.0% below the June 30, 2026 settlement (4,354,976 shares) and 17.0% above the year-ago settlement (2,010,961 shares). The series maximum is 5,165,894 shares at March 31, 2026, and the latest reading sits 54.5% below it; the minimum is 786,697 shares at December 31, 2024. The summer's path: 4,354,976 (June 30), 3,496,230 (July 15), 2,712,736 (July 31), 2,051,946 (August 14), 2,303,452 (August 31), 2,352,518 (September 15) — three settlements down from the June snapshot, then two small rebuilds.
The Gap
The search story is a Sell label on a falling tape: Rank #4, the current-quarter estimate cut 26.2% in a month, and a stock down 8.7% over the same month. The filings underneath describe the quarter before that fall, and they were busy in the other direction. In Q2, when the price rose 46.9%, the full market reported 18.35% more shares across 67 more filers, and the tracked cohort grew a verified 4.2% — though that growth is Oakmark's +19.7% alone, while the holder who is 54.4% of the cohort trimmed 0.9%. Since June the price has given back 25.5%, and the borrow has fallen 46.0% from its June 30 settlement and 54.5% from its March maximum. Congress has not touched the name in any aggregate we hold. The 5% register is passive paper only, its largest print more than a year old. And the insider record is this audit's emptiest buy column: 190 filings, 14 sales, and not one open-market purchase anywhere in the parsed record. One plausible reading is that the October search interest is a valuation argument about a downgraded name after a round trip — up 46.9%, then down 25.5% — while the record shows institutions arriving during the rise, tracked holders mostly waiting, insiders selling in small lots, and nobody in the filings buying at all.
What Would Change the Picture
Nothing above is a recommendation. These filings would change it:
- 1. The 2026Q3 13F season (filing window closing mid-November 2026). The baseline is 4 June holders with 3,826,373 shares, the continuing holders verified at +4.2%, Davis at 54.4% of the cohort, Oakmark's +19.7% increase, and no September early filer holding the name. Whether Davis adds after trimming in a +46.9% quarter, whether Oakmark keeps building, and whether any new tracked name enters after the 25.5% pullback would change this lens.
- 2. A first insider purchase — or a larger insider sale. The parsed record through the October 2 window end holds 0 purchases and 14 sales. A first purchase-coded row would populate an empty column; a sale materially larger than the recent 900-share lot would change the scale of this lens.
- 3. A first congressional trade. The combined, House and Senate aggregates and both member files hold no row for this ticker. Any recorded purchase or sale, in any amount band, would populate this blank lens.
- 4. A first SC 13D, or a fresh passive print above 11.47%. The register holds no SC 13D and its maximum print is dated March 31, 2025. An original SC 13D from any reporter, or a new SC 13G print above the Vanguard maximum, would change this lens.
- 5. Short interest above 5,165,894 shares, or below 2,051,946. Above the March 31, 2026 reading would set a new series high; below the August 14, 2026 settlement would resume the summer decline.
Methodology and data notes
- As-of & limits: The lenses rest on different clocks, none live: 13F is a June 30, 2026 snapshot published up to 45 days later; Form 4 windows run through October 2, 2026 (the last Owens Corning filing in the parsed record is itself dated September 17, 2026); Congress aggregates run through October 3, 2026 (Senate through October 1, 2026); 13D/G through June 4, 2026; short interest through September 15, 2026; the price file ends October 2, 2026. Ten limits are specific to this audit. First, the roster expanded before the recent audits — from 85 managers (83 filing) to 149 (147 filing) — so "of 147" counts are not comparable to earlier pieces' "of 83" figures. Second, this name's common stock carries a single CUSIP (690742101), and the full-market by-CUSIP row matches the by-ticker aggregate on every field — holders, long holders, shares, reported value, prior holders and prior reported value — so no CUSIP blending question arises. Third, the tracked register's change labels are verified, not taken on trust: all four continuing holders were verified by two methods that agree exactly — a total-value prefix pass and accession identity plus CUSIP-overlap pairing, each June filing paired to a unique March filing, with every label recomputing exactly and no fallback lookup needed. There is no NEW label to audit, no tracked exit, and no September early filer holding this name. The registers then reconcile with no remainder: the March 31 register holds 3,672,270 shares, equal to the verified continuing holders' 3,672,270; the June 30 register holds 3,826,373 shares, equal to the June cohort's 3,826,373, so the register change and the verified cohort change are the same +4.2%. Fourth, implied prices are near-exact on this name: the June cohort implies $158.93 against the June 30 close of $158.96 (−0.02%), three of the four holders imply $158.96 exactly, and Davis Advisors implies $158.90 — a small per-holder gap, reported rather than averaged away. Fifth, the full-market aggregate implies $150.77 against the June 30 close of $158.96 (−5.15%): the aggregate is a reported sum that includes option rows, so its implied price need not equal the close; the gap here is not small, and this audit uses filer counts and share counts as this lens's primary measures and reports the value as reported only. Sixth, the insider lens rests on a single aggregate bucket — this issuer's filings sit under one symbol spelling, "OC", with no case split — cross-checked against a row-level scan of all 190 parsed filings for the issuer (CIK 1370946): filing counts, transaction counts, share counts, officer-row counts and values reproduce exactly in every window, with a value difference of $0.00 in all three windows and no accession appearing under more than one symbol spelling. On that record, every insider implied-price check that applies passes: the 90-day implied sale price of $144.07, the one-year implied sale price of $126.79 and the full-record implied sale price of $169.18 each sit inside their filing-window close ranges; the record holds no purchase rows, so no implied-price check applies on the buy side in any window. The site's insider aggregate (dated October 22, 2026, a 90-day window ending that day) carries a row for this name — 0 purchases, 1 sale, $129,663.00, no last purchase, not flagged as a CEO buy — which matches the full parse's 90-day filing-date window (ending October 2, 2026) exactly; this audit uses the full parse, whose window is defined in the aggregate file itself. Form 4 windows in this audit are filing-date windows; the recent sale was transacted August 28, 2026 and filed September 1, 2026. Seventh, the congressional lens is an absence across five files: the combined aggregate, the House aggregate, the Senate aggregate, the House member file (transactions dated on or after April 1, 2026) and the Senate member file (same window) each carry no row for this ticker. That is an absence in the aggregates as collected, stated with their windows, not a claim about any individual member's complete disclosure history. Eighth, the 5% register's maximum print needs its date in full: the Vanguard Group SC 13G/A (filed April 30, 2025) prints 9,815,685 shares at 11.47% as of March 31, 2025, and that share count is 11.8% of the 82,999,508 shares the full 13F market reports for the same CUSIP at June 30, 2026, so on this name the printed percentage and the share count are in the same range and no mismatch flag applies. The register's cross-date share total of 44,733,445 is likewise an arithmetic sum of 7 reporter rows across different reporters and as-of dates, including one reporter's own 0-share print, and is not a current combined stake; each print is reported individually in the text. Parsed totals match the aggregates exactly, the register holds no SC 13D filing, and every filing is in the SC 13G family. Ninth, the short-interest series holds no step of 2x or more and no step to one-half or less (the largest step is 1.471x, at March 13, 2026; the smallest is 0.544x, at December 31, 2024), so the series carries no discontinuity on this measure across its span. No row carries a split flag; two rows carry a FINRA revision flag (June 15, 2021 and November 15, 2023). The issuer-name field reads "Owens Corning" at all 137 settlements, on a single market class (NYSE) throughout. The share count behind the short-interest percentage is 79,048,683 shares in our fundamentals file, and unlike a weighted-average fallback it is a measured count (the file's shares_source reads dei/EntityCommonStockSharesOutstanding and its shares_end reads "2026-07-31"), so the 2.98% figure rests on that measured denominator. Our price file records no single-day close move across the thresholds this audit normally treats as split patterns, and records no split factor for this name; the 252-day high close is the June 30, 2026 close itself, so the drawdown from the high and the pullback from the June snapshot are the same −25.5%. The company's fundamentals as collected print fiscal 2025 revenue of $10,103,000,000, net income of −$522,000,000 and assets of $12,980,000,000; those figures are reported as collected and are not used in any lens above. Every price statement from our own file is mechanical, a date and a close. The Zacks figures in The Hype — the search ranking, the past-month return and the consensus estimates — are that outlet's published figures, cited as such, not blended into file-based calculations.
- Market context sources: Zacks, October 22, 2026 (Owens Corning one of the most searched-for stocks on Zacks.com lately; past-month return −8.7% against no change in the Zacks S&P 500 composite; Building Products - Miscellaneous industry −0.3%; current-quarter consensus EPS $2.98, down 18.8% year over year, revised −26.2% over 30 days; fiscal-year consensus $9.59, down 20.4%, revised −5.4%; next fiscal year $10.72, up 11.8%, revised −11.6%; current-quarter sales consensus $2.6 billion, down 3.0%; fiscal-year sales $9.9 billion, down 2.0%, and next fiscal year $10.26 billion, up 3.6%; Zacks Rank #4 (Sell); Value Style Score A; last reported quarter revenue $2.76 billion, up 0.3%, EPS $3.93 against $4.21 a year earlier, revenue surprise +3.16% and EPS surprise +28.43%, EPS beats in three of the trailing four quarters and revenue beats in two). Google Trends US daily snapshot via Cyber Kendra, updated October 22, 2026 (top queries are sports and entertainment names; no stock query appears, so the Zacks trending-stock selection above is the fallback basis). Figures we could not confirm were left out; the external items above are reported figures from those outlets, not GetCoattail measurements.
- Owens Corning is in the GetCoattail stock-page universe: Owens Corning (OC) stock page. Series data: oc_lens_data.csv · oc_short_interest_series.csv. Earlier audits: Tyson Foods · First Solar.
Past patterns are not a promise of future results. For education only — not investment advice.
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history: v1.0 — October 23, 2026: first publication.