GetCoattail Research — The Filing Tape #172. RingCentral (RNG) jumped 13.53% in premarket trading on October 23, 2026, after reporting third-quarter non-GAAP earnings per share of $1.33 against $1.28 expected and raising its full-year outlook. The filings show 2 of 147 tracked funds holding 451,484 shares of RingCentral common stock, $17.6 million reported: Coatue Management is 91.1% of that stake and held exactly flat in Q2; Polen Capital Management is the one new name; insiders have never recorded an open-market buy in our parsed record; the full 13F market reported 18.25% more shares; and short interest sits 39.7% below its February 2026 peak — though it is up 4.6% from a year ago.
① The Hype
On October 23, 2026, RingCentral reported third-quarter 2026 results before the bell, and the premarket tape did the rest. Swingfolio's U.S. pre-market briefing put RNG.US at +13.53% — the largest gainer in its movers table — on "Q3 EPS $1.33 against $1.28 expected; raised full-year outlook." Seeking Alpha's gap-up premarket list the same morning had RingCentral (RNG) at +15.4%.
The company's announcement: third-quarter total revenue of $676.0 million, up 5.9% year over year; non-GAAP diluted EPS of $1.33, up from $1.13 a year earlier. StockStory's read put revenue at $676 million against analyst estimates of $667.4 million (a 1.3% beat) and adjusted EPS of $1.33 against estimates of about $1.27, and noted the company raised its full-year adjusted EPS guidance to a $5.10 midpoint. The company announcement's own guidance: full-year 2026 total revenue of $2.650 billion to $2.657 billion, non-GAAP EPS of $5.07 to $5.12, and free cash flow of $620 million to $630 million. One line of the press release deserves a pause: GAAP diluted EPS of $6.50 includes a $544.9 million benefit from a partial release of the valuation allowance — the GAAP print is dominated by a tax benefit, not by operations.
Our price file ends October 2, 2026, so we cannot verify the earnings-day move itself. Through that date, RNG closed at $78.28 — up 4.8% in Q2 ($37.19 to $38.98), up 171.1% year to date, up 100.8% since June 30, 1.9% below its September 24 high of $79.82, and 215.4% above its February 3 low of $24.82. The earnings pop sits on top of a stock that had already been climbing out of a very deep hole all year.
That is the story the market is reading. The filings tell their own version.
② The Tape
| Lens | As of | What the filings show | Direction vs prior period |
|---|---|---|---|
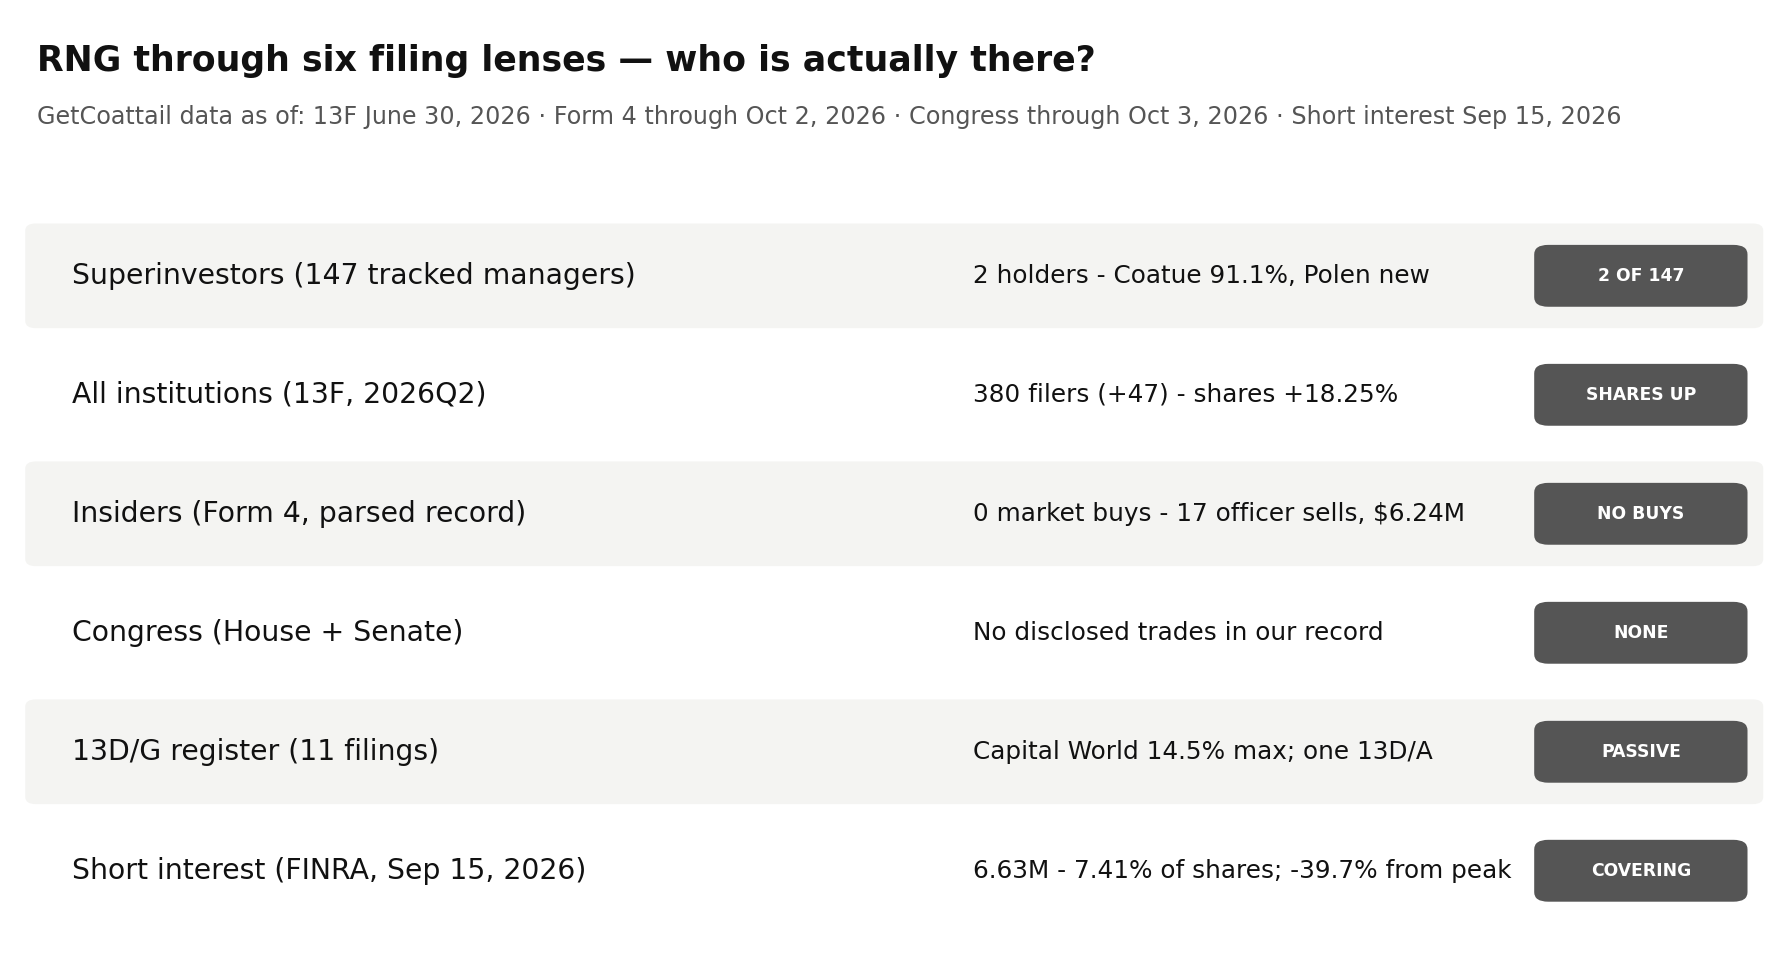
| Superinvestors (13F) | Jun 30, 2026 | 2 of 147 tracked funds hold 451,484 shares, $17.6M reported; Coatue 91.1% | Continuing cohort 0.0%; one new name |
| All institutions (13F) | Jun 30, 2026 | 380 filers, 86,392,888 shares | +47 filers; shares +18.25% |
| Insiders (Form 4) | Through Oct 2, 2026 | 0 open-market buys in the record; 17 officer sells in 90 days ($6.24M) | Selling, never buying |
| Congress | Through Oct 3, 2026 | No disclosed trades in our record | None |
| 13D / 13G | Through Aug 6, 2026 | Capital World 14.5% passive max; latest LSV 5.4%; one 13D/A at 4.88% | Mostly passive |
| Short interest (FINRA) | Sep 15, 2026 | 6,633,567 shares; 7.41% of shares outstanding | −39.7% from Feb 2026 peak; +4.6% y/y |
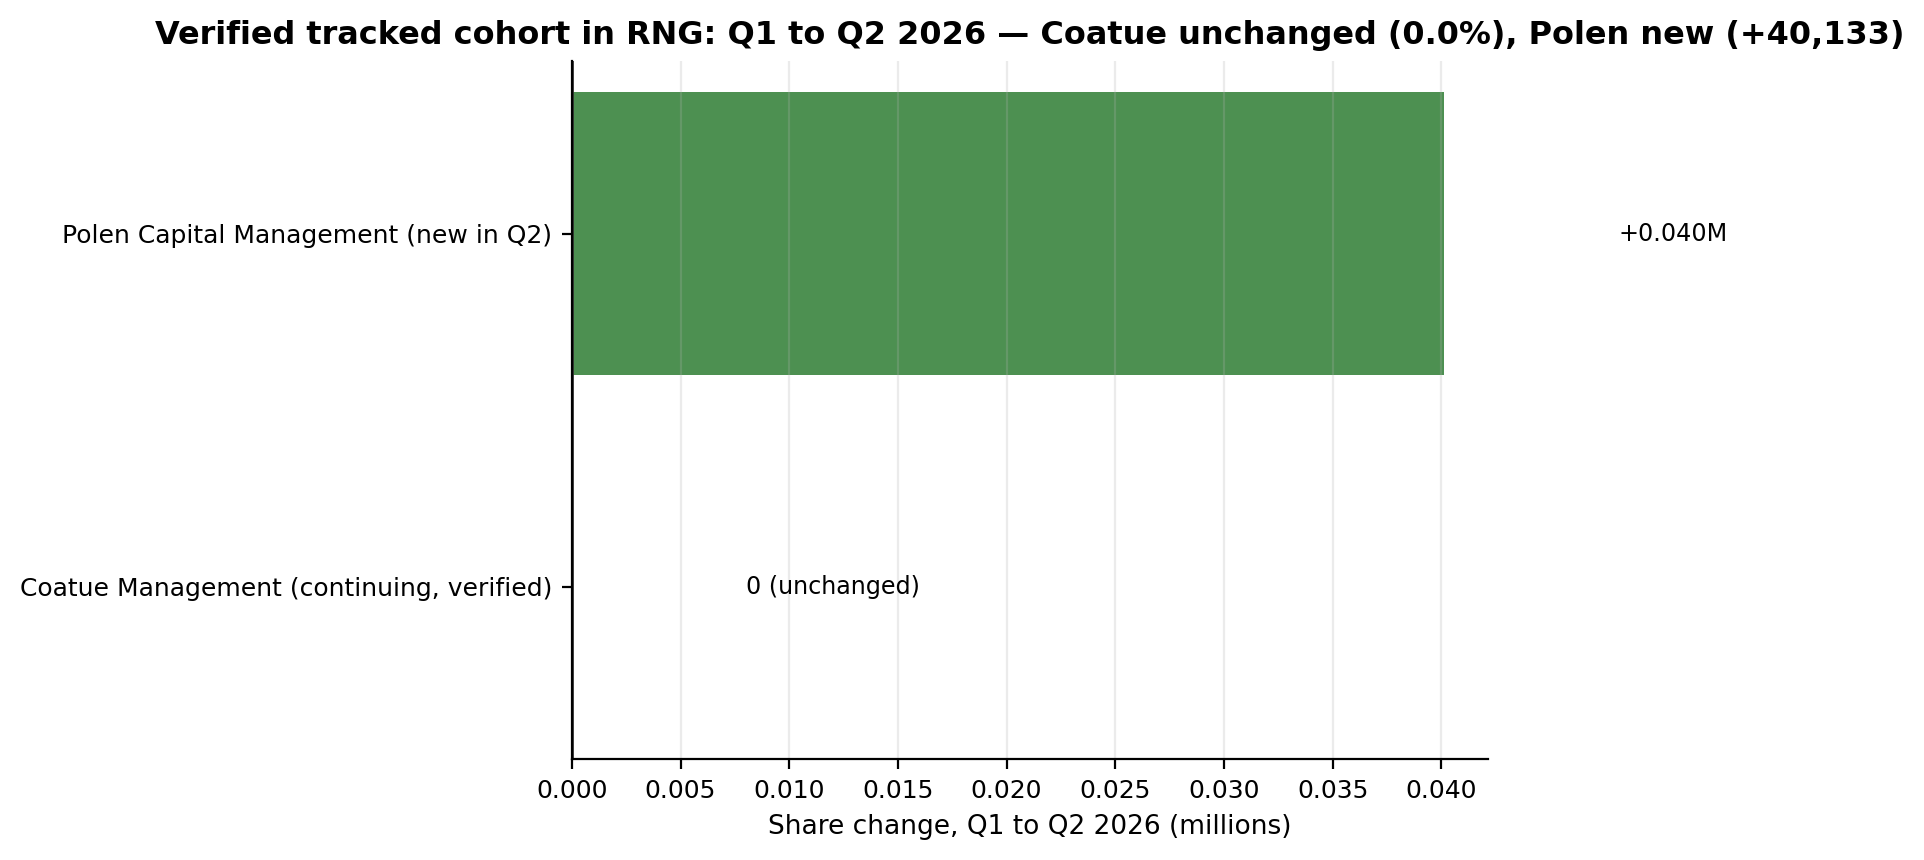
Superinvestors. Two of 147 tracked funds held RNG common stock at June 30, 2026: 451,484 shares, $17.6 million reported — 0.52% of all 13F-reported RNG shares. This is the smallest tracked footprint in this series' recent run: the entire tracked stake is two lines. Coatue Management holds 411,351 shares (91.1% of the cohort, a 0.03% portfolio weight) and sat exactly flat in Q2 — 411,351 shares to 411,351 shares, 0.0%, confirmed by two independent pairing methods against the Q1 register. The only other line is Polen Capital Management with 40,133 shares (8.9% of the cohort, a 0.01% weight), a genuine new position: the Q1 register held only Coatue's row, and the NEW label verifies — no Polen RNG row existed in Q1. No holder cut a share; no holder exited. The cohort's implied price of $38.98 lands exactly on the June 30 close of $38.98. No September early filer holds this name.
All institutions. The broad 13F market did what the tracked crowd did not: it added. Filers grew to 380 (+47, +14.11%) while reported shares grew 18.25% to 86,392,888 — a net add of 13.33 million shares; reported value rose 22.53% to $3.14 billion (value includes option rows, so shares are the cleaner signal). The single-CUSIP fixture check matches exactly. The tracked cohort's flat 0.0% is the still center of a register that was broadly accumulating — the tracked register's net add in the quarter was 40,133 shares (Polen's new line), about 0.30% of the market's 13.33-million net share add.
Insiders. The parsed record is a one-way ledger: 128 filings from February 24, 2025 to September 16, 2026, zero open-market buys, 112 sells totaling 1,246,375 shares and $42.08 million from 7 sellers. Over the last year, 81 sells of 605,877 shares ($24.08 million) from 6 sellers. In the last 90 days: 16 filings, 17 sells of 87,929 shares ($6.24 million) from 4 sellers — AGARWAL VAIBHAV, ARORA TARUN, MAKAGON KIRA, SHMUNIS VLADIMIR — every one an officer row. Implied sale prices pass their price gates in every window (w90 $71.00, w1y $39.74, full-record $33.76). Our site's insider aggregate matches the 90-day window exactly. There is no late-reporting artifact to qualify here — there are simply no P-coded transactions, ever.
Congress. Our record has nothing. The combined aggregate (through October 3, 2026), the House aggregate, and the Senate aggregate (through October 1, 2026) carry no RNG row, and no member file rows mention the ticker. Silence, not signal.
13D / 13G. Eleven filings, ten reporters, eight amendments — and ten of the eleven are passive. Capital World Investors' SC 13G/A at 14.5% (11,735,991 shares, filed November 13, 2025, as of September 30, 2025) is the register maximum. The other large passive prints: BlackRock, Inc. at 13.8% (filed March 5, 2026), Vanguard Portfolio Management at 10.57% (filed March 5, 2026) and 8.85% (filed July 31, 2026, as of June 30), and Vanguard Capital Management at 5.29% (filed April 30, 2026). The one activist-schedule print: Sylebra Capital's SC 13D/A at 4.88% (3,912,007 shares, filed July 29, 2025) — filed at a stake below 5%, the register's only non-passive row. The latest print is LSV Asset Management's SC 13G at 5.4% (3,977,000 shares, filed August 6, 2026, as of June 30, 2026). The aggregate file matches the parsed filings exactly.
Short interest. Shorts covered hard off the February peak, then ticked back up into September. From the February 13, 2026 peak of 10,998,242 shares, the series fell to 6,633,567 shares at September 15, 2026 — −39.7% from the peak, −29.2% since the June 30 settlement (9,367,652), but +4.6% versus a year ago (6,343,280) and +7.24% from the prior settlement (6,185,616 on August 31). The latest print is 4.62 days to cover and 7.41% of shares outstanding — a meaningful short position that rebuilt slightly into the earnings print. (The 137-settlement absolute minimum is an older print from December 2023, so this is not an all-time anything.)
③ The Gap
The market story is an earnings beat: $1.33 against $1.28 expected, guidance raised, +13.53% premarket. The filings neither confirm nor contradict the earnings — but they do say who was in the room before the beat, and it was not the tracked crowd. Two of 147 tracked funds held the name at June 30, and their combined stake was 0.52% of reported 13F shares. The single dominant holder, Coatue, held exactly flat through the quarter in which the stock bottomed at $24.82 and began its climb. Polen's new 40,133 shares — $1.56 million reported — is the register's only fresh tracked money. If the Q2 rally was smart money's work, the tape says it wasn't ours.
The broader register tells the busier story. The full 13F market added 18.25% more shares in Q2 with 47 new filers — the accumulation is real, but it sits outside the tracked 147. That is the gap's first half: the name the earnings made famous is one the superinvestors barely own.
The second half is the insider ledger. Through the same climb that took the stock from $24.82 to $78.28 — up 215.4% from the February low, up 100.8% since June 30 — insiders sold: 112 sells, 1,246,375 shares, $42.08 million across the parsed record, with 17 officer sells in the last 90 days alone. Zero open-market buys, ever. No member of Congress has disclosed a trade. The 13D/G register's largest prints are passive index giants; the lone activist-schedule row is a 2025 amendment at 4.88%.
One plausible reading is that the earnings beat is doing exactly what the premarket move says — rewarding a real quarter (revenue up 5.9%, non-GAAP margin expansion) — and that the filing gaps are simply the lag of a story still being written: the Q3 13F season will show who bought the run-up. But the record as it stands has the rally's sharpest edge pointing away from the tracked names: 18.25% more shares in the broad register, zero insider buys, and a 7.41%-of-shares short interest that covered 39.7% off its peak and then ticked back up. The tape does not predict what the beat earns; it records who was positioned for it, and the answer is: not the crowd this site tracks.
④ What Would Change the Picture
Nothing above is a recommendation. It is a record. The next filing cycles will rewrite that record one row at a time — here is what would change the picture, all checkable in future filings:
- 1. The Q3 13F season (deadline November 16, 2026). Does Coatue add to its 411,351 shares after the earnings pop, or keep sitting flat? Does Polen's 40,133-share toehold grow? Does any new tracked name appear — and does the tracked footprint rise above 0.52% of reported shares?
- 2. A genuine insider buy. Any open-market purchase in a future Form 4 would be the first in our parsed record — against 112 sells and $42.08 million of selling across it.
- 3. Short interest turning. Shorts covered 39.7% from the February peak to September 15, then rebuilt 7.24% in the last settlement. A renewed build through October settlements would signal the bear case is rearming into the earnings pop; continued covering would confirm the unwind.
- 4. A new 13D. The register's only activist-schedule row is Sylebra's 2025 amendment at 4.88%. A fresh SC 13D would change the register's character from passive to contested.
- 5. Congressional trades. Nothing disclosed now, in either chamber. Any print would be the first data point in an empty record.
⑤ As-of & Limits
| Lens | As of |
|---|---|
| Superinvestors (13F) | Jun 30, 2026 (13F figures are as of the quarter-end; funds have up to 45 days after quarter-end to file, so this is the most recent complete picture — and it is always a lagging one) |
| All institutions (13F) | Jun 30, 2026 (same lag) |
| Insiders (Form 4) | Filings through Oct 2, 2026 (parsed record from Feb 24, 2025) |
| Congress | Through Oct 3, 2026 (Senate through Oct 1, 2026) |
| 13D / 13G | Filings through Aug 6, 2026 |
| Short interest (FINRA) | Settlements through Sep 15, 2026 |
| Prices | Through Oct 2, 2026 (our file) |
Methodology and data notes
- As-of & limits: The lenses rest on different clocks, none live: 13F is a June 30, 2026 snapshot published up to 45 days later; Form 4 windows run through October 2, 2026; Congress aggregates run through October 3, 2026 (Senate through October 1, 2026); 13D/G through August 6, 2026; short-interest settlements through September 15, 2026; the price file ends October 2, 2026. Limits specific to this audit. First, the tracked cohort is two managers with one dominant holder — Coatue at 91.1% of the cohort is a 0.03% portfolio weight; Polen's new 40,133 shares are a 0.01% weight. Second, RNG common stock carries a single CUSIP (76680R206), and the full-market by-CUSIP row matches the by-ticker aggregate on every field — holders, long holders, shares, reported value, prior holders and prior reported value — so no CUSIP blending question arises. Third, the tracked change figures are verified, not taken on trust: Coatue's continuing position was verified by two methods that agree — a total-value prefix pass and accession identity plus CUSIP-overlap pairing — with the 0.0% label recomputing exactly from share counts (411,351 to 411,351); Polen's NEW label was verified against the Q1 register, which holds only Coatue's single row — the Q1 register total is 411,351 shares against the Q2 register's 451,484. No September early filer holds this name. The registers reconcile with no remainder. Fourth, the June cohort's implied price is $38.98 against the June 30 close of $38.98 (+0.00%). Fifth, the full-market aggregate implies $36.36 against the $38.98 close (−6.72%): the aggregate is a reported sum that includes option rows, so its implied price need not equal the close; this audit uses filer counts and share counts as this lens's primary measures and reports the value as reported only. Sixth, the insider lens rests on a single aggregate bucket — this issuer's filings sit under one symbol spelling, "RNG", with no case split — cross-checked against a row-level scan of all 128 parsed filings for the issuer (CIK 1384905): filing counts, transaction counts, share counts, officer-row counts and values reproduce exactly in every window, and no accession appears under more than one symbol spelling. There are zero P-coded transactions in the entire parsed record; the implied sale prices pass their price gates (the 90-day implied sale price of $71.00, the one-year implied sale price of $39.74 and the full-record implied sale price of $33.76 each sit inside their filing-window close ranges). The 90-day window contains 16 filings and 17 officer sells by 4 sellers. Form 4 windows in this audit are filing-date windows. Our site's insider aggregate carries an RNG row (checked October 23, 2026) and matches the 90-day window exactly: 0 buys, 17 sellTx, $6,243,242.92. Seventh, the congressional lens is reported across four files: the combined aggregate, the House aggregate, the Senate aggregate and the member files — none carries an RNG row; that absence is reported, not interpreted. Eighth, the 5% register holds eleven filings from ten reporters with eight amendments: Capital World Investors' SC 13G/A (filed November 13, 2025) prints 11,735,991 shares at 14.5% as of September 30, 2025 — the register maximum; BlackRock, Inc.'s SC 13G/A (filed March 5, 2026) prints 10,248,861 shares at 13.8% as of February 28, 2026; Vanguard Portfolio Management's SC 13G (filed March 5, 2026) prints 8,019,586 shares at 10.57% as of February 27, 2026, and its SC 13G/A (filed July 31, 2026) prints 6,562,347 shares at 8.85% as of June 30, 2026; Vanguard Capital Management's SC 13G (filed April 30, 2026) prints 3,930,398 shares at 5.29% as of March 31, 2026; Sylebra Capital's SC 13D/A (filed July 29, 2025) prints 3,912,007 shares at 4.88% as of July 25, 2025 — the register's only activist-schedule row; LSV Asset Management's SC 13G (filed August 6, 2026) prints 3,977,000 shares at 5.4% as of June 30, 2026 — the latest print. The parsed totals match the aggregates exactly, and each print is reported individually in the text. Ninth, the short-interest series holds 137 settlements beginning January 15, 2021, so its maximum and minimum describe that span only. Within it, the series carries no discontinuity of 2x or one-half on consecutive settlements on this measure. No row carries a split flag; one row (June 15, 2021, at 4,965,402 shares) carries a FINRA revision flag. The series reads 10,998,242 (Feb 13, 2026, the maximum) → 9,367,652 (Jun 30, 2026) → 8,806,800 (Jul 15) → 7,649,444 (Jul 31) → 7,062,139 (Aug 14) → 6,185,616 (Aug 31) → 6,633,567 (Sep 15, −39.7% below the maximum, +7.24% from the prior settlement). The 7.41% short-interest figure uses 89,481,000 shares from our fundamentals file (a measured period-end count), not a float estimate. Our price file records no split factor for this name. The fundamentals record is status ok: FY2025 revenue $2,515,142,000 and net income $43,391,000 are reported as stored. The market figures in The Hype — the premarket moves, the Q3 EPS and revenue figures, the raised guidance ranges, the analyst estimates — are the outlets' and the company's published figures, cited as such, not blended into file-based calculations; our price file cannot confirm or refute post-October-2 price levels.
- Market context sources: Swingfolio, October 23, 2026 ("US Pre-Market 23 Oct 2026: Dow Futures -0.72%": RNG.US +13.53%, "Q3 EPS $1.33 against $1.28 expected; raised full-year outlook", as of 8:31am ET); Seeking Alpha, October 23, 2026 ("At a glance: stocks gapping up premarket": RingCentral (RNG) +15.4%, published 11:20 UTC); RingCentral company announcement (reported October 22, 2026: Q3 2026 total revenue $676.0M, +5.9% y/y; non-GAAP diluted EPS $1.33 vs $1.13 a year earlier; GAAP diluted EPS $6.50 including a $544.9M benefit from a partial release of the valuation allowance; raised full-year 2026 guidance — total revenue $2.650B–$2.657B, non-GAAP EPS $5.07–$5.12, free cash flow $620M–$630M); StockStory, October 23, 2026 ("RingCentral (NYSE:RNG) surprises with Q3 2026 sales, stock jumps 14.8%": revenue $676M vs $667.4M estimates; adjusted EPS $1.33 vs ~$1.27 estimates; raised full-year adjusted EPS guidance midpoint to $5.10).
- RNG is in the GetCoattail stock-page universe: RNG (RNG) stock page. Tracked manager pages: Coatue Management · Polen Capital Management. Series data: rng_lens_data.csv · rng_short_interest_series.csv. Earlier audits: Dollar General · TJX.
Past patterns are not a promise of future results. For education only — not investment advice.
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history: v1.0 — October 23, 2026: first publication.