GetCoattail Research — The Filing Tape #174. Abbott Laboratories (ABT) reported Q3 2026 results on October 21, 2026 — net sales $13.01 billion (+14.5%), adjusted EPS $1.42 (a 0.7% consensus miss) — and announced a plan to spin off its Nutrition business by the end of 2027; the stock fell ~3.6% premarket. Abbott ranked sixth on TipRanks' analyst-attention trending screener on October 23 (12 buy ratings in 72 hours, Strong Buy, average price target $122.12). The filings show 10 of 147 tracked funds holding 13,945,545 shares of Abbott Laboratories common stock, $1.265 billion reported, as of June 30, 2026: Flossbach von Storch alone is 71.4% of that stake; the verified continuing cohort grew 12.1% in Q2 — but ex-Flossbach the other eight holders shrank 17.7%; insiders sold $46.85 million in the 90 days through October 2, 2026 with zero buys; seven House members traded the name (2 buys, 8 sells); the passive 13G register's largest historical holder (The Vanguard Group, 10.05%) dropped below 5% while Vanguard Capital Management filed a new 7.5% 13G; and short interest is down 19.9% from its July peak, at 1.14% of shares outstanding.
① The Hype
Abbott Laboratories had a busy week. On October 21, 2026, the company reported third-quarter results: net sales of $13.01 billion, up 14.5% from a year earlier, and adjusted earnings per share of $1.42, up 9.2% — but a touch below the consensus estimate, missing by 0.7%. The stock fell about 3.6% in premarket trading. In the same announcement, Abbott said it plans to spin off its Nutrition business into a separate publicly traded company by the end of 2027, a portfolio reshaping that immediately became the second headline of the week.
Analysts are paying attention. On TipRanks' trending-by-analyst-attention screener, Abbott ranked sixth on October 23, with 12 buy ratings issued in the previous 72 hours, a Strong Buy consensus, and an average price target of $122.12 — implying about 18.7% upside from the then-current price.
The price, meanwhile, tells a cooler story. Abbott closed at $102.51 on October 22 — down 22.4% from its 52-week high of $132.03, down 1.1% over the past month, but up 10.8% over the past 126 trading days. The question for this series is the usual one: what do the filings say?
② The Tape
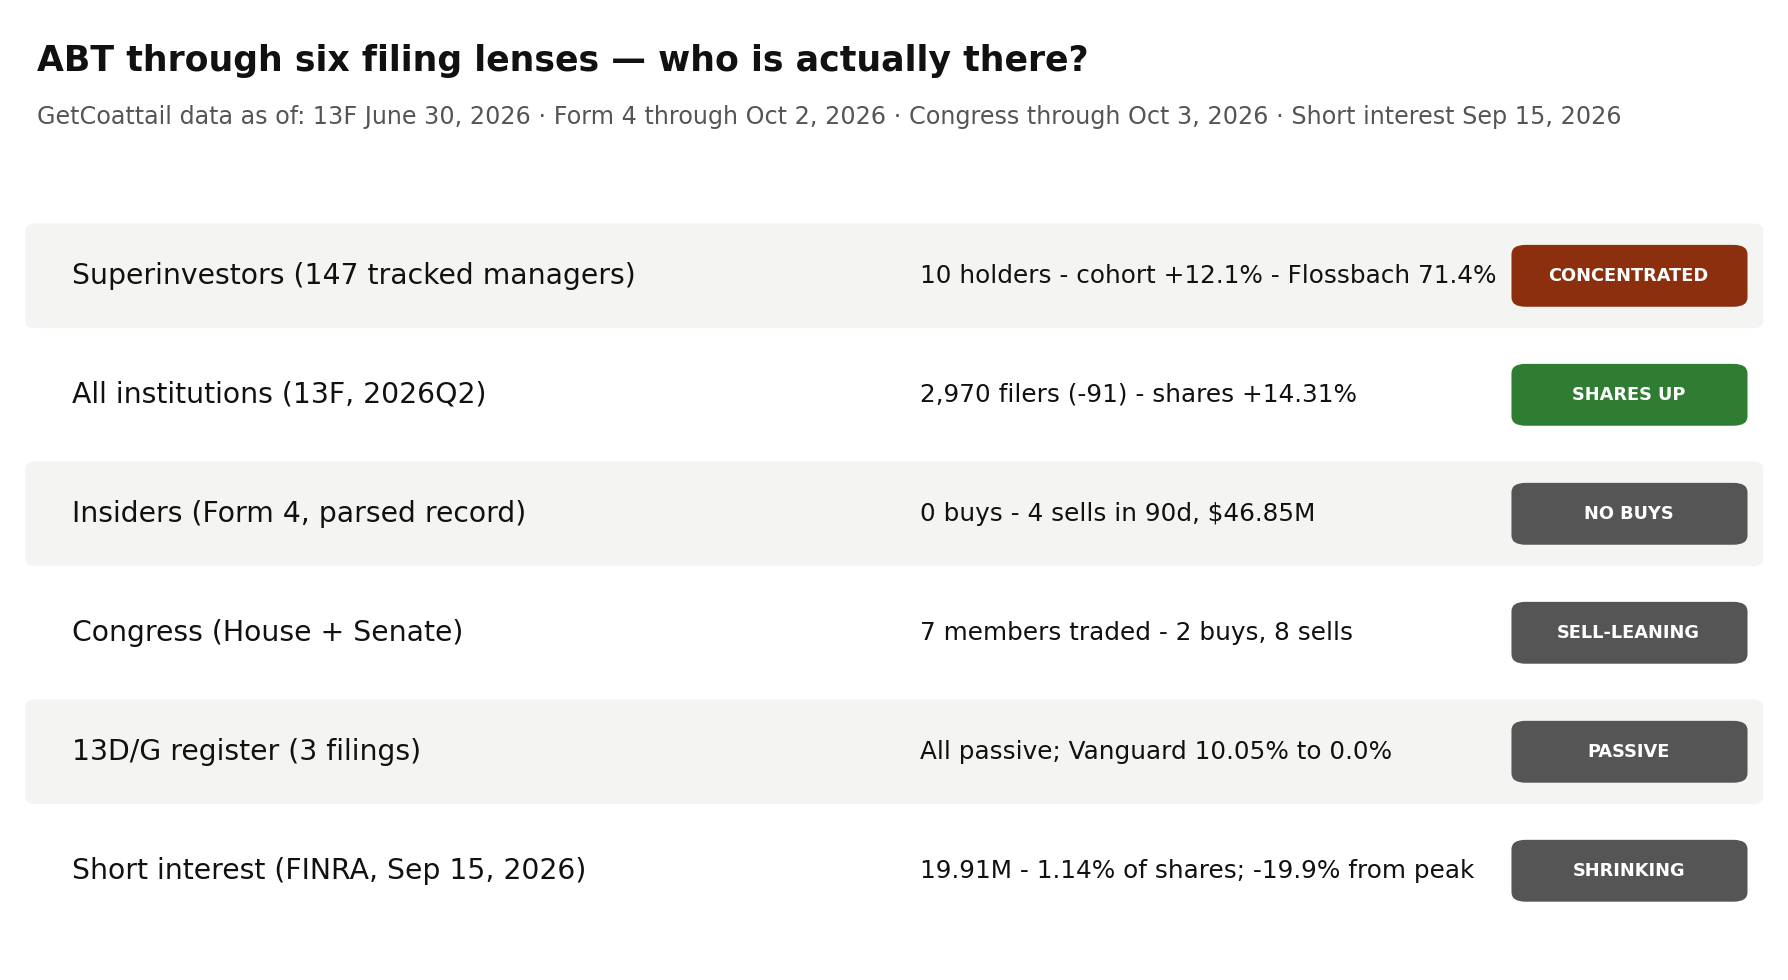
We read Abbott through GetCoattail's six filing lenses. The table summarizes; the paragraphs give the detail. Every number below comes from our pipeline, not from a press release.
| Lens | As of | What the filings show | Direction vs prior period |
|---|---|---|---|
| Superinvestors (13F) | Jun 30, 2026 | 10 holders, 13,945,545 shares ($1.265B reported); Flossbach von Storch alone is 71.4% | Verified continuing cohort +12.1% (Q1 to Q2) |
| All institutions (13F) | Jun 30, 2026 | 2,970 filers, 1,366,328,316 shares ($121.9B reported) | Shares +14.31%; filer count −91 |
| Insiders (Form 4) | Oct 2, 2026 | 0 buys / 4 sells in 90 days ($46.85M sold); 6 small buys in the past year ($4.40M) | Sells continued; no buys in 90 days |
| Congress | Oct 3, 2026 (House) | 7 members traded: 2 buys / 8 sells, all in the smallest bands | Sell-heavy, tiny size |
| 13D/G | Apr 29, 2026 | All passive; Vanguard Group fell from 10.05% to 0.0%; Vanguard Capital Management filed a new 7.5% 13G | Vanguard dropped below 5% |
| Short interest | Sep 15, 2026 | 19,911,199 shares (1.14% of shares outstanding) | −14.9% since Jun 30; −19.9% from the Jul 15 peak |
Superinvestors (13F). Ten of the 147 tracked managers held Abbott common stock on June 30, 2026 — 13,945,545 shares with a reported value of $1.265 billion. One number dominates this lens: Flossbach von Storch holds 9,950,828 shares, 71.4% of the entire tracked cohort's Abbott position, at a 4.08% portfolio weight. The top two holders together are 78.9% of the cohort. In other words, "the superinvestors own Abbott" mostly means one German asset manager owns Abbott.
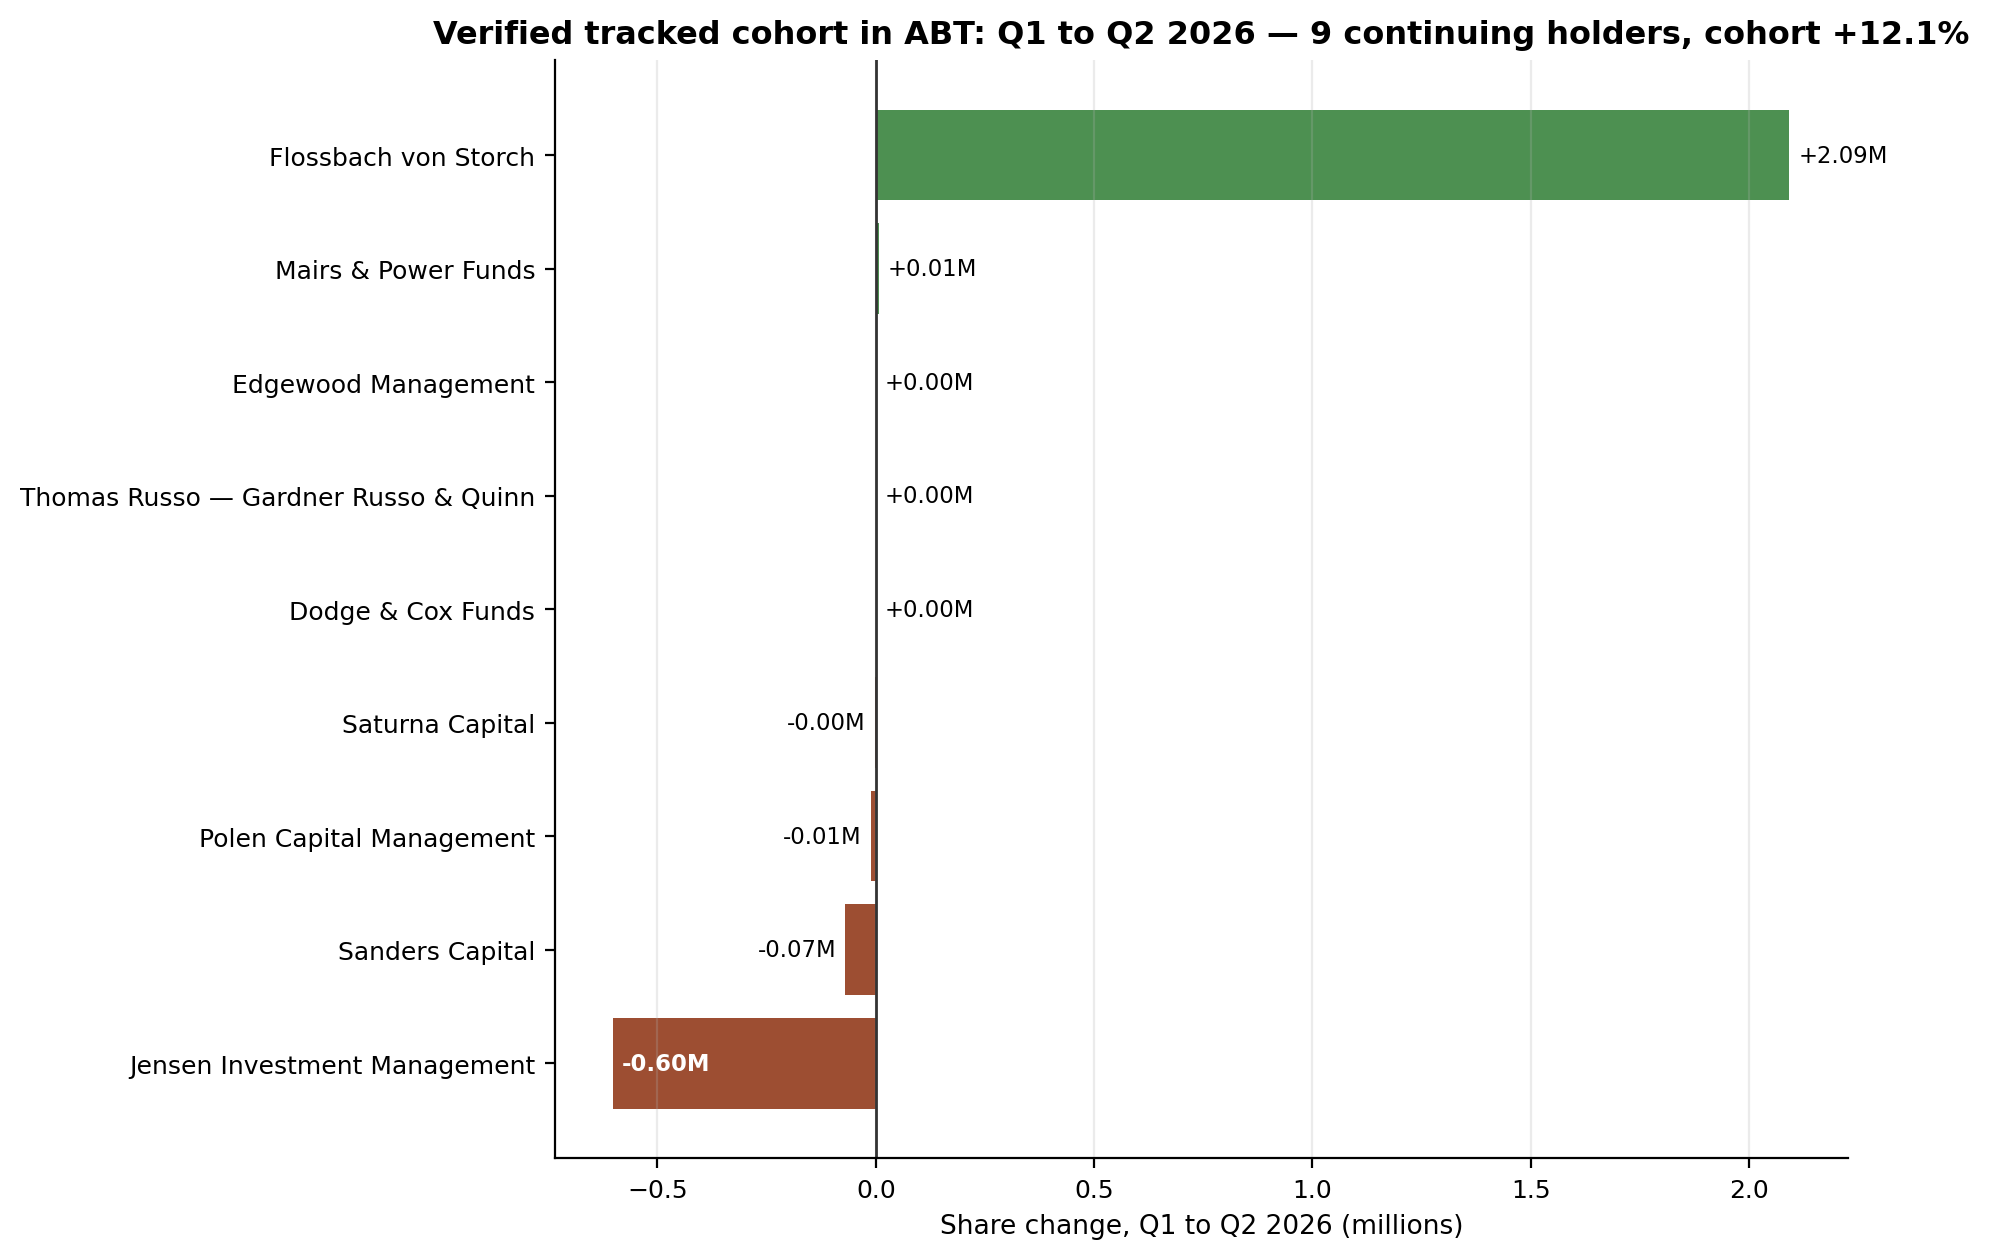
The direction of the continuing holders is unusual for this series: the nine holders we could verify against their Q1 filings — every label recomputed exactly from paired accessions — grew their combined stake from 11,691,323 to 13,104,798 shares, +12.1%. Flossbach itself added 26.6% (7,858,443 → 9,950,828 shares). The mix: 3 unchanged, 4 decreased, 2 increased, 1 genuinely new. The new name is Mason Hawkins' Southeastern Asset Management with 840,747 shares (verified new — no Q1 Abbott rows under its filing identity). The exit is Lee Ainslie's Maverick Capital, which held 1,758,160 shares in Q1 and none in Q2. David Katz's Matrix Asset Advisors, a September-30 early filer, holds 52,805 shares ($5.2 million) outside the June cohort. The Q1 and Q2 filing registers reconcile to the share: continuing holders plus Maverick's exit equal the Q1 register exactly, and the June cohort's implied price ($90.74) matches the June 30 close to the cent. 13F figures are as of June 30, 2026, the quarter-end. Funds have up to 45 days after quarter-end to file, so this is the most recent complete picture — and it is always a lagging one.
All institutions (13F). The full market tells a broader version of the same story: 2,970 filers held 1,366,328,316 Abbott shares ($121.9 billion reported) on June 30 — up 14.31% in shares from Q1 even as the filer count fell by 91 (1,879 entered, 1,970 exited). The tracked superinvestor cohort is 1.02% of those reported shares.
Insiders (Form 4). Through October 2, 2026, Abbott insiders filed 10 transactions in the last 90 days: zero buys, four sells — 404,709 shares, $46.85 million. The sellers were CEO Robert B. Ford, John A. McCoy Jr., and Louis H. Morrone, all of them officer sales. Over the past year the picture softens only slightly: six buys totaling 43,000 shares ($4.40 million) from four buyers, against 11 sells totaling 410,494 shares ($47.54 million). In the full parsed record (123 filings, January 2025 – October 2026), buys remain exactly those six; sells total 25 transactions and $126.6 million. Our site's insider aggregate matches the 90-day window exactly.
Congress. Seven House members traded Abbott in the 2026 disclosure window (April 1 – October 3, 2026): two buys and eight sells. The buys came from Gilbert Cisneros and Richard Dean McCormick; the sells are spread across five more members, with Richard W. Allen's two sells in the $15,001–$50,000 band and everything else in the smallest $1,001–$15,000 band. The Senate shows no Abbott rows. Small money, sell-leaning.
13D/G. Three filings, all passive, two reporters. The Vanguard Group reported 10.05% (174,894,079 shares) in a December 2025 amendment — then amended in March 2026 to 0.0 shares and 0.0%, dropping below the 5% reporting threshold. A month later, Vanguard Capital Management filed a new 13G at 7.5% (130,676,776 shares). No activist (13D-family) filings.
Short interest. FINRA settlements through September 15, 2026: short interest was 19,911,199 shares — 1.14% of Abbott's 1.74 billion shares outstanding, with 2.57 days to cover. That is down 14.9% from the June 30 settlement and 19.9% below the July 15 peak of 24,846,147 shares, though still 10.2% above the level a year earlier. The short book has been shrinking since mid-July; it is not a crowded short.
③ The Gap
The market's Abbott story this week is an earnings-and-breakup story: sales growing 14.5%, margins expanding, a Nutrition spin-off by end of 2027, and analysts leaning in with a dozen fresh buy ratings. The filings tell a quieter, more concentrated story underneath it.
First, concentration. The superinvestor register for Abbott is a one-fund show: Flossbach von Storch's 9.95 million shares are 71.4% of the tracked cohort, and its Q2 addition of 2,092,385 shares is larger than the cohort's entire net addition of 1,413,475. Remove Flossbach and the continuing cohort didn't grow at all — the other eight holders shrank a combined 17.7%.
Second, insiders. While analysts published buy ratings, Abbott's own officers sold $46.85 million of stock in the 90 days through October 2 and bought none. The year's six insider buys total $4.4 million — less than a tenth of the 90-day sales. (Insider sales are routine compensation events; the filing record shows the transactions, not the motives.)
Third, the Vanguard rotation. The largest passive holder on record went from 10.05% to effectively zero in one amendment, replaced a month later by a different Vanguard entity at 7.5%. That is index plumbing, not a verdict — but it is the biggest single change in Abbott's passive register this year.
One plausible reading is that the filings and the market are looking at different clocks: the 13F register is a June snapshot in an October news cycle, while the insider and short-interest lenses — current through early October and mid-September — show selling insiders and a shrinking short book. Neither lens contradicts the earnings story; they just don't confirm it either.
④ What Would Change the Picture
Nothing above is a recommendation. It is a record. Here is what to watch in the next filing cycles:
- 1. Q3 13F season (filings due by November 16, 2026). Does Flossbach's 9.95-million-share position survive the earnings-week dip, and does the rest of the cohort follow its +12.1% Q2 direction or Maverick's exit?
- 2. Form 4 after the spin-off details land. Any insider buying — there has been none in 90 days — would be the first crack in the one-sided insider tape.
- 3. The passive register. Vanguard Capital Management's 7.5% is now the largest passive report; watch whether the zeroed-out Vanguard Group filing stays at zero.
- 4. Short interest into year-end. The book fell 19.9% from its July peak; a fresh build into the spin-off would signal the skeptics are re-engaging.
- 5. Congressional disclosures. Seven members traded this year, all tiny; a larger-band trade by any of them would be new information.
⑤ As-of & Limits
| Lens | As of | Coverage note |
|---|---|---|
| Superinvestors 13F | Jun 30, 2026 (filed ≤ Aug 14) | 10 June holders + 1 Sep-30 early filer; 147-manager collection |
| All institutions 13F | Jun 30, 2026 | 2,970 filers; value is reported (includes option rows) |
| Insiders (Form 4) | Oct 2, 2026 | 123 filings parsed by issuer CIK; scan matches aggregate |
| Congress | Oct 3, 2026 (House); Oct 1, 2026 (Senate) | House PTR filings, 2026 window; Senate: no rows |
| 13D/G | Apr 29, 2026 (latest filing) | 3 parsed filings; no activist filings |
| Short interest | Sep 15, 2026 | FINRA, 137 settlements |
Limits: 13F captures long positions only, with a 45-day reporting lag — the June snapshot predates the October earnings and spin-off news. The Q2 register contains one 47,262-share row that matches no tracked manager's filing identity; it is left unattributed rather than assigned. Congressional amounts are reported in bands, not exact dollars. Short interest is a mid-month settlement snapshot. Past patterns are not a promise of future results. For education only — not investment advice.
Methodology and data notes
- As-of & limits: The lenses rest on different clocks, none live: 13F is a June 30, 2026 snapshot published up to 45 days later; Form 4 windows run through October 2, 2026; Congress aggregates run through October 3, 2026 (Senate through October 1, 2026 — no rows); 13D/G through April 29, 2026; short-interest settlements through September 15, 2026; the price file ends October 2, 2026 while the daily-refreshed close quoted ($102.51) is from October 22, 2026. Limits specific to this audit. First, the tracked cohort is 10 June holders: the largest, Flossbach von Storch at 71.4% of the cohort, is a 4.08% portfolio weight; the top two holders together are 78.9%. Second, Abbott common stock carries a single CUSIP (002824100), and the full-market by-CUSIP row matches the by-ticker aggregate — so no CUSIP blending question arises. Third, the tracked change figures are verified, not taken on trust: 9 continuing holders were paired by accession identity plus CUSIP-overlap matches, and every share-change label recomputed exactly (Flossbach +26.6%, Jensen −40.4%, Mairs & Power +1.0%, Polen −79.1%, Sanders −6.3%, Saturna −0.8%, the rest unchanged). Mason Hawkins' NEW label was verified against the Q1 register (no Q1 rows under its filing identity); Maverick's exit is 1,758,160 shares. Mairs & Power, Polen, and Sanders file their 13F under filer CIK 1172661 (distinct from their adviser CIKs in our roster); register rows are identity-matched by total_value_usd, which is exact for all three. Fourth, the Q1 register reconciles exactly: continuing verified 11,691,323 + Maverick exit 1,758,160 = 13,449,483 shares, the Q1 register total. (The compute script's reported Q1 residual of −1,121,205 is a pairing artifact — its early-filer block double-counted Sanders Capital's verified Q1 row as Matrix's.) Fifth, the Q2 register holds one 47,262-share row (accession 0001172661-26-002637) whose total_value_usd matches no tracked manager's filing total — not Matrix's either; it is left unattributed. Matrix's September-30 position (52,805 shares, $5.2 million, label INCREASED +11.7%) is reported from the manager collection as filed. Sixth, the June cohort's implied price is $90.74 against the June 30 close of $90.74 (+0.00%). Seventh, the full-market aggregate implies $89.22 against the $90.74 close (−1.7%): the aggregate is a reported sum that includes option rows, so its implied price need not equal the close; this audit uses filer counts and share counts as this lens's primary measures and reports the value as reported only. Eighth, the insider lens rests on a single aggregate bucket — this issuer's filings sit under one symbol spelling, "ABT", with no case split — cross-checked against a row-level scan of all 123 parsed filings for the issuer (CIK 1800): filing counts, transaction counts, share counts, officer-row counts and values reproduce exactly in every window, and no accession appears under more than one symbol spelling. The implied sale prices pass their price gates (the 90-day implied sale price of $115.76, the one-year implied sale price of $115.81 and the full-record implied sale price of $124.63 each sit inside their filing-window close ranges). Form 4 windows in this audit are filing-date windows. Our site's insider aggregate carries an ABT row that matches the 90-day window exactly (0 buys, 4 sells, $46,850,261.46). Ninth, the congressional lens is reported across the combined aggregate (2 buys, 8 sells), the House aggregate (same), the Senate aggregate (no rows) and the member file — which names seven members (Cisneros 1 buy, McCormick 1 buy, Allen 2 sells, Gottheimer 1 sell, Johnson 1 sell, Kelly 1 sell, Larsen 1 sell); the "members" field in the aggregates counts only members with buys (2), while the member index lists all seven members with rows; every amount sits in the $1,001–$15,000 band except Allen's two sells ($15,001–$50,000). Tenth, the 5% register holds three filings from two reporters with two amendments, all passive: The Vanguard Group's SC 13G/A (event November 28, 2025, filed December 3, 2025) prints 174,894,079 shares at 10.05% — the register maximum; the same reporter's SC 13G/A (event March 13, 2026, filed March 26, 2026) prints 0 shares at 0.0% — below the reporting threshold; Vanguard Capital Management's SC 13G (event March 31, 2026, filed April 29, 2026) prints 130,676,776 shares at 7.5% — the largest current print. The parsed totals match the aggregate exactly (filings, max percent, total shares reported, latest date). Eleventh, the short-interest series holds 137 settlements, so its maximum and minimum describe that span only. Within it, no consecutive-settlement step is ≥2x or ≤0.5x (max step 1.30x on March 15, 2021; min 0.80x on June 14, 2024). The series reads 23,387,895 (Jun 30, 2026) → 24,846,147 (Jul 15, peak) → 22,624,184 (Jul 31) → 20,375,133 (Aug 14) → 22,129,750 (Aug 31) → 19,911,199 (Sep 15, −19.9% from the peak, −14.9% from the June settlement, +10.2% from a year earlier). The 1.14% short-interest figure uses 1,741,812,429 shares from our fundamentals file (a measured period-end count), not a float estimate. Our price file records no split factor for this name. The fundamentals record is status ok: FY2025 revenue $44,328,000,000 (stored under the us-gaap concept tag RevenueFromContractWithCustomerExcludingAssessedTax — the tag is disclosed because it differs from the usual sales concept) and net income $6,524,000,000, total assets $86,713,000,000, 1,741,812,429 shares outstanding as of March 31, 2026, market cap $170,976,314,409.35 at the October 6, 2026 price. The market figures in The Hype — the Q3 sales and EPS figures, the consensus miss, the premarket move, the spin-off plan, the TipRanks trending rank and price target — are the outlets' published figures, cited as such, not blended into file-based calculations; our price file cannot confirm or refute post-October-2 price levels, which is why the October 22 close is separately sourced from the daily-refreshed chart statistics.
- Market context sources: Abbott Laboratories Q3 2026 press release via Morningstar/PR Newswire, October 21, 2026 (net sales $13.01B +14.5%, adjusted EPS $1.42 +9.2% y/y, miss by 0.7%, ~3.6% premarket decline); tickeron earnings recap (Nutrition spin-off plan by end of 2027); TipRanks trending-by-analyst-attention screener, October 23, 2026 (ABT #6, 12 buy ratings in 72h, Strong Buy, average price target $122.12, +18.74% implied upside).
- ABT is in the GetCoattail stock-page universe: ABT (ABT) stock page. Tracked manager pages: Flossbach von Storch · Sanders Capital · Jensen Investment Management · Mason Hawkins — Southeastern Asset Management · Mairs & Power Funds. Series data: abt_lens_data.csv · abt_short_interest_series.csv. Earlier audits: Analog Devices · RingCentral · TJX.
This article describes filings and reported positions — it is not investment advice. Past patterns are not a promise of future results. For education only — not investment advice.
Revision history: v1.0 — October 24, 2026