GetCoattail Research — The Filing Tape #72. Corning beat its second-quarter estimate and the stock fell anyway, on guidance. The filings describe a register where all four tracked superinvestors cut in the quarter the price rose 87.9%, two more exited, the full market added 103.1 million shares, insiders have recorded no purchase at all, and the borrow peaked in mid-June, days before the price did.
The Hype
Corning is the tenth name on MarketBeat's trending-stocks list, after one of the year's sharpest round trips. In the second quarter of 2026 the stock rose from $135.97 at March 31 to $255.43 at June 30 on our daily-close file — up 87.9% in a single quarter — as its optical-fiber business became shorthand for the data-center buildout. The second-quarter print itself beat: earnings of $0.78 per share against a $0.76 consensus, revenue of $4.74 billion, optical communications sales up 32% to $2.07 billion with segment net income up 77%, gross margin of 39.6% and $1.42 billion of free cash flow. The stock fell about 12% on the day anyway, because third-quarter guidance of $0.85 to $0.89 per share came in below what the market had pencilled in. Since then the shares have slid to $164.19 by October 2 on our file — down 35.7% from the June 30 close — and MarketBeat's trending page prints $146.88, a moderate-buy consensus and an average target of $177.56. The company declared a $0.28 quarterly dividend on October 7, Truist raised its target from $175 to $182, and third-quarter results are due October 27, with analysts expecting $0.88 per share. The filings answer who held the stock on the way up, and what they did at the top.
The Tape
For Corning — the seventy-second Filing Tape audit — the tape shows a tracked cohort that cut unanimously into an 87.9% quarter, a full market adding 457 filers and 103.1 million shares, an insider record with no purchase in it, an empty congressional register, a passive-only 5% register, and a borrow that peaked two weeks before the price.
| Lens | As of | What the filings show | Direction vs prior period |
|---|---|---|---|
| Superinvestors (13F) | Jun 30, 2026 | 4 long holders; 2,852,944 shares; $728,727,486 | Shares -46.69% vs Q1; all 4 holders cut; 2 more exited |
| All institutions (13F) | Jun 30, 2026 | 2,684 filers; 625,947,736 shares | Filers +457; shares +19.72% |
| Insiders (Form 4) | Oct 2, 2026 | 0 purchases in the entire parsed record; 59 sales | Last 90 days: 0 purchases, 2 sales |
| Congress | Oct 3, 2026 | No recorded transactions in either chamber | No entry in the combined, House or Senate aggregates |
| 13D/G | Apr 29, 2026 | 4 parsed filings (0 SC 13D-family, 4 SC 13G-family); register maximum 8.3% (Samsung Display) | Largest chain stepped down to 7.94% in August 2025 |
| Short interest (FINRA) | Sep 15, 2026 | 17,615,953 shares; 2.05% of shares outstanding | Series record set Jun 15, 2026; latest -25.9% below it |
Lens 1 — the superinvestors: four holders, four cuts, two exits. We track 83 large, mostly long-only managers whose 13F portfolios we collect directly from SEC EDGAR. As of June 30, 2026, 4 held Corning long, totalling 2,852,944 shares worth $728,727,486, with no option rows — and every one of the four is labelled decreased. Stephen Mandel's Lone Pine Capital holds 2,728,058 shares worth $696,827,855, a 4.26% portfolio weight — 95.6% of the cohort's position — after cutting 26.6% in the quarter. Mairs & Power holds 85,447 shares after cutting 3.2%; Dodge & Cox holds 34,665 shares after cutting 4.6%; Lee Ainslie's Maverick Capital holds 4,774 shares after cutting 98.7%. On the pipeline's holdings files, the cohort held 5,351,779 shares across six rows at March 31 and 2,852,944 at June 30, a change of -2,498,835 shares (-46.69%). The two missing rows are exits: David Tepper's Appaloosa Management, which held 1,129,500 shares at March 31, and Steven Check's Check Capital Management, which held 5,050 shares, both appear on the collection's exit list. The implied price, $255.43, sits exactly on the June 30 close. 13F figures are as of June 30, 2026; funds have up to 45 days to file, so this picture is complete — and always lagging.
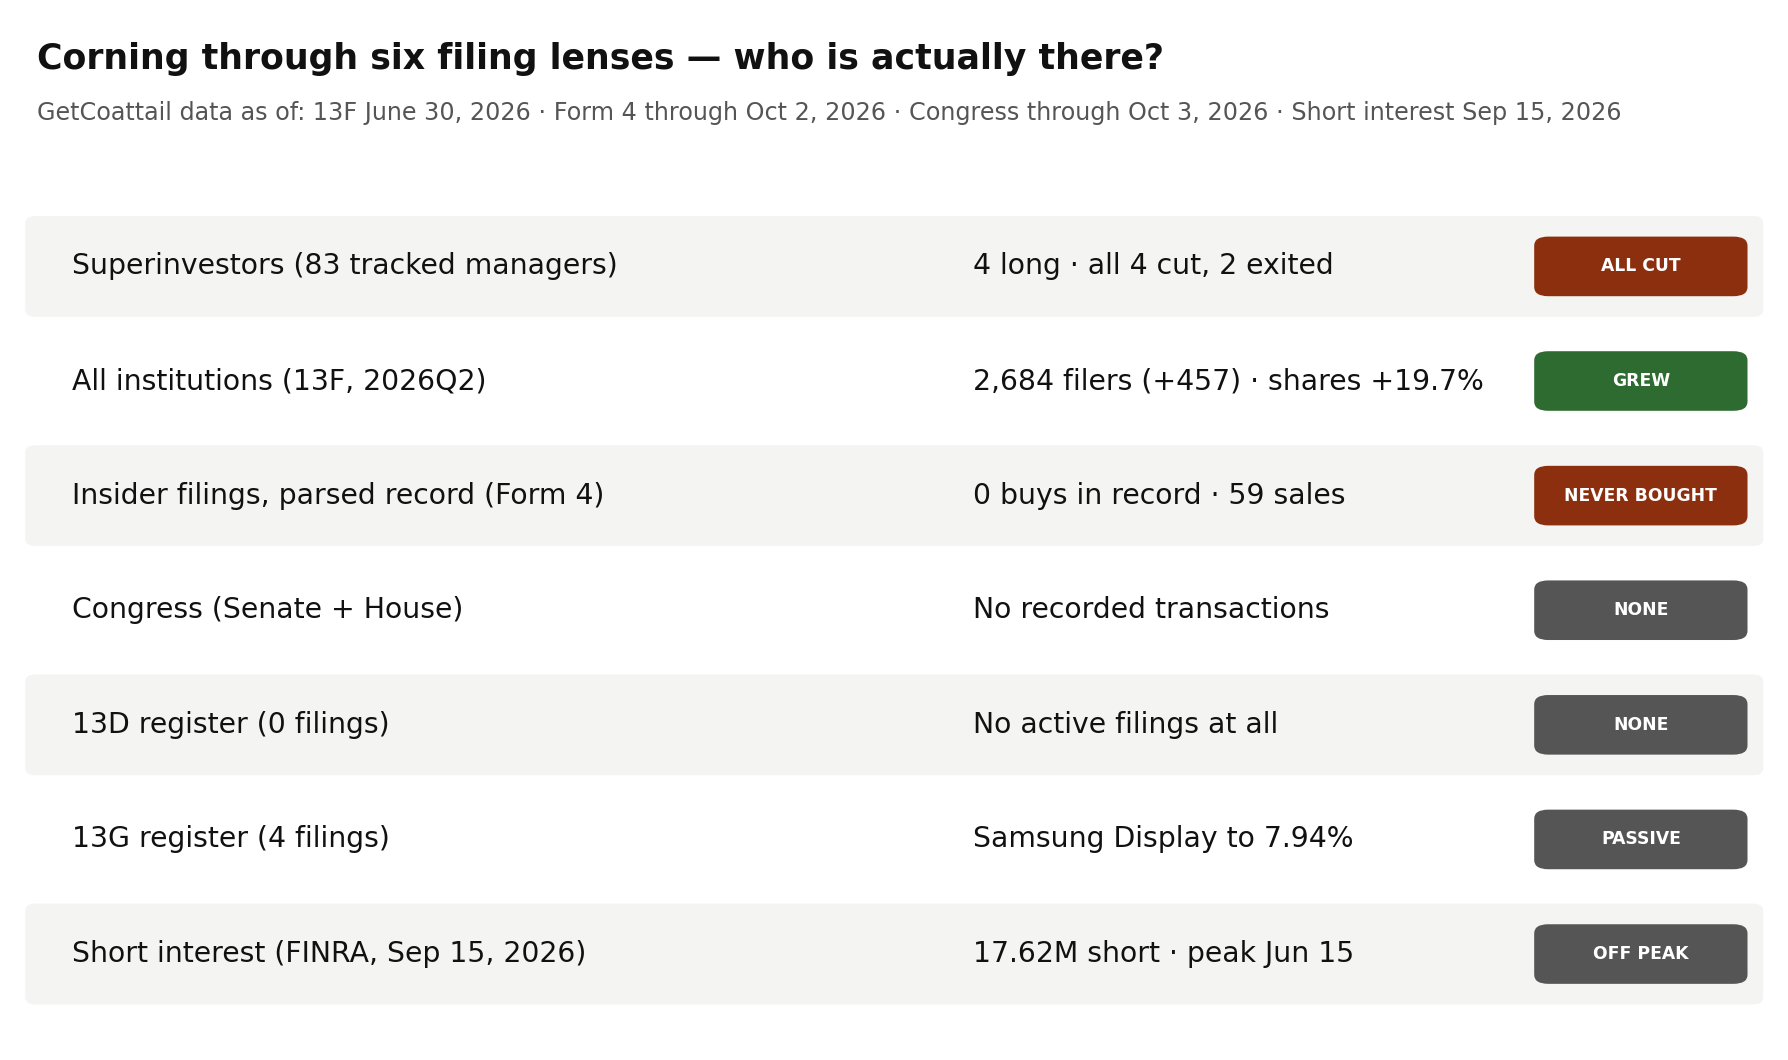
Lens 2 — institutions: 457 more filers, 103.1 million more shares. At June 30, 2026, 2,684 institutions reported positions, up 457 from 2,227 at March 31 (+20.52%), 2,668 of them long. Reported shares rose 19.72%, from 522,842,802 to 625,947,736 shares — up 103,104,934 shares in the quarter the price rose 87.9%. Reported value rose 132.69% to $165,234,768,536; the aggregate includes option rows, so we headline filer and share counts and label dollars "reported" (see methodology).
Lens 3 — insiders: no purchase in the record at all. The parsed Form 4 record holds 264 filings through October 2, 2026. Purchases total zero transactions — in the 90-day window, the last year and the full record alike — with zero buyers in every window, and officer purchases are likewise zero in every window. Sales total 59 transactions totalling 1,280,271 shares and $141,580,154.37, by 16 sellers, 54 of them recorded as officer sales. The last year holds 130 filings with no purchases alongside 34 sales — 767,821 shares for $112,203,630.08, by 15 sellers, 31 of them officer sales — and the last 90 days hold 6 filings with no purchases and two sales (22,974 shares for $3,485,642.56), both of them officer sales. We assign no motives.
Lens 4 — Congress: no recorded transactions. None of the three congressional aggregates — the combined record (as of October 3, 2026), the House aggregate (October 3, 2026) or the Senate aggregate (October 1, 2026) — carries an entry for this ticker. This audit reports that absence as recorded, rather than as a zero it cannot verify beyond the aggregates.
Lens 5 — the 5% register: four filings, all passive. Our full parse holds exactly 4 SC 13D/G filings — one SC 13G and three SC 13G/A, with three amendments and no SC 13D-family filing at all — 4 reporting-person rows across 3 names as filed, most recently filed April 29, 2026, matching the site aggregate on every headline field. The register's maximum is Samsung Display Co., Ltd. at 71,000,000 shares (8.3%) as of March 17, 2025, and its second print steps down to 68,000,000 shares (7.94%) as of August 20, 2025. The Vanguard Group prints 0 shares (0.0%) as of March 13, 2026, while Vanguard Capital Management prints 58,226,346 shares (6.77%) as of March 31, 2026; we report them as filed and do not merge them.
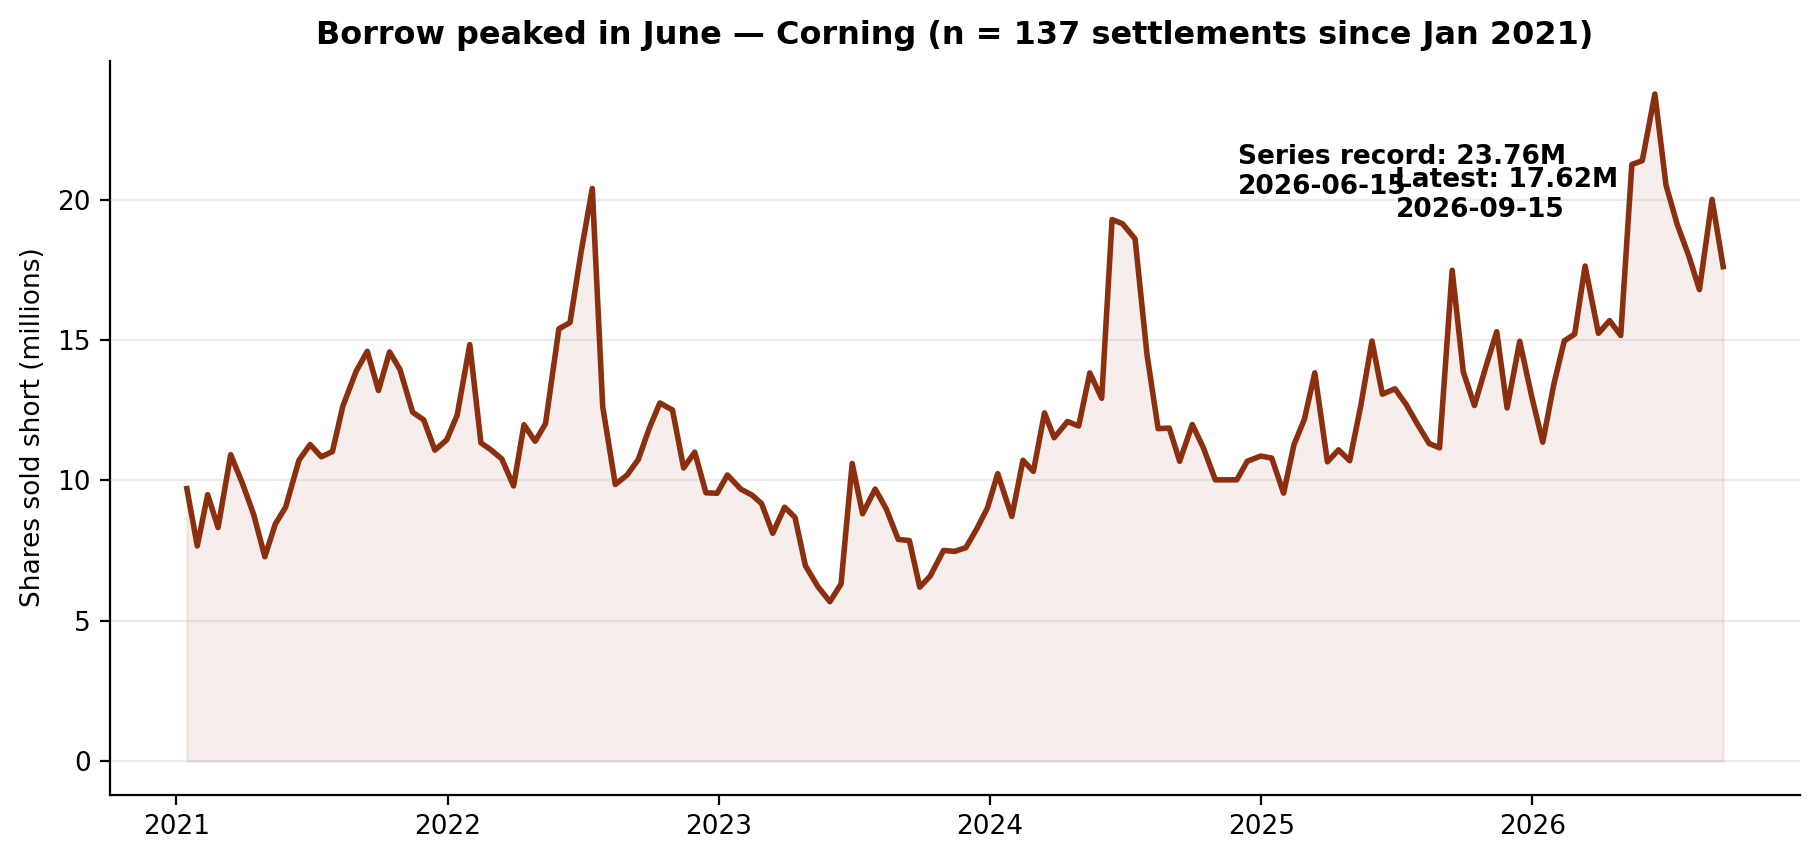
Lens 6 — short interest: 17,615,953 shares, a quarter below a record set in June. As of September 15, 2026 — the most recent of 137 FINRA settlements since January 15, 2021 — 17,615,953 shares were sold short, down 11.96% from the prior settlement. The series maximum, 23,762,888 shares on June 15, 2026 — verified by a maximum query over the whole series — was set two weeks before the June 29 closing high, and the latest reading sits 25.9% below it. The last five settlements read 19,125,152, 17,973,094, 16,795,510, 20,009,517 and 17,615,953: a decline into mid-August, a step back up at August 31, then a fall. Against the year-ago 17,484,284 shares the latest is up 0.8%; against the June 30, 2026 settlement of 20,518,605 it is down 14.1%. Against 861,388,331 shares outstanding, it is 2.05% of the share count, at 1.87 days to cover.
The Gap
The narrative describes an AI-infrastructure winner: a quarter in which the price rose 87.9%, a print that beat on earnings and optical growth, a dividend declared and at least one target raised — followed by a 35.7% slide once guidance, not the quarter, disappointed. The filings describe the broad market and the tracked top moving in opposite directions at the top of that run. The full market held 625,947,736 reported shares at June 30, up 103,104,934 shares (+19.72%), as its filer count rose by 457 to 2,684. The tracked cohort moved the other way, unanimously: 5,351,779 shares at March 31 became 2,852,944 at June 30, down 2,498,835 shares (-46.69%), with all four remaining holders cutting — one of them by 98.7% — and two more managers exiting, including a 1,129,500-share position. The 5% register holds no active filing at all: its largest name is a strategic holder whose reported stake stepped down from 8.3% to 7.94% in 2025. Insiders recorded no purchase in 264 filings — not one, in any window — against 59 sales. Congress records nothing at all. And the borrow peaked at 23,762,888 shares on June 15, two weeks before the closing high, and now stands at 17,615,953 shares, 2.05% of the shares outstanding. One plausible reading is that the second-quarter register absorbed the run broadly while the tracked holders used the strength to reduce, and the borrow crested with the price rather than after it. The record supports each clause separately; it does not say which register is early.
What Would Change the Picture
Nothing above is a recommendation. It is a record. These filings would change the description:
- 1. The 2026Q3 13Fs (filing window closing mid-November 2026). The cohort held 2,852,944 shares at June 30, 95.6% of it Lone Pine's, after every holder cut and two exited in a quarter the price rose 87.9%. A tracked manager adding — or Lone Pine exiting — rewrites this lens either way.
- 2. A first insider purchase, ever, in the record. The record holds zero purchases across 264 filings through October 2, 2026, against 59 sales. One purchase breaks the pattern.
- 3. A first SC 13D, or a new step in the largest 13G chain. Samsung Display's reported stake has printed 8.3% and 7.94% in succession, most recently filed September 10, 2025. A third print — in either direction — or the register's first active filing restarts this lens.
- 4. Whether the borrow keeps unwinding, or rebuilds. Short interest stands at 17,615,953 shares, 25.9% below the June 15, 2026 record of 23,762,888. A reading back above the August 31 print of 20,009,517 marks a rebuild; a reading below the August 14 print of 16,795,510 extends the unwind.
- 5. A first recorded congressional transaction, in either chamber. All three aggregates carry no entry for this ticker. One recorded purchase or sale gives this lens its first entry.
Until one of those prints, the record describes a stock held by four of our 83 tracked superinvestors — 2,852,944 shares, every holder a cutter in the quarter it rose 87.9% — whose insiders have never recorded a purchase, whose 5% register is passive-only, and whose borrow peaked a fortnight before its price did.
As-of & Limits
The lenses rest on different clocks, none live: 13F is a June 30, 2026 snapshot published up to 45 days later; Form 4 runs through October 2, 2026; Congress through October 3, 2026 (Senate October 1); 13D/G through the April 29, 2026 filing; short interest through September 15, 2026; prices end October 2, 2026. Three limits are specific to this name: the congressional aggregates carry no row at all, so Lens 4 reports a recorded absence rather than a verified zero; the full-market aggregate's implied price ($263.98) sits 3.3% above the June 30 close because its reported value sums option rows alongside common-stock rows, so this audit headlines filer and share counts; and the earnings print postdates the June 30 13F snapshot, so the 13F lenses show positioning into the print, not trading on it.
Related reading: One of 83: The Only Superinvestor in McCormick Trimmed 1.6% in Q2. Short Interest Set a Series Record in August. — Filing Tape #71; Three of 83: One Holder Is 89.7% of the Superinvestors' Lowe's Stake. Its Insiders Have Bought Once. — Filing Tape #70; Fifteen of 83: One Holder Is 93.2% of the Superinvestors' Bank of America Stake. Its Insiders Have Never Bought a Share. — Filing Tape #69. Corning's own page: Corning Inc (GLW) on GetCoattail.
Methodology and data notes
- Superinvestor lens: 83 managers collected directly from SEC EDGAR Form 13F (managers_13f collection), positions as of June 30, 2026; Corning identified by CUSIP 219350105. Four distinct managers hold long positions totalling 2,852,944 shares; there are no option rows for this name in the collection. The direction count on the collection's labels, across the long rows, is four DECREASED (Stephen Mandel - Lone Pine Capital, -26.6%; Mairs & Power Funds, -3.2%; Dodge & Cox Funds, -4.6%; Lee Ainslie - Maverick Capital, -98.7%); the collection's exit list contains two Corning rows (David Tepper - Appaloosa Management, 1,129,500 shares held at March 31; Steven Check - Check Capital Management, 5,050 shares). Quarter-to-quarter cohort totals (5,351,779 long shares at March 31; 2,852,944 long shares at June 30, a change of -2,498,835 shares or -46.69%) are from the site pipeline's holdings files on the same CUSIP basis in both quarters, and the pipeline's second-quarter totals match the EDGAR collection exactly on both shares and value (differences of 0 shares and $0). Lone Pine Capital's share of the cohort is 95.6% = 2,728,058 / 2,852,944.
- Full-market lens: SEC Form 13F Data Sets full-market aggregation. The primary table is the full13f collection's by-ticker file (holders = distinct filers reporting the CUSIP; 2,668 reported long positions out of 2,684 filers). Corning reports under a single CUSIP, 219350105, and the backfill fixtures' by-CUSIP row matches the by-ticker row exactly on holders, shares, reported value, prior holders and prior value. The by-ticker file's entered/exited fields (1,991 and 1,534, a net of +457 that matches the change in holder count) are gross flows, so this audit headlines the net change. Reported-value caution: the aggregate value ($165,234,768,536 over 625,947,736 shares) implies $263.98 per share against a June 30, 2026 close of $255.43 in our price file, a gap of +3.3% — printed here as found. The aggregate sums the VALUE of every information-table row — including put and call option rows — while the share count covers long common-stock rows only, so we headline filer and share counts and label dollar values "reported."
- Insider lens: full-parse Form 4 aggregation (agg_by_ticker), record as of October 2, 2026 (264 filings). Sale and purchase counts are transaction-code counts (S and P) in non-derivative rows; grants and exercises are not counted as purchases, and one filing can contain many transaction rows. Purchase transactions total 0 across the parsed record (0 shares, $0, zero buyers) and officer purchase transactions total 0 in the 90-day window, the last year and the full record alike (officerBuyTx 0 and officerBuyValUsd $0 in each). Sale transactions total 59 across the record (1,280,271 shares, $141,580,154.37, 16 sellers, 54 of them recorded as officer sales); the last year holds 34 (767,821 shares, $112,203,630.08, 15 sellers, 31 officer sales) alongside no purchases, and the 90-day window holds no purchases and two sales (22,974 shares, $3,485,642.56), both officer sales. The site's insider aggregate (compiled as of October 14, 2026, 90-day window) matches the full parse's 90-day window exactly on counts and values, including the absence of any recorded purchase. No purchase-value field exists to check, because there are no purchases; the full-parse aggregate's sale-value totals imply $151.72 per share for the 90-day window, $146.13 for the one-year window and $110.59 for the full record, each inside the traded price range of its window on our price file ($124.05 to $194.80 for the 90-day window, $78.03 to $255.69 for the one-year window, and $26.59 to $255.69 across the price file), so all sale totals are cited as figures in this article.
- 13D/G lens: full-parse SC 13D/G parsed filings (4 filings matching issuer CIK 24741 on CUSIP 219350105, 4 reporting-person rows across 3 names as filed: one SC 13G filing and three SC 13G/A amendments, with no SC 13D-family filing), filings through April 29, 2026. The site aggregation's by-ticker row for Corning (4 filings, 0 D-filings, 4 G-filings, 3 amendments, 3 reporters, latest date April 29, 2026, maximum 8.3% and 197,226,346 reported shares) matches the parsed filings on filings, form mix, amendments, latest date, maximum and reported-share total; its reporter count of 3 is the count of distinct reporter names, and the parsed filings hold 4 reporting-person rows because Samsung Display reports in two separate filings. The parsed reporting-person rows sum to 197,226,346 shares, but that total sums reporting-person rows across different dates, so it is not used as a stake figure in the article. Samsung Display Co., Ltd.'s rows (71,000,000 shares at 8.3% as of March 17, 2025, filed April 7, 2025, SC 13G/A — the register maximum; 68,000,000 shares at 7.94% as of August 20, 2025, filed September 10, 2025, SC 13G/A), The Vanguard Group's row (0 shares at 0.0% as of March 13, 2026, filed March 26, 2026, SC 13G/A) and Vanguard Capital Management's row (58,226,346 shares at 6.77% as of March 31, 2026, filed April 29, 2026, SC 13G) are reported as filed, under the names exactly as they appear. The Vanguard-named rows are separate reporting persons as filed and are not merged in this audit. The parsed coverage for this issuer holds these 4 filings; a 5% holder that has not filed in the covered window would not appear here.
- Congress lens: Senate PTR archive and House PTR archive as maintained on this site. The combined record (as of October 3, 2026), the House aggregate (as of October 3, 2026) and the Senate aggregate (as of October 1, 2026) each carry no row for this ticker, so this audit reports that no transaction is recorded in these collections; it does not reconstruct individual filers and does not present the absence as a verified market-wide zero beyond the aggregates.
- Short interest lens: FINRA Equity Short Interest files (biweekly settlement dates), collected directly from FINRA's public distribution. The published series covers 137 settlements from January 15, 2021 (9,708,023 shares) to September 15, 2026. The latest reading is 17,615,953 shares on September 15, 2026, down 11.96% from the prior settlement (20,009,517 on August 31, 2026). The series maximum is 23,762,888 shares on June 15, 2026 (verified by a maximum query over the series, not read off the latest row), so the latest reading sits 25.9% below a record set in mid-June. The year-ago settlement (September 15, 2025) printed 17,484,284 shares, so the latest reading sits 0.8% above a year ago. The series minimum is 5,682,623 shares on May 31, 2023. The June 30, 2026 settlement printed 20,518,605 shares, so the latest reading sits 14.1% below the 13F snapshot date's borrow. FINRA publishes each settlement about two weeks after the fact, so the October price action is not yet in this series. The share-count ratio (2.05%) uses the fundamentals file's shares-outstanding figure below.
- Fundamentals note: our fundamentals collection carries Corning's revenue of $15,629,000,000, net income of $1,596,000,000 and assets of $30,976,000,000, each labelled fiscal 2025 in the file (the company's fiscal year ends December 31). The file is marked ok for this name, with no missing fields: shares outstanding of 861,388,331 (as of July 24, 2026 in the file, sourced in the file to the cover share count) and a file-computed market value of $145,548,787,340.57. The file's price for the name is $168.97 as of October 6, 2026; our daily-close file ends October 2, 2026 at $164.19, and we keep the two files' figures separate rather than blending them.
- Prices: our own daily-close file for Corning through October 2, 2026 ($164.19 close, +87.5% year to date on that file; 252-session closing high $255.69 on June 29, 2026, so the last close sits 35.8% below it; 252-session closing low $78.03 on November 20, 2025, so the last close sits 110.4% above it; closes of $135.97 at March 31, 2026 and $255.43 at June 30, 2026, a second-quarter change of +87.9%; change from June 30 to October 2 of -35.7%; change from the September 30, 2025 close of $82.03 of +100.2%). The series in our price file begins June 1, 2021 at $43.12 and holds 1,342 rows.
- Market context sources: MarketBeat trending-stocks list (Corning ranked tenth, $146.88, moderate-buy consensus, average target $177.56; checked October 14, 2026); second-quarter 2026 results (earnings of $0.78 per share against a $0.76 consensus; revenue of $4.74 billion; optical communications sales up 32% to $2.07 billion with segment net income up 77%; gross margin 39.6%; free cash flow of $1.42 billion; third-quarter guidance of $0.85 to $0.89 per share; shares down about 12% on the print), as carried by MarketBeat, checked October 14, 2026; third-quarter results due October 27, 2026 with an expected $0.88 per share, as carried by Barchart and the Zacks earnings calendar, checked October 14, 2026; the $0.28 quarterly dividend declared October 7, 2026 (record date November 13, payment December 11), as carried by American Banking News, and Truist's target increase from $175 to $182, as carried in The Cerbat Gem's weekly summary, checked October 14, 2026. Figures we could not confirm against two sources were left out; the external items above are reported speech from those outlets, not GetCoattail measurements.
- Corning is in the GetCoattail stock-page universe: Corning Inc (GLW) stock page. Series data: glw_lens_data.csv · glw_short_interest_series.csv. Earlier audits: McCormick · Lowe's.
Past patterns are not a promise of future results. For education only — not investment advice.
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history
- v1.0 — October 14, 2026: first publication.