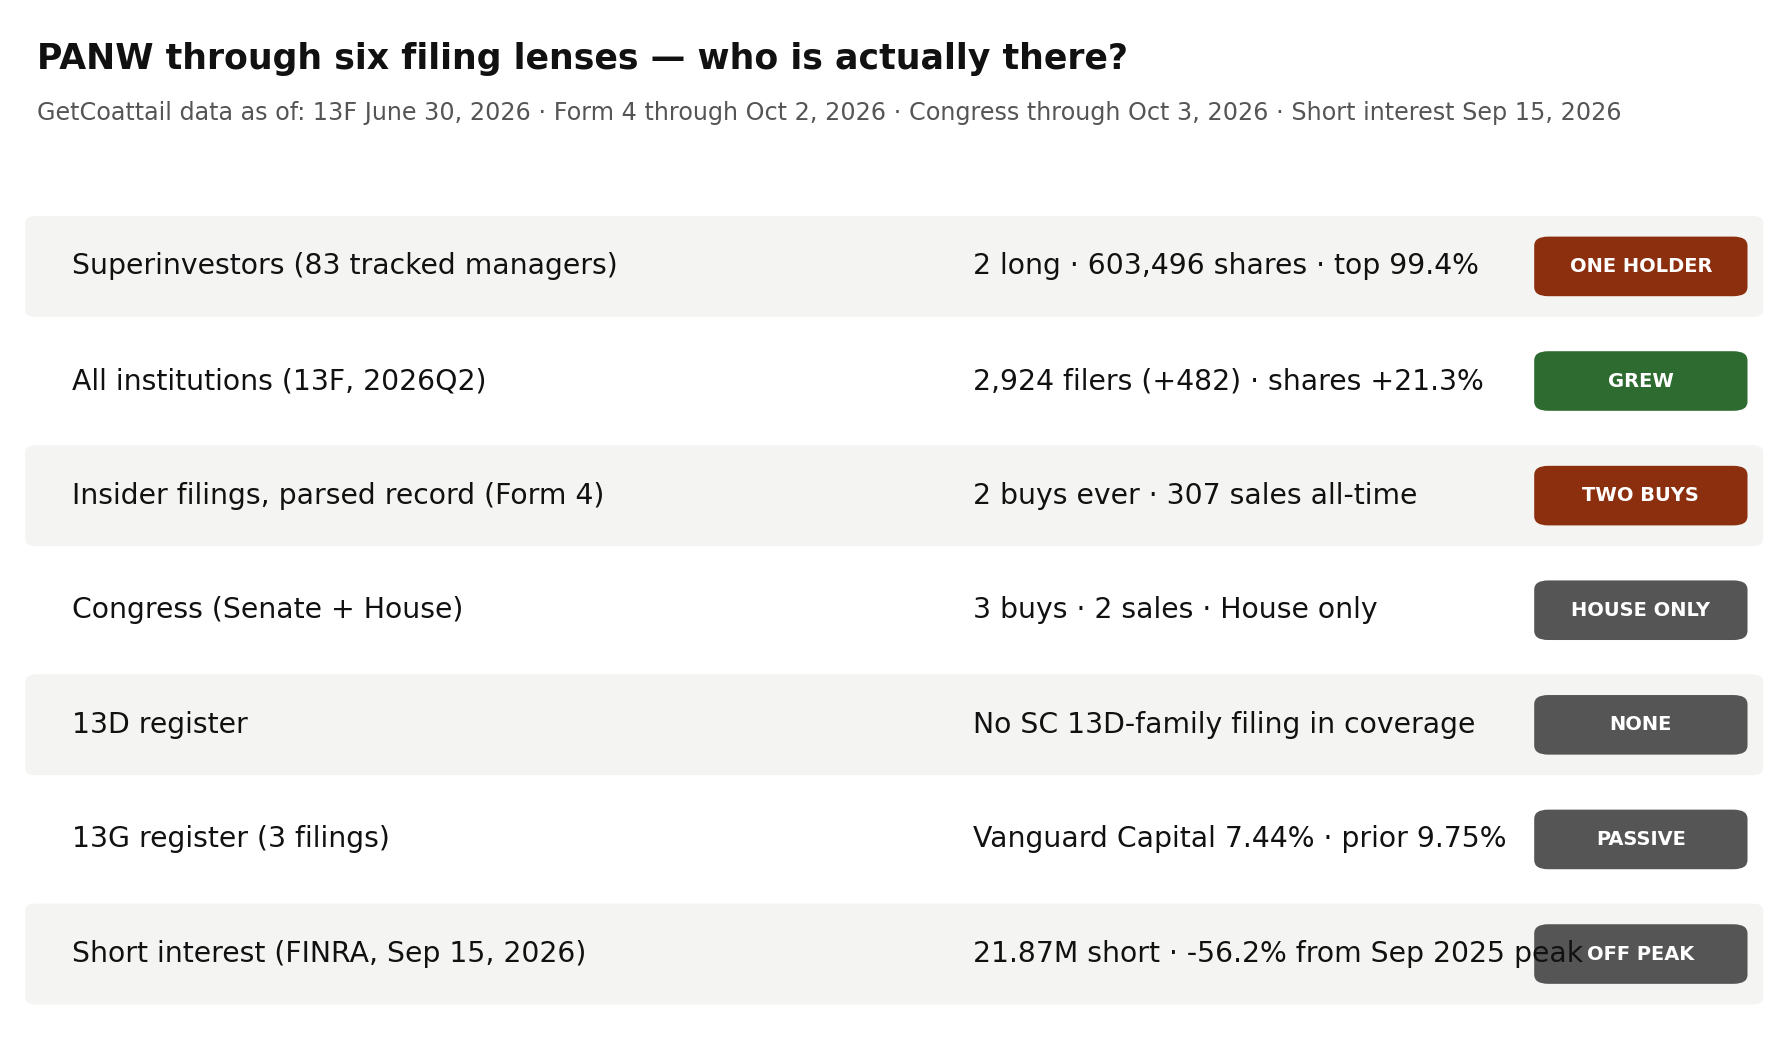
GetCoattail Research — The Filing Tape #63. Palo Alto Networks has more than doubled this year, set record closes in early October, and then dropped sharply on October 12 after a downgrade that called the shares stretched. The filings describe the positioning underneath: two tracked superinvestors holding 603,496 shares, with 99.4% of them in a single holder's row; a full market that added 482 filers and 116,291,731 shares in the second quarter; an insider record that holds exactly two purchases against 307 sales; and a borrow that stands at less than half its level of a year ago.
Start with the narrative. The stock's year is the story: Palo Alto Networks closed our price file's second quarter at $341.02, up 112.7% from $160.32 at March 31, and the climb did not stop at the quarter-end — the file's last close, $403.24 on October 2, is itself the highest close in its last 252 sessions, and market data compiled elsewhere put the October 6 close at $419.91, reported as the highest close in the stock's history, with a 52-week range of $139.57 to $432.33 as of October 9. The business headlines ran with the price: the most recent quarter, reported September 1, delivered earnings of $1.02 a share against a $0.98 consensus, and the fiscal year that ended in July produced revenue of $11.48 billion, up about a quarter from the year before, on net income of $307 million, down sharply. On October 12 the argument turned: Phillip Securities cut the shares to neutral from buy with a $346 target, describing the valuation — around 97 times earnings against a five-year average of 54 — as stretched after a 2026 climb of more than 120%, and the shares fell about 4.7% in the session before closing down 3.6% at $403.81, a day after closing at $418.78. The consensus sits below the price: MarketBeat's count is moderate buy, 38 buys against 12 holds, with an average target of $391.32. MarketBeat's trending table, checked October 13, still had the name at rank 17, with searches up about a fifth. A director's sale of 250 shares on October 9, at $412.28, was also in the week's news.
Now the filings. For PANW — the sixty-third Filing Tape audit — the tape shows a two-name tracked cohort that is really one name, a broad register that grew by nearly a fifth in a quarter when the price more than doubled, a small passive 5% register, an insider record with two purchases in it, a congressional record that exists in only one chamber, and a borrow cut by more than half in a year.
Lens 1: the superinvestors — two holders, and one of them is the register
We track 83 large, mostly long-only managers whose 13F portfolios we collect directly from SEC EDGAR. As of June 30, 2026, 2 held PANW long totalling 603,496 shares worth $205,804,206, with no option rows in the register. The direction count on the collection's own labels, across the long rows, is one new and one increased — and the register has no exit row for this name at all. The cohort total moved from 532,679 long shares at March 31 to 603,496 at June 30, a change of +13.29%, a difference of +70,817 shares.
Almost all of what remains sits in one row. Mairs & Power Funds holds 599,841 shares worth $204,557,778, a 1.88% portfolio weight — 99.4% of the tracked cohort's PANW shares — flagged increased, and the pipeline's March file carries the position at 532,679 shares, so the label's +12.6% and the continuity agree exactly: the March register's only PANW row is this same holder, grown. The other row is Lee Ainslie's Maverick Capital, new in the quarter with 3,655 shares worth $1,246,428, a 0.01% portfolio weight and 0.6% of the cohort. The cohort's implied price, $341.02 per share, sits exactly on the June 30 close of $341.02. This register's second quarter, in full: one holder adding an eighth to a position it already owned, one holder opening a position of 3,655 shares — in a quarter when the price rose from $160.32 to $341.02, a change of +112.7%.
Lens 2: institutions — 482 more filers, 116.3 million more shares
Zoom out to the whole 13F market and the register grew in every direction the tracked cohort did not. At June 30, 2026, 2,924 institutions reported positions, up 482 from 2,442 at March 31 (+19.74%), and 2,902 of them reported long positions. Reported shares rose 21.31%, from 545,833,325 to 662,125,056 shares — 116,291,731 more shares than the prior quarter. Reported aggregate value rose 164.67% to $239,430,288,180; the aggregate includes option rows, so we headline filer and share counts and label dollars "reported" (see methodology). The implied value per share, $361.61, sits 6.0% above the June 30 close of $341.02 — a gap published as found, in a quarter when the price itself more than doubled and per-row values were struck at different moments of a steep climb. Where the tracked cohort's register is two names and 603,496 shares, the broad register is nearly three thousand filers who, in aggregate, ended the quarter holding about a fifth more shares than they started it with.
Lens 3: the 5% register — three passive filings, one complex
Our full parse holds exactly 3 SC 13D/G filings for PANW — one SC 13G and two SC 13G/A, and no SC 13D-family filing at all — three reporting-person rows across two names, the most recent filed April 30, 2026. The register's maximum is The Vanguard Group at 65,268,469 shares (9.75%) as of September 30, 2025, filed October 30, 2025. Its later row runs the other way: The Vanguard Group prints 0 shares (0.0%) as of March 13, 2026, filed March 27, 2026 — the same re-papering pattern this series has recorded at other names, a stake moving between reporting entities inside one complex. The remaining row is the receiving side of that move: Vanguard Capital Management at 60,785,782 shares (7.44%) as of March 31, 2026, filed April 30, 2026. That is the whole 5% register in our parsed coverage: one index complex, reporting under two names across three filings, and no activist paper of any kind.
Lens 4: insiders — two purchases in the record
The parsed Form 4 record holds 112 filings through October 2, 2026. Across the whole record, open-market purchases total 2 transactions — both of them within the last year, both recorded as officer purchases, both by a single buyer — totalling 68,085 shares and $9,999,976.89. Sales total 307 transactions, totalling 6,831,579 shares and $1,276,592,844.72, by ten sellers, 268 of them recorded as officer sales. The recent windows sharpen the shape: the last year holds 63 filings with the same 2 purchases against 103 sales totalling 709,267 shares and $158,725,918.50; the last 90 days hold 13 filings with no purchase at all against 26 sales totalling 54,260 shares and $20,804,691.03, by six sellers. Our site's insider aggregate, compiled as of October 13 on a 90-day window, is close but not identical — 0 purchases, 25 sales, five sellers, $20,561,896.03 — and this audit prints the full parse as the record and says so. One boundary matters: the director sale reported in the week's news, dated October 9, falls after this record's October 2 cutoff and is in none of these windows. We assign no motives to any of it; the record itself — two purchases, ever, in our parsed coverage, against 307 sales — is the fact.
Lens 5: Congress — a record in one chamber only
The congressional record we maintain exists for this name, but only on one side of the Capitol. The combined record (as of October 3, 2026) carries 3 recorded purchases and 2 recorded sales, two members, party D only, with the most recent purchase dated July 16, 2026. The House aggregate (as of October 3, 2026) carries the whole of it — the same 3 buys, 2 sales, two members and July 16 last-buy date. The Senate aggregate (as of October 1, 2026) carries no PANW row at all: in our coverage, no Senate record for this ticker exists to agree or disagree. Each part of that statement is printed as the aggregates carry it; this audit does not reconstruct individual filers beyond what the aggregates state.
Lens 6: short interest — 21,871,670 shares, less than half the year-ago reading
FINRA's files carry the borrow across 137 settlements, from January 15, 2021. As of September 15, 2026 — the most recent settlement — 21,871,670 PANW shares were sold short, with days-to-cover of 3.02. That reading rose 2.15% from the prior settlement's 21,411,706 shares on August 31, 2026, after 22,414,335 on August 14, 21,000,807 on July 31 and 20,423,492 on July 15. The series maximum is 49,937,430 shares on September 15, 2025, a fact we verified by taking the maximum across the whole series rather than reading it off the latest row — and that date is also the year-ago settlement, so the latest reading is 56.2% below the peak and 56.2% below a year ago on the same comparator. The June 30, 2026 settlement — the date the 13F lenses snapshot — printed 25,002,502 shares; the latest reading sits 12.5% below it. The series minimum is 4,609,769 shares on January 29, 2021; the latest reading sits 374.5% above that low, and the series' first settlement, on January 15, 2021, printed 4,810,905 shares. Against the fundamentals file's 818,000,000 shares outstanding, the latest reading is 2.67% of the share count.
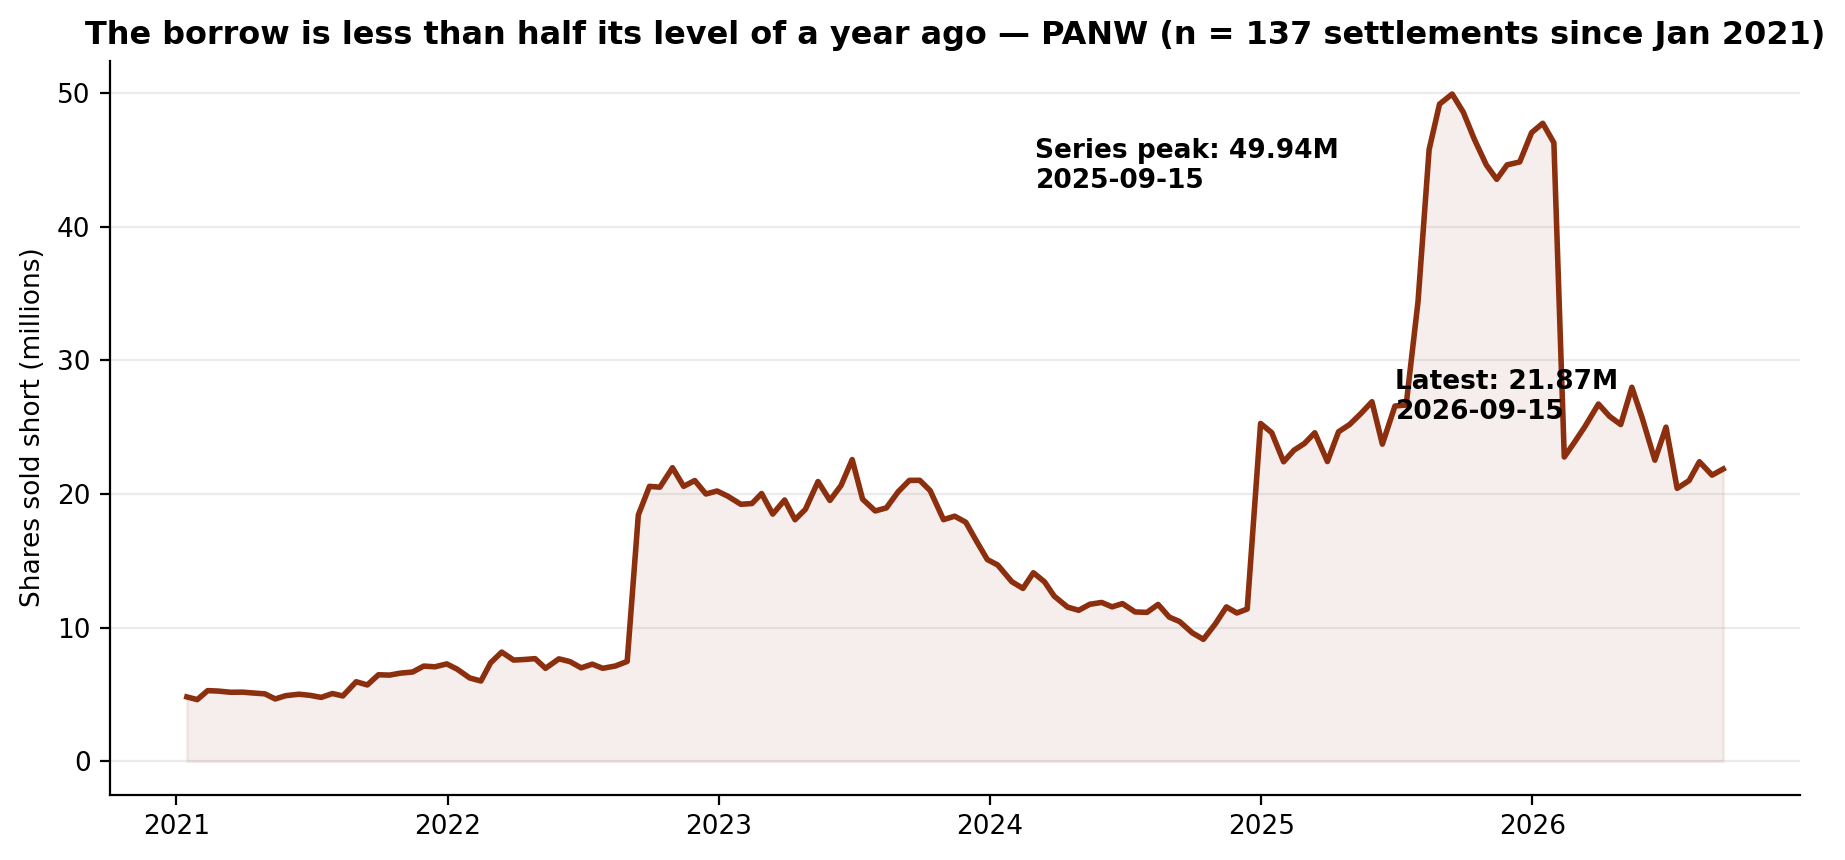
The borrow is neither crowded nor gone. It is a position that peaked a year ago at nearly 50 million shares and has since been cut by more than half, while the price it was shorted against kept rising.
The gap, stated plainly
The narrative describes a stock that has risen about 119% this year on our price file, set record closes in early October, beat its last earnings consensus, and then drew a downgrade whose $346 target sits below the price and a consensus target of $391.32 that also sits below it. The filings describe the positioning that preceded it. The tracked superinvestors held 603,496 shares at June 30 across two holders, having moved +13.29% in a quarter when the price rose 112.7% — with one holder, Mairs & Power, carrying 99.4% of the cohort after adding 12.6%, and the only other row a new position of 3,655 shares. The full market moved far more: 662,125,056 reported shares, up 116,291,731, across 2,924 filers — 482 more than the prior quarter. The 5% register printed 3 filings, all passive, all from one complex: a Vanguard Group stake at 9.75%, a Vanguard Group row at zero, and a Vanguard Capital Management stake at 7.44%. Insiders, across 112 parsed filings, recorded 2 purchases — both by one officer-buyer, both in the last year — against 307 sales. Congress records 3 purchases and 2 sales, all of them in the House record; the Senate record holds no row for this name. And the borrow stands at 21,871,670 shares — 56.2% below the reading of a year ago, which was also its peak, and 12.5% below its June 30 level. One plausible reading is that the registers are describing a name the broad market crowded into while the concentrated cohort barely participated: the full register added about a fifth more shares and 482 filers in the very quarter the price doubled, the tracked cohort's entire position fits in two rows and one of them is 0.6% of it, the insider tape holds two purchases against 307 sales, the congressional tape exists in only one chamber, and the short side has been more than halved from its peak — all of the 13F part of it snapshot at June 30, when the stock closed at $341.02, before the record closes and the downgrade the current story rests on. The record supports each clause separately; it does not say which register is right, and it cannot — the tracked cohort's whole position is a June 30 snapshot of 603,496 shares, taken before the quarter that made the narrative.
What would change the picture
Nothing above is a recommendation. It is a record. These are the filings that would change the description:
- 1. The 2026Q3 13Fs (filing window closing mid-November 2026). The tracked cohort held 603,496 shares at June 30 across two holders, after a +13.29% move made of one holder's +12.6% add and one new 3,655-share row. Whether Mairs & Power builds on its 599,841-share position after a quarter in which the price rose a further 18.2% to October 2, whether Maverick's row grows or disappears, and whether any third tracked name appears are the first things the next register will answer.
- 2. A third insider purchase — or a first one outside a single buyer. The parsed record holds 2 purchases in total, both by one buyer and both recorded as officer purchases, against 307 sales. A purchase by any second insider, at any size, would widen this lens beyond a single name; a 90-day window with no sale in it would change its recent shape just as much.
- 3. Whether the borrow rebuilds toward its June 30 level, or keeps fading. Short interest stands at 21,871,670 shares, 12.5% below the June 30, 2026 settlement of 25,002,502 and 56.2% below the September 15, 2025 peak of 49,937,430. A reading back above 25,002,502 would mark a rebuild into strength; a reading below the July 15 print of 20,423,492 would extend the fade.
- 4. A first Senate record, at any size. The combined congressional record carries 3 purchases and 2 sales, all of them House. A single Senate purchase or sale would give this lens a second chamber for the first time in our coverage.
- 5. A first SC 13D, or a new 5% name. The 5% register in our parsed coverage holds three passive filings from one complex and no SC 13D-family filing. An original 13D from any filer, or a 13G from outside the Vanguard complex, would give this lens its first non-passive, non-single-complex content.
Until one of those prints, the record describes a stock held by two of our 83 tracked superinvestors — 603,496 shares, moved +13.29% in the quarter its price rose 112.7%, with one holder carrying 99.4% of the stake — whose full market added 116,291,731 reported shares across 482 more filers, whose insiders have recorded 2 purchases against 307 sales in the parsed record, whose congressional register is 3 House purchases and 2 House sales with no Senate row at all, and whose borrow has fallen 56.2% from a peak set exactly a year before its latest reading — all of it snapshot at June 30, before the record closes and the downgrade the current story rests on.
Related reading: Fourteen of 83: Wells Fargo's Superinvestors Stood Still as the Full Market Added 15.0%. Its Insiders Have Never Bought a Share. — Filing Tape #62; Three of 83: The Superinvestors Cut Marathon Petroleum 91.8% in Q2 While the Full Market Added 19.4% — Filing Tape #61; Zero of 83: The Superinvestors Aren't in IREN — Filing Tape #1. PANW's own page: Palo Alto Networks Inc (PANW) on GetCoattail.
Methodology and data notes
- Superinvestor lens: 83 managers collected directly from SEC EDGAR Form 13F (managers_13f collection), positions as of June 30, 2026; PANW identified by CUSIP 697435105. Two distinct managers hold long positions totalling 603,496 shares; there are no option rows for this name in the collection. The direction count on the collection's labels, across the long rows, is one new and one increased; the collection's exit list contains no PANW row. Quarter-to-quarter cohort totals (532,679 long shares at March 31; 603,496 long shares at June 30; change +13.29%) are from the site pipeline's holdings files on the same CUSIP basis in both quarters, and the pipeline's second-quarter totals match the EDGAR collection exactly on both shares and value (differences of 0 shares and $0). The March file's single PANW row (532,679 shares) is matched to Mairs & Power Funds by filing continuity, and its move to 599,841 shares (+12.6%) agrees with the collection's INCREASED label and its stated +12.6% share change; Maverick Capital's row is labelled NEW and has no March row. Mairs & Power's share of the cohort is 99.4% = 599,841 / 603,496.
- Full-market lens: SEC Form 13F Data Sets full-market aggregation. The primary table is the full13f collection's by-ticker file (holders = distinct filers reporting the CUSIP; 2,902 reported long positions out of 2,924 filers). PANW reports under a single CUSIP spelling, 697435105, and the backfill fixtures' by-CUSIP file carries the same row — the cross-check matches on every field (holders, shares, reported value, prior holders and prior reported value). The by-ticker file's entered/exited fields (2,074 and 1,592, a net of +482 that matches the change in holder count) are gross flows, so this audit headlines the net change. Reported-value caution: the aggregate value ($239,430,288,180 over 662,125,056 shares) implies $361.61 per share against a June 30, 2026 close of $341.02 in our price file, a gap of +6.0% — printed here as found. The aggregate sums the VALUE of every information-table row — including put and call option rows — while the share count covers long common-stock rows only, so we headline filer and share counts and label dollar values "reported."
- Insider lens: full-parse Form 4 aggregation (agg_by_ticker), record as of October 2, 2026 (112 filings). Sale and purchase counts are transaction-code counts (S and P) in non-derivative rows; grants and exercises are not counted as purchases, and one filing can contain many transaction rows. Purchase transactions total 2 across the parsed record (68,085 shares, $9,999,976.89, one buyer, both recorded as officer purchases); the last year holds both 2 and the 90-day window holds 0. Sale transactions total 307 across the record (6,831,579 shares, $1,276,592,844.72, ten sellers, 268 of them recorded as officer sales); the last year holds 103 (709,267 shares, $158,725,918.50, eight sellers, 66 officer sales) and the 90-day window holds 26 (54,260 shares, $20,804,691.03, six sellers, 10 officer sales). The site's insider aggregate (compiled as of October 13, 2026, 90-day window) carries 0 purchases, 25 sales, five sellers and $20,561,896.03 for this name — close to, but not identical with, the full parse's 90-day window (26 sales, six sellers) — so this audit prints the full parse as the record and the site aggregate alongside it, here and in the lens text. A director sale dated October 9, 2026, reported in the press (see market context sources) falls after this record's October 2 cutoff and appears in none of these windows.
- 13D/G lens: full-parse SC 13D/G parsed filings (3 filings matching issuer CIK 1327567 on CUSIP 697435105, 3 reporting-person rows across 2 names: one SC 13G filing and two SC 13G/A amendments, no SC 13D-family filings), filings through April 30, 2026. The site aggregation's by-ticker file carries the same totals (3 filings, 2 reporters, latest filing April 30, 2026, maximum 9.75%, total reported 126,054,251 shares), so the aggregate and the parse agree here; the aggregation's total sums reporting-person rows across different dates and entities, so it is not used as a stake figure in the article. The Vanguard Group's rows (65,268,469 shares at 9.75% as of September 30, 2025, filed October 30, 2025, SC 13G/A; then 0 shares at 0.0% as of March 13, 2026, filed March 27, 2026, SC 13G/A) and Vanguard Capital Management's row (60,785,782 shares at 7.44% as of March 31, 2026, filed April 30, 2026, SC 13G) are reported as filed, under the reporting-person names exactly as they appear. No reason for any change is asserted — the filings themselves are the record. The parsed coverage for this issuer holds these 3 filings; a 5% holder that has not filed in the covered window would not appear here.
- Congress lens: Senate PTR archive and House PTR archive as maintained on this site. The combined record (as of October 3, 2026) carries 3 recorded purchases and 2 recorded sales, a most-recent purchase date of July 16, 2026, and an aggregate member count of two (party D) for this ticker; the House aggregate (as of October 3, 2026) carries the identical record, and the Senate aggregate (as of October 1, 2026) carries no PANW row at all, so the combined record is the House record alone. Transaction counts are reported as the aggregates carry them; this audit does not reconstruct individual filers from the aggregate beyond what the aggregate itself states.
- Short interest lens: FINRA Equity Short Interest files (biweekly settlement dates), collected directly from FINRA's public distribution. The published series covers 137 settlements from January 15, 2021 (4,810,905 shares) to September 15, 2026. The latest reading is 21,871,670 shares on September 15, 2026, up 2.15% from the prior settlement (21,411,706 on August 31, 2026), which had fallen from 22,414,335 on August 14, 2026, following 21,000,807 on July 31 and 20,423,492 on July 15. The series maximum is 49,937,430 shares on September 15, 2025 (verified by a maximum query over the series, not read off the latest row), so the latest reading sits 56.2% below the peak; because the peak date is also the year-ago settlement, the year-over-year change is the same -56.2% on the same comparator, and the article says so rather than presenting them as two separate facts. The series minimum is 4,609,769 shares on January 29, 2021, so the latest reading sits 374.5% above the low. The June 30, 2026 settlement printed 25,002,502 shares, so the latest reading sits 12.5% below the 13F snapshot date's borrow. FINRA publishes each settlement about two weeks after the fact, so the October price action is not yet in this series. The share-count ratio (2.67%) uses the fundamentals file's shares-outstanding figure below.
- Fundamentals note: our fundamentals collection carries PANW's revenue of $11,480,000,000, net income of $307,000,000 and assets of $48,460,000,000, each labelled fiscal 2026 in the file. The file is marked ok for this name, with no missing fields: shares outstanding of 818,000,000 (as of August 31, 2026 in the file, sourced in the file to the issuer's reported shares-outstanding figure) and a file-computed market value of $343,486,382,995.61. The file's price for the name is $419.91 as of October 6, 2026; our daily-close file ends October 2, 2026 at $403.24, and we keep the two files' figures separate rather than blending them.
- Prices: our own daily-close file for PANW through October 2, 2026 ($403.24 close, +118.9% year to date on that file; the October 2 close is itself the 252-session closing high; 252-session closing low $141.67 on February 24, 2026; closes of $160.32 at March 31, 2026 and $341.02 at June 30, 2026, a second-quarter change of +112.7%; change from June 30 to October 2 of +18.2% ((403.24 / 341.02) − 1); change from the 252-session low of +184.6% ((403.24 / 141.67) − 1)). The series in our price file begins June 1, 2021 at $60.06.
- Market context sources: MarketBeat Trending table (rank 17 for PANW; price $403.83, -3.6%; 23 searches, +21.05% — checked October 13, 2026); the Phillip Securities action (October 12, 2026; downgrade to neutral from buy, $346 target, valuation described at about 97 times earnings against a five-year average of 54, and a 2026 climb of more than 120% — StockStory, October 12, 2026); the October 12 session (shares fell about 4.7% intraday and closed down 3.6% at $403.81 after a previous close of $418.78, up 5.1% — StockStory, October 12, 2026, and MarketBeat data via Zolmax, October 12, 2026); consensus counts (moderate buy, 38 buys and 12 holds, average target $391.32 — MarketBeat as reported by Watch List News, October 12, 2026); the director sale (Aparna Bawa, 250 shares at $412.28 for $103,070 on October 9, 2026 — Zolmax, October 12, 2026); record closes and range (October 6 close $419.91, up 3.23%, reported as the highest close in the stock's history on StockAnalysis-compiled Nasdaq data; intraday high $432.33; 52-week range $139.57–$432.33 as of October 9, 2026 — Respect Investment summary and ad-hoc-news, checked October 13, 2026); the most recent quarter (fiscal fourth quarter reported September 1, 2026; earnings of $1.02 a share against a $0.98 Zacks consensus — Zacks earnings calendar, checked October 13, 2026); fiscal 2026 annual figures (revenue $11.48 billion, up 24.5% from $9.22 billion; net income $307 million, down 72.9% from $1.13 billion — annual-data summary via ad-hoc-news, October 12, 2026; the revenue and net-income levels match our fundamentals file). Calendar estimates for the next earnings date differ across sources (mid-November 2026) and none was confirmed as a company-set date in the sources checked, so this article gives no specific date. Figures we could not confirm against two sources were left out.
- PANW is in the GetCoattail stock-page universe: Palo Alto Networks Inc (PANW) stock page. Series data: panw_lens_data.csv · panw_short_interest_series.csv. Earlier audits: Wells Fargo · Marathon Petroleum · IREN.
Past patterns are not a promise of future results. For education only — not investment advice.
This article describes public filings as of the dates stated. It is not investment advice and makes no recommendation. Filings lag reality: 13F positions are as of June 30, 2026, and later trading is not yet public.
Revision history
- v1.0 — October 13, 2026: first publication.